
CPF interest rate 2026: OA, SA, MA and RA rates explained
CPF & Retirement
By Beansprout • 29 Oct 2026
Why trust Beansprout? We’ve been awarded Best Investment Website at the SIAS Investors’ Choice Awards 2025

Make Beansprout your preferred source on Google
Add us on Google to see more of our insights in your search results
Explore CPF interest rates for 2026: OA at 2.5% and SA, MA and RA at 4%. Understand extra interest, changes after 55 and how interest is calculated.
What happened?
CPF interest rates affect how our savings grow for retirement, housing and healthcare.
For October to December 2026, CPF members will continue to earn a base interest rate of 2.5% p.a. on their Ordinary Account (OA) and 4% p.a. on their Special, MediSave and Retirement Accounts.
The Government has also extended the 4% interest-rate floor for Special, MediSave and Retirement Account savings until 31 December 2027, providing greater certainty over the minimum interest these savings will earn.
With CPF forming a significant part of many Singaporeans’ retirement savings, it is useful to understand both the headline rates and the extra interest available on eligible balances.
The closure of the Special Account for members aged 55 and above also makes it important to know where our savings are held and what interest they earn.
Let us look at the latest CPF interest rates, how they are calculated and what they mean for our retirement planning.
What are the CPF interest rates in 2026?
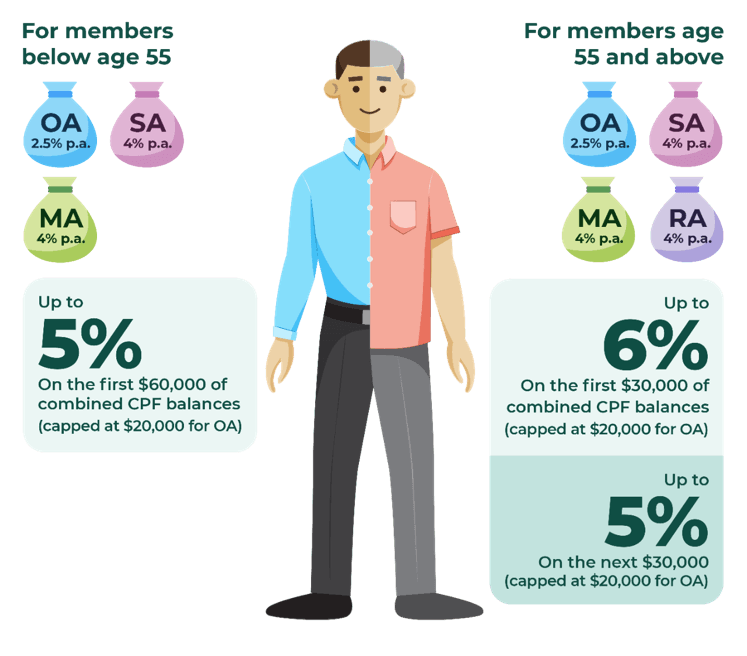
From 1 October to 31 December 2026, the CPF OA interest rate is 2.5% p.a., while the SA, MA and RA interest rates are 4% p.a.
Eligible balances can earn extra interest, depending on your age and combined CPF savings.
| CPF account | Base interest rate, October–December 2026 | Potential extra interest on eligible balances |
| Ordinary Account (OA) | 2.5% p.a. | Up to 1 percentage point below 55; up to 2 percentage points from age 55 |
| Special Account (SA), for members below 55 | 4% p.a. | Up to 1 percentage point |
| MediSave Account (MA) | 4% p.a. | Up to 1 percentage point below 55; up to 2 percentage points from age 55 |
| Retirement Account (RA), from age 55 | 4% p.a. | Up to 2 percentage points |
| Source: CPF Board | ||
Extra interest is subject to combined-balance limits, with no more than S$20,000 from OA counted.
This means that “up to 6% interest” does not apply to your entire CPF balance. We explain the limits and illustrate how they work below.
What are the different CPF accounts?
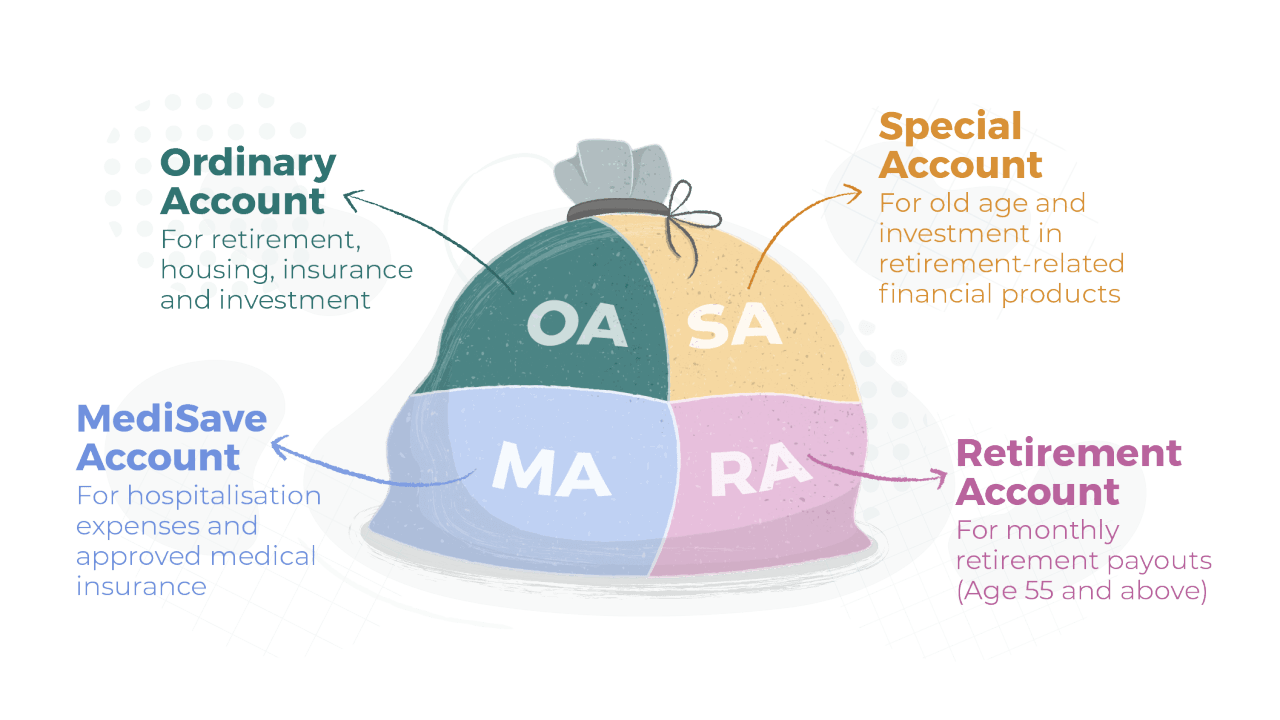
Each CPF account serves a different purpose, which helps explain why the interest rates and rules for using the savings differ.
| CPF account | What are the savings used for? |
| Ordinary Account (OA) | Housing, education, approved insurance and investments, as well as retirement |
| Special Account (SA) | Retirement savings and approved retirement-related investments for members below 55 |
| MediSave Account (MA) | Approved healthcare expenses and medical insurance premiums |
| Retirement Account (RA) | Retirement payouts, including through CPF LIFE, for members aged 55 and above |
Before age 55, members generally have an OA, SA and MA.
When you turn 55, your RA is created and your SA closes. Savings from SA, followed by OA, go towards your RA up to your applicable Full Retirement Sum. Any remaining SA savings move to OA.
You can read our CPF retirement sum guide to understand how much is set aside for retirement.
What is the CPF OA interest rate?
The CPF OA interest rate is 2.5% p.a. for October to December 2026.
OA savings can support housing, education and other approved uses, as well as retirement.
The base rate is reviewed quarterly and is subject to a legislated minimum of 2.5% p.a.
Why is CPF OA still paying 2.5%?
The OA benchmark uses the three-month average of specified deposit rates at DBS, OCBC and UOB.
The calculation gives an 80% weighting to 12-month fixed deposit rates and a 20% weighting to savings deposit rates.
For October to December 2026, the relevant average bank interest rate from May to July 2026 was 0.32%.
As this was below the legislated minimum of 2.5%, OA savings continue to earn 2.5% p.a.
This also explains why higher advertised bank promotions do not automatically translate into a higher CPF OA interest rate. The CPF formula uses specified deposit rates, rather than whichever promotional rate is highest.
The HDB concessionary loan rate is pegged at 0.1 percentage point above the OA interest rate. It therefore remains at 2.6% p.a. for the same quarter.
What is the CPF SA interest rate?
The CPF SA interest rate is 4% p.a. for October to December 2026.
The Special Account holds retirement savings for members below 55.
When a member turns 55, the SA closes and savings are transferred to the Retirement Account, up to the applicable Full Retirement Sum. Remaining SA savings move to OA.
For members below 55 considering an OA-to-SA transfer, the higher interest rate comes with a trade-off.
The transfer is irreversible, and the transferred savings will no longer be available for housing. Eligibility and transfer limits also apply.
What is the CPF MediSave interest rate?
The CPF MediSave Account interest rate is 4% p.a. for October to December 2026.
MediSave savings support approved healthcare expenses and insurance premiums.
Its interest rate follows the same benchmark as SA and RA.
Eligible MA balances can also receive extra interest, depending on your age and combined CPF balances.
What is the CPF Retirement Account interest rate?
The CPF RA interest rate is 4% p.a. for October to December 2026.
Your Retirement Account is created when you turn 55 to set aside savings for retirement payouts.
Since January 2024, its interest-rate benchmark has been aligned with SA and MA, with rates reviewed quarterly.
The Government has extended the 4% interest-rate floor for SA, MA and RA until 31 December 2027.
This provides a minimum interest rate for that period. These accounts can still earn more if their market-based benchmark rises above the floor.
How are CPF interest rates determined?
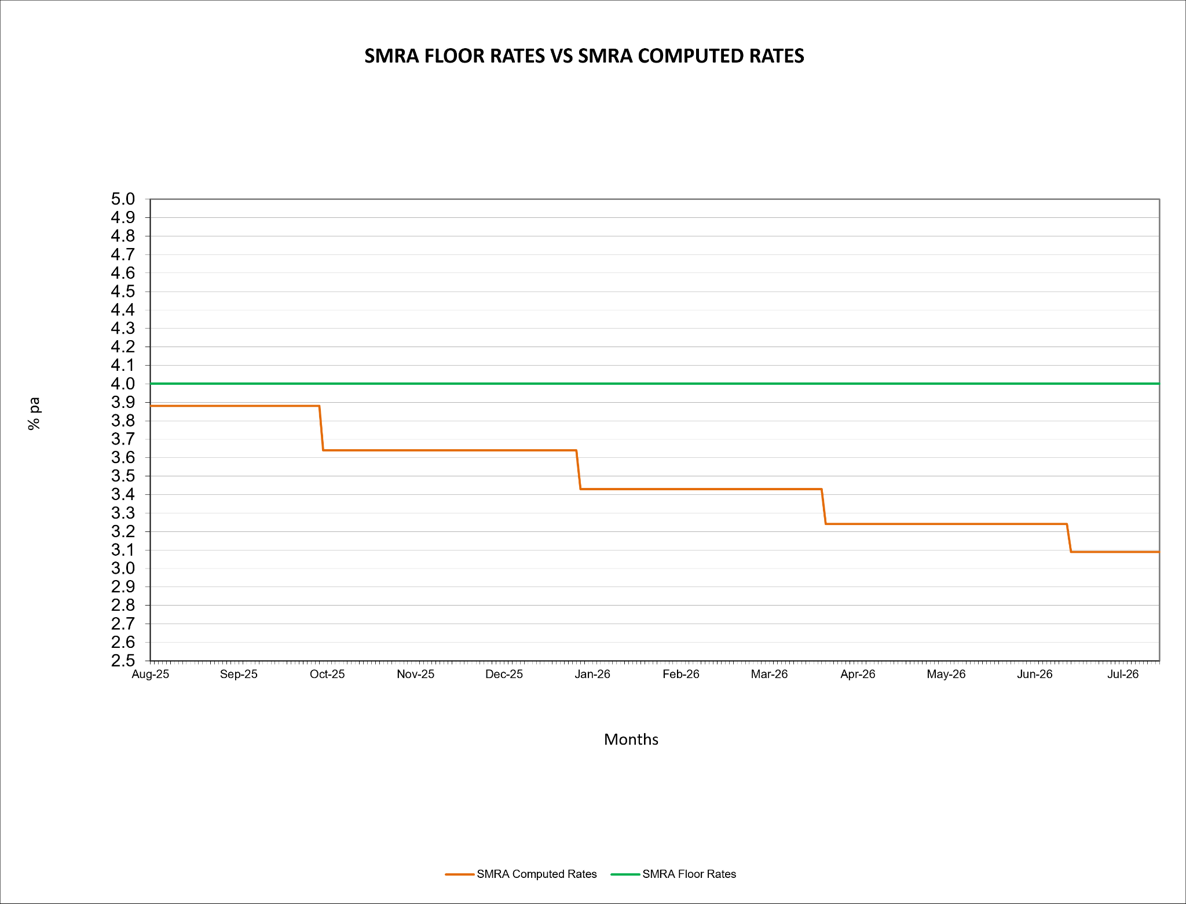
CPF compares each account’s market-based benchmark with its applicable floor and pays the higher rate.
| Account | Benchmark, reviewed quarterly | Interest-rate floor | October–December 2026 base rate |
| OA | Three-month average of specified major local bank deposit rates | Legislated minimum of 2.5% p.a. | 2.5% p.a. |
| SA, MA and RA | Twelve-month average yield of 10-year Singapore Government Securities, plus 1 percentage point | 4% p.a., extended through December 2027 | 4% p.a. |
| Source: CPF Board’s benchmark calculations | |||
For SA, MA and RA, the average 10-year Singapore Government Securities yield from August 2025 to July 2026 was 2.06%.
Adding 1 percentage point gives a calculated rate of 3.06%.
As this is below the 4% floor, members receive 4% p.a. on these savings.
How much extra CPF interest can I earn?
The Government pays extra interest on eligible CPF balances to help members build their retirement savings.
The amount depends on your age and combined balances. The limits apply across your accounts, rather than separately to each account.
| Age | Extra interest per year | OA limit |
| Below 55 | 1% on the first S$60,000 of combined balances | Up to S$20,000 of OA savings counts |
| 55 and above | 2% on the first S$30,000, then 1% on the next S$30,000 | Up to S$20,000 of OA savings counts |
| Source: CPF Board’s extra-interest rules | ||
CPF counts balances in the following order:
- RA, including any CPF LIFE premium balance.
- OA, capped at S$20,000.
- SA.
- MA.
Extra interest earned on OA savings goes into SA if you are below 55, or RA if you are 55 and above.
How do I earn 6% CPF interest?
The 6% rate comes from a 4% base rate plus 2% extra interest on eligible balances for members aged 55 and above.
For illustration, suppose a member aged 55 or above has S$100,000 in RA throughout a full year, has not joined CPF LIFE, and the current rates remain unchanged.
| Portion of RA savings | Rate including extra interest | Illustrative annual interest |
| First S$30,000 | 6% | S$1,800 |
| Next S$30,000 | 5% | S$1,500 |
| Remaining S$40,000 | 4% | S$1,600 |
| Total | 4.9% across S$100,000 | S$4,900 |
The member earns 6% on the first S$30,000, while the overall interest earned on S$100,000 is 4.9% in this illustration.
Actual interest depends on eligible monthly balances and prevailing rates.
What CPF interest do I earn after age 55?
At age 55, your RA is created and your SA closes.
Savings go towards RA up to your applicable Full Retirement Sum, using SA savings first and then OA savings. Remaining SA savings move to OA.
For members already aged 55 and above, the SA closure took place on 19 January 2025.
Under current rates:
- Savings in RA earn 4% p.a., before extra interest.
- Savings in OA earn 2.5% p.a., before extra interest.
- Savings in MA earn 4% p.a., before extra interest.
This means that savings moved from SA to OA do not retain the SA base interest rate.
You can consider transferring OA savings to RA up to the prevailing Enhanced Retirement Sum to support higher retirement payouts.
However, this transfer is irreversible and reduces the savings available for other uses.
Our guide to the CPF SA closure explains what happens to your savings and the options to consider after the transfer.
You can also read our CPF retirement sum guide to understand the Basic, Full and Enhanced Retirement Sums.
How is CPF interest calculated and credited?
CPF interest is calculated monthly and compounded annually, with the annual interest credited by the following year.
The timing of transactions affects the amount earned:
- Contributions and refunds received in a month start earning interest in the following month.
- Amounts withdrawn or deducted stop earning interest from the month of withdrawal or deduction.
As a simple illustration, S$10,000 eligible for OA base interest for one full month at 2.5% p.a. earns approximately:
S$10,000 × 2.5% ÷ 12 = S$20.83
This excludes any extra interest.
Your actual total depends on each month’s eligible balance, account transactions and applicable rates.
Multiplying your year-end balance by the headline rate may therefore give the wrong result.
Frequently asked questions about CPF interest rates
Can CPF interest rates rise above 2.5% and 4%?
Yes. These are floors, rather than fixed maximums.
Rates can rise when their respective benchmarks exceed the floors. For example, SA, MA and RA paid 4.14% p.a. in October to December 2024.
The benchmarks use averages, so a short-term rise in market rates does not immediately produce a higher CPF interest rate.
Does every CPF account earn up to 6%?
No. The maximum depends on your age, the account’s base rate and your eligible balance.
At current rates, OA’s 2.5% base rate cannot become 6% through extra interest.
The combined-balance caps also mean you cannot claim the maximum extra interest separately on every account.
What happens to my SA interest after 55?
SA closes at 55.
Savings transferred to RA earn the prevailing RA interest rate, while savings transferred to OA earn the prevailing OA interest rate.
Extra-interest rules continue to apply to eligible balances.
Does CPF LIFE still earn interest?
Yes. CPF LIFE earns the same interest rate as RA savings, and interest is incorporated into monthly payouts.
Interest on CPF LIFE premiums is pooled to support lifelong payouts. It should not be treated as a separate annual cash payment to you.
Members participating in CPF LIFE remain eligible for extra interest on combined balances, including savings used for CPF LIFE, subject to the applicable limits.
Read our CPF LIFE guide for more on how lifelong payouts work and what to consider when choosing a plan.
What would Beansprout do?
CPF interest can help our retirement savings grow over time, but I would look beyond the headline rate when deciding how to use my savings.
I would first check how my CPF savings are split between accounts, how much qualifies for extra interest, and what I may need for housing and retirement.
For savings I am eligible to invest from OA, the prevailing 2.5% interest rate provides a starting point for comparison.
I would assess potential investment returns after fees, alongside the possibility of losses and how long I can leave the money invested.
Our CPF Investment Scheme guide explains the eligibility rules and considerations before investing CPF savings.
For transfers to SA or RA, I would weigh the higher interest against the irreversible commitment to retirement savings, especially if I may still need the money for housing.
Ultimately, I would use CPF as a foundation for retirement planning, starting with the retirement sum I am working towards and the monthly income CPF LIFE could provide. I would then consider how to fund any remaining gap in my retirement expenses.
For savings outside CPF, the Four Pots of Wealth framework can help me plan how to fund any remaining gap. Money needed for near-term expenses can remain in the Liquidity Pot, investments intended to provide additional income can form part of the Income Pot, and funds not needed for many years can be considered for the Growth Pot.
Are you leaving your CPF savings to earn interest, making top-ups or considering investing a portion for retirement? Share your thoughts with the Beansprout Telegram community.
Follow Beansprout on Telegram, Youtube, Facebook and Instagram, and add Beansprout as your preferred source on Google so you never miss an update.
Read also
Gain financial insights in minutes
Subscribe to our free weekly newsletter for more insights to grow your wealth
Most Popular

Comments
0 comments