
DBS Multiplier Account: Interest rates up to 4.10% p.a. (September 2026)
Savings, Savings Account
By Beansprout • 08 Sep 2026
Why trust Beansprout? We’ve been awarded Best Investment Website at the SIAS Investors’ Choice Awards 2025

Make Beansprout your preferred source on Google
Add us on Google to see more of our insights in your search results
DBS Multiplier Account offers up to 4.10% p.a. Learn how the interest rates work, qualifying criteria, latest promotions and key pros and cons.
What happened?
Choosing a savings account is partly about finding one that fits how we already bank.
If you are setting aside money for emergencies or upcoming expenses, you may want to earn more interest without having to spend more each month.
The DBS Multiplier Account allows you to qualify for bonus interest through income crediting and everyday transactions, without a separate minimum spending requirement.
The changes introduced in August 2023 made DBS Multiplier easier to qualify for, lowering the minimum total monthly transaction amount to S$500 and allowing more types of income and spending to count towards bonus interest.
However, while it offers up to 4.10% p.a., the interest you earn depends on your eligible transactions and savings balance.
We take a look at how DBS Multiplier works, its advantages and disadvantages, and how it compares with other savings accounts in Singapore.
How does DBS Multiplier work?
DBS Multiplier is a personal multi-currency deposit account that rewards you with higher interest on your SGD savings when you transact with DBS/POSB.
To qualify through the standard route, you need to credit recognised income and transact in at least one additional category, with total eligible transactions adding up to S$500 or more each month.
Recognised income includes qualifying salary, dividends, CPF payouts and SRS withdrawals.
You can earn higher bonus interest when you transact across more qualifying categories with DBS/POSB.
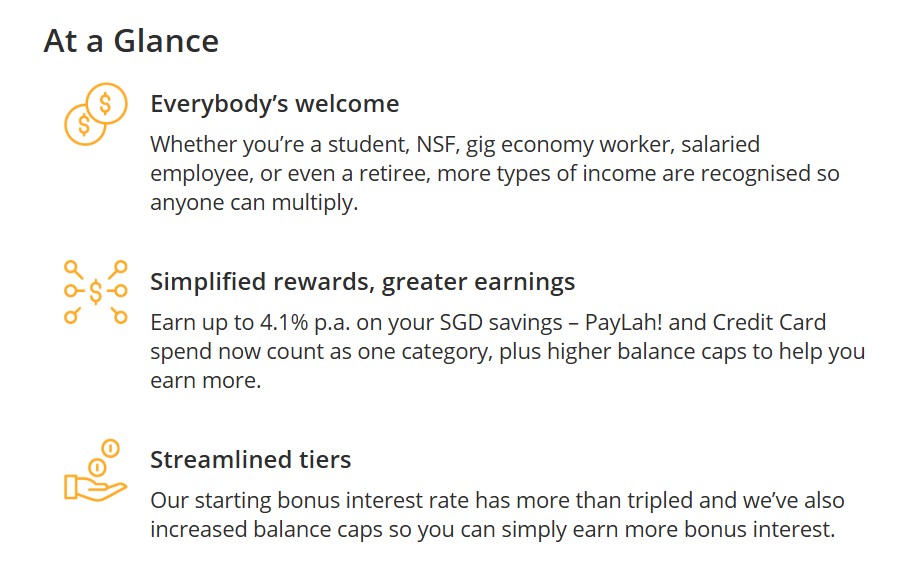
These product categories would include:
| Category | Examples of transactions that count |
|---|---|
| Credit card or PayLah! retail spending | Eligible DBS/POSB credit card purchases or PayLah! retail payments |
| Home loan | Qualifying DBS/POSB residential mortgage instalments |
| Insurance | Eligible insurance purchased through DBS/POSB |
| Investments | Eligible investment transactions through DBS/POSB |

Credit card and PayLah! spending count together as one category, even if you use both.
Likewise, salary and dividends are combined under income. They do not count as separate categories.
For example, if you credit a qualifying salary of S$3,500 and make S$100 of eligible PayLah! purchases, your total eligible transactions would be S$3,600.
You would fulfil income plus one category, qualifying for 1.80% p.a. on your first S$50,000 under the current schedule.
The S$500 requirement refers to your total eligible transactions, including income. It does not mean you need to spend S$500 every month.
What are the current DBS Multiplier interest rates?
The interest rate you earn depends on the value of your eligible monthly transactions and the number of categories you fulfil alongside income.
Generally, a higher value of eligible transactions and more qualifying categories allow you to earn a higher interest rate.

For example, if you credit your income, fulfil one category and have total eligible monthly transactions of at least S$500 but below S$15,000, you will earn 1.80% p.a. on the first S$50,000.
If you credit your income, fulfil two categories and have total eligible monthly transactions of at least S$500 but below S$15,000, you will earn 2.10% p.a. on the first S$100,000.
If you transact across two categories and your total eligible transactions reach S$30,000 or more, you can earn 3.00% p.a. on the first S$100,000.
If you credit recognised income, fulfil three or more categories and have S$30,000 or more in eligible monthly transactions, you can earn the highest rate of 4.10% p.a. on the first S$100,000.
However, do take note that the higher rate applies only up to the balance cap for your category combination.
With income plus one category, the cap is S$50,000. With income plus two or more categories, it increases to S$100,000.
Balances above the applicable cap earn the prevailing base rate.
What are the advantage of DBS Multiplier?
#1 - No separate minimum spending requirement
One advantage of DBS Multiplier is that there is no separate minimum card spending requirement to fulfil the spending category.
Even a small amount of eligible DBS/POSB credit card or PayLah! retail spending can count.
Your recognised income and other eligible transactions can make up the minimum total eligible transaction amount of S$500.
For example, someone earning a qualifying salary of S$3,500 could spend S$100 through PayLah! and still meet the S$500 total transaction requirement.
This may be useful if you do not regularly spend enough to meet the S$500 or higher monthly card-spending requirements of some other savings accounts.
However, PayLah! transfers to friends do not count as retail spending. Eligible merchant payments and other qualifying transactions are required.
#2 - A qualifying home loan can help fulfil another category
If you already have a DBS/POSB home loan, its monthly instalment may count as another category alongside spending.
Qualifying instalments include payments made with CPF, cash or both.
For joint home loans, the first three joint borrowers can each have the full monthly instalment recognised as an eligible transaction for their individual Multiplier Accounts.
For example, a qualifying salary of S$4,000, eligible spending of S$100 and a qualifying mortgage instalment of S$2,000 would add up to S$6,100 in eligible monthly transactions.
This would fulfil income plus two categories and qualify for 2.10% p.a. on the first S$100,000.
For someone who already has these transactions, the higher interest rate would come without needing an additional insurance or investment purchase.
#3 - More ways to qualify under the Income category
The DBS Multiplier Account has also become easier to qualify for because more types of income are now recognised.
Salary crediting is no longer limited to GIRO. Your salary can be credited via GIRO, FAST or PayNow, as long as it carries the recognised transaction code or description.
You can also qualify through dividends credited via GIRO, FAST or PayNow.
For retirees or those drawing down their retirement savings, CPF payouts and SRS withdrawals can also count towards the Income category.
This makes the DBS Multiplier Account more accessible even if you do not receive a conventional salary through GIRO.
What are the disadvantage of DBS Multiplier?
#1 - Salary and spending alone do not earn the maximum rate
To earn the highest rate, you need to fulfil at least three additional categories alongside income and reach the highest transaction tier.
If your banking activity consists mainly of salary crediting and everyday spending, a lower rate would apply.
For example, income plus spending with total eligible transactions below S$15,000 but at least S$500 earns 1.80% p.a. on the first S$50,000.
To move into the higher interest tiers, you would need to transact across more categories, such as a DBS home loan, insurance or investments.
This is likely to be the more relevant rate to compare if you do not have other qualifying transactions.
For those without a DBS/POSB home loan, meeting the additional categories may therefore mean taking up qualifying insurance or investment products.
Some of these products are also only recognised for a limited period. For example, eligible insurance premiums are recognised for 12 consecutive months, while new DBS Invest-Saver investments are also recognised for the first 12 consecutive months per fund.
There may also be minimum amounts for certain investment products. For example, eligible digiPortfolio lump-sum investments require at least S$1,000, while recurring monthly investments can qualify from S$100.
While DBS has made these categories easier to meet, I would still avoid taking up an insurance or investment product purely to earn a higher savings account interest rate.
#2 - You need to meet two categories to earn bonus interest on the first S$100,000
The amount of savings that earns bonus interest depends on how many transaction categories you meet.
If you credit your income and transact in just one category, the bonus interest rate applies only to the first S$50,000 in your DBS Multiplier Account.
To increase the balance cap to S$100,000, you need to transact in at least two categories.
For example, someone who credits their salary and only spends on a DBS credit card or PayLah! would earn bonus interest on the first S$50,000.
This means that if you have more than S$50,000 in savings, you would need to meet another category, such as a home loan, insurance or investments, for more of your balance to earn bonus interest.
Any balance above the applicable cap earns only the prevailing base interest rate.
Can I earn DBS Multiplier bonus interest without crediting a salary?
If you are 29 years and below, you can still earn an interest rate of 1.50% per annum on your first S$50,000 with any credit card or PayLah! Retail spend.
Example #1 - University student who does not credit her salary
Using the example of Andrea, who is a 21 years old full time student who spends S$100 through PayLah.
This means that Andrea is able to earn an interest rate of 1.50% per annum on her first S$50,000 of deposits. When she credits her income through internship of $500 or more a month, she would be able to earn a higher interest rate of 1.80% per annum.

Example #2 - Retiree with no salary
Using the example of Philip, a retiree who receives his CPF LIFE monthly payouts through DBS and transacts using DBS PayLah!, he is still able to earn an interest rate of 1.80% per annum on his first S$50,000 in the DBS Multiplier account.

How does DBS Multiplier compare with UOB One, OCBC 360 and other savings accounts?
With savings-account rates and criteria changing across banks, it is worth comparing DBS Multiplier with other popular savings accounts such as UOB One and OCBC 360.
The account that gives you the highest effective interest rate can differ depending on how much you save and which requirements you can already meet.
Let's start with a fairly common scenario where you mainly credit your salary and use your account for everyday spending.
Scenario 1: Salary + spending
For this comparison, we assume that you:
- meet the salary-crediting requirement for each account
- spend at least S$500 on an eligible card where required
- increase your OCBC 360 average daily balance by at least S$500 each month
- do not purchase insurance or investment products from any of the banks
For DBS Multiplier, we assume total eligible transactions are at least S$500 but below S$15,000 per month.
Based on these criteria, we compare the effective interest rate across different savings balances.
| Account monthly average balance | DBS Multiplier | UOB One | OCBC 360 |
|---|---|---|---|
| S$50,000 | 1.80% | 1.00% | 1.80% |
| S$75,000 | 1.22% | 1.00% | 1.80% |
| S$100,000 | 0.925% | 1.375% | 2.20% |
| S$150,000 | 0.63% | 1.90% | 1.48% |
| Source: Various bank websites as of 8 September 2026 | |||
DBS Multiplier and OCBC 360 offer the same rate of 1.80% p.a. at S$50,000 under these assumptions, but DBS Multiplier does not require S$500 of spending or monthly balance growth. OCBC 360 offers more at S$100,000, while UOB One leads at S$150,000.
The comparison changes if you already have a qualifying DBS/POSB home loan.
Scenario 2: Salary + spending + DBS/POSB home loan
Let's now consider someone who already has a qualifying DBS/POSB home loan.
For this scenario, we keep the UOB One and OCBC 360 assumptions unchanged, but assume the DBS Multiplier customer also has a qualifying DBS/POSB home loan.
For DBS Multiplier, we assume your total eligible transactions, including income, spending and home loan instalments, are still at least S$500 but below S$15,000 per month.
Under this scenario, you would meet two DBS Multiplier transaction categories, spending and home loan, allowing you to earn 2.10% p.a. on the first S$100,000.
| Account monthly average balance | DBS Multiplier | UOB One | OCBC 360 |
|---|---|---|---|
| S$50,000 | 2.10% | 1.00% | 1.80% |
| S$75,000 | 2.10% | 1.00% | 1.80% |
| S$100,000 | 2.10% | 1.375% | 2.20% |
| S$150,000 | 1.42% | 1.90% | 1.48% |
| Source: Various bank websites as of 8 September 2026 | |||
In this scenario, DBS Multiplier offers the highest effective interest rate for balances of S$50,000 and S$75,000.
At S$100,000, OCBC 360 remains slightly higher at 2.20% p.a., although it requires you to increase your account balance by at least S$500 each month and spend at least S$500 on an eligible OCBC credit card.
Under these assumptions, having a qualifying DBS/POSB home loan makes DBS Multiplier more competitive, as the instalment gives you another qualifying category without requiring an insurance or investment purchase.
However, the advantage becomes smaller once your balance exceeds S$100,000, as the DBS Multiplier bonus interest is capped at the first S$100,000 when you meet two or more categories.
To see how DBS Multiplier compares with other options, check out our guide to the best savings accounts in Singapore based on different balances and banking habits.
What are the latest DBS Multiplier promotions?
DBS is currently running a salary‑crediting promotion that allows customers to earn extra cash rewards on top of the standard Multiplier account interest rates.
DBS salary-crediting promotion: Get up to S$300
The promotion is only open to those who did not have a salary‑crediting arrangement linked to a POSB/DBS account in 2025.
To qualify for the main S$250 cash reward, you need to register for the promotion and credit:
- at least S$1,600 of salary per month, or
- at least S$500 of NS allowance per month
This must be credited via GIRO SAL/PAY for four consecutive months, with your first qualifying salary or NS allowance credited by 31 October 2026.
There are also ways to boost your rewards further.
You can earn another S$40 by setting up a qualifying GIRO arrangement for income or property tax payments and having at least one successful deduction. You can also earn another S$10 by opening an SRS account and contributing at least S$10.
This brings the potential cash reward to S$300.
However, the rewards are limited to the first 12,000 qualified customers.
You can read the full promotion details here.
DBS yuu Card sign-up promotion
On top of the salary‑crediting promotion, DBS is offering a separate campaign for new DBS yuu Card applicants.
If you apply for a DBS yuu Card by 31 October 2026, you can choose between:
- Samsonite MINTER 80/30 Trunk Luggage (Worth S$680), using the promo code MINTER, or
- S$288 cashback, using the promo code CASH288.
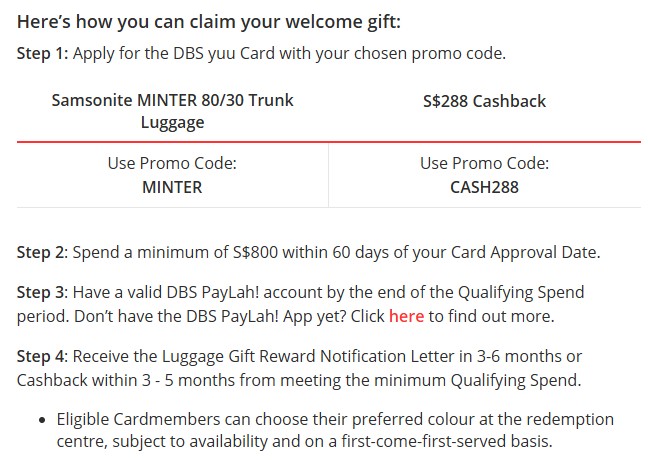
This offer is for new to DBS/POSB credit card customers, meaning those who do not currently hold any principal DBS/POSB credit card and have not cancelled one in the past 12 months.
To receive the welcome gift, you need to spend at least S$800 within 60 days of your card approval date and have a valid DBS PayLah! account by the end of the qualifying spend period.
Beyond the sign-up rewards, the DBS yuu Card offers up to 18% cash rebates at participating merchants such as Cold Storage, Giant, foodpanda, Gojek and SimplyGo.
However, to earn the full 18% cash rebates, you need to spend at least S$800 in eligible card spend and transact at four different participating merchants each calendar month.
You can find the promotion details and full terms and conditions here.
DBS Multiplier minimum balance and fees
There is no initial deposit required to open a DBS Multiplier Account.
However, a S$5 monthly service charge applies if your average daily balance falls below S$3,000, unless you qualify for a waiver.
| Requirement | Details |
|---|---|
| Minimum age | 18 |
| Initial deposit | None required |
| Average daily balance to avoid the service charge | S$3,000 |
| Service charge below the required balance | S$5 per month |
| Age-based service-charge waiver | Customers aged 29 and below |
For a smaller savings balance, the service charge can outweigh the interest earned.
For example, S$2,000 earning 1.80% p.a. would generate approximately S$36 a year. If the S$5 monthly charge applied throughout the year, it would cost S$60.
It is therefore worth checking the waiver if you are starting with a smaller amount.
You can read the full terms and conditions here.
How to open a DBS Multiplier Account
You can apply through the DBS digibank app.
Existing customers can select More → Deposit Account → DBS Multiplier Account.
New customers can follow the application process using Singpass and provide any required supporting information.
After opening the account, you can check the Bank & Earn summary in digibank to see your eligible transactions and the rate you qualify for.
Allow for processing and settlement time, particularly for transactions made near month-end.
Base interest is credited at month-end, while bonus interest is credited by the seventh working day of the following month.
What would Beansprout do?
For me, the DBS Multiplier Account is more compelling if I already use DBS/POSB for several of my everyday banking needs.
If I credit my income and use a DBS/POSB credit card or PayLah!, I can earn 1.80% p.a. on the first S$50,000 at the lowest eligible transaction tier, without having to meet a separate minimum card-spending requirement.
If I also already have a DBS/POSB home loan, I can fulfil another category and earn bonus interest on up to the first S$100,000, without needing to take up an additional insurance or investment product.
That makes DBS Multiplier relatively straightforward for someone who is already within the DBS ecosystem.
However, if I only credit my salary and spend with DBS, the rate I can realistically earn is quite different from the headline 4.10% p.a. rate.
And if I do not already have a DBS/POSB home loan, insurance or investments, I would not take up these products purely to unlock a higher savings account interest rate.
For money in my Liquidity Pot, what matters most to me is keeping my cash accessible while still earning interest.
I would therefore compare the rate I can realistically earn with DBS Multiplier against other savings accounts in Singapore, based on my savings balance and the banking requirements I can already meet, rather than comparing headline rates alone.
I would also compare it with alternatives such as fixed deposits, T-bills and Singapore Savings Bonds, depending on when I expect to need the money and how much flexibility I want.
Would you consider using the DBS Multiplier Account for your savings, or do you prefer another savings account? Share your thoughts in the comments below or join the discussion in our Telegram group.
Follow Beansprout on YouTube, Facebook and Instagram, and add Beansprout as your preferred source on Google so you never miss an update.

Find out which savings account allows you to earn the highest interest rate on your savings.
Read also
Gain financial insights in minutes
Subscribe to our free weekly newsletter for more insights to grow your wealth
Most Popular

Questions and Answers
3 questions
- Thomas Chua • 29 Nov 2025 08:29 AM
- Terry • 12 Jul 2025 05:06 AM
- gen • 07 Nov 2024 03:49 AM
- JD • 05 Dec 2024 09:03 AM