
Best savings accounts in Singapore with high interest rates [November 2026]
Savings
By Gerald Wong, CFA • 04 Nov 2026
Why trust Beansprout? We’ve been awarded Best Investment Website at the SIAS Investors’ Choice Awards

Make Beansprout your preferred source on Google
Add us on Google to see more of our insights in your search results
Compare the best savings accounts in Singapore for November 2026, with rates of up to 7.35% p.a. depending on your cash balance and banking habits.
What happened?
Several savings accounts are offering higher interest rates in November 2026.
UOB Stash and Maybank raised its interest rates, while OCBC 360, HSBC EGA, Trust Bank and CIMB FastSaver have introduced new promotional offers.
What caught my attention is that some promotions let me earn more without moving my salary or meeting monthly card-spend requirements.
At the same time, some high-yield savings accounts continue to offer a maximum effective interest rate of up to 7.35% p.a., subject to conditions such as salary crediting, card spend, or investment and insurance purchases.
If my money has been sitting in the same account for a while, it could be worth checking whether it can earn more elsewhere.
But I would first check which requirements I can consistently meet, and whether bonus interest applies to my entire balance or only to qualifying fresh funds.
In this guide, I compare the best savings accounts in Singapore in November 2026, outline the requirements to qualify for higher interest, and help you decide which account may work better for your situation.
[Exclusive Beansprout Promotion] Get 8.8% p.a. interest boost coupon for 90 days on S$10,000 (worth S$217) with Longbridge Cash Plus when you sign up for a Longbridge account via Beansprout. Plus get S$80 Fairprice voucher within 5 working days. Learn more about the Longbridge promotion here.
The best savings accounts in Singapore
The best savings account in Singapore depends on how much cash you have and which requirements you can realistically meet.
Some accounts offer higher rates if you can credit your salary and spend on a linked credit card, while others may be more useful if you prefer fewer conditions.
Here is a quick summary of the savings accounts that may stand out for different situations, based on information available as of 12 November 2026.
| Scenario | Account to consider | Realistic interest rate (p.a.) |
| S$75,000 savings, salary credit, card spend, and investment and insurance purchase | Standard Chartered BonusSaver |
|
| S$100,000 in qualifying fresh funds, with salary credit and card spend | CIMB FastSaver Account | Up to 2.49% p.a.* |
| S$100,000, with salary credit, card spend and monthly savings growth | OCBC 360 | Up to 2.20% p.a. |
| S$100,000 in qualifying fresh funds, without salary credit or card spend | Up to 2.20%, subject to different promotion conditions** | |
| S$150,000 qualifying fresh funds, without salary credit or card spend | Up to 2.20%, subject to different promotion conditions** | |
| S$150,000 savings, salary credit and card spend | UOB One | Up to 1.90% p.a. |
| Smaller savings amount with no salary credit, fresh funds or card spend | GXS Savings Account Boost Pocket | Up to 2.00% p.a. for an 18-month Boost Pocket |
Source: Official bank websites and Beansprout calculations as of 12 November 2026. Rates are annualised and exclude separate cash rewards. Promotional rates apply only for the relevant promotion period. *CIMB: Personal Banking rates assume the full balance qualifies for November's fresh-funds promotion. The salary-and-spend scenarios require at least S$1,000 monthly salary credit or an eligible standing instruction, plus S$800 monthly eligible CIMB Visa Signature card spend. The promotion excludes certain October participants. **Maybank: 2.20% promotion runs until 31 January 2027, with incremental balances measured against October. | ||
Best high-yield savings accounts in Singapore by maximum effective interest rate
A higher advertised effective interest rate may not always mean that an account is the best savings account for you.
Many of the highest headline rates require salary crediting, credit card spend, or the purchase of investment and insurance products.
To make the comparison clearer, I started by comparing the maximum effective interest rate offered by some of the most popular savings accounts in Singapore.
| Savings Account | Maximum Effective Interest Rate (p.a.) |
| HSBC Everyday Global Account (fresh funds and Rewards+) | 8.10% |
| Standard Chartered Bonus Saver (New-to-BonusSaver Invest) | 7.35% |
| OCBC 360 | 4.70% |
| Bank of China SmartSaver | 4.60% |
| DBS Multiplier | 4.10% |
| CIMB FastSaver (Personal banking) | 3.20% |
| MariBank Savings Account (New user, salary credit and ShopeeVIP, first 30 days) | 3.08% |
| CIMB StarSaver (Personal banking) | 2.60% |
| Trust Bank | 2.40% |
| Maybank iSAVvy (incremental ADB) | 2.20% |
| GXS (Boost Pockets*) | Up to 2.00% |
| UOB Stash | 1.92% |
| UOB One | 1.90% |
| OCBC Statement Savings Account | 1.91% |
| Standard Chartered eSaver (fresh funds) | 1.80% |
| SingFinance GoSaver | 1.60% |
| Standard Chartered JumpStart | 1.50% |
| Singapura Finance Vivid Savings Account | 1.28% |
| Hong Leong Finance Premium SAVER Account | 1.20% |
| MariBank (Existing user, salary credit and ShopeeVIP) | 1.48% |
Source: Official bank websites and Beansprout calculations as of 12 November 2026. Rates assume the relevant balance and qualifying requirements are met. Promotional rates apply only during their respective promotion periods. Separate cash rewards and cashback are excluded. *CIMB StarSaver’s approximately 2.60% EIR assumes S$1 million of fully qualifying incremental fresh funds. | |
How we come up with the list of best savings accounts in Singapore
Does a higher advertised effective interest rate mean it is the best savings account in Singapore?
It depends.
The effective interest rate is the total annual interest earned as a percentage of your average balance in the savings account over the year.
We suggest looking at the effective interest rate rather than the headline interest rate, as a bank may offer an interest rate of “up to 6.0% p.a.”, but this rate may only apply to a specific deposit tier.
For example, the highest rate could apply only to balances above S$50,000, or only after you meet several qualifying conditions.
Hence, the best savings account would depend on whether you are able to fulfil these criteria, and how much cash you plan to keep in the account.
Featured high-yield savings accounts in Singapore
OCBC 360
Why we like it:
The OCBC 360 Account is useful if you want to earn bonus interest through regular banking habits, rather than relying only on short-term promotions.
It may work best if you already use OCBC as your main salary-crediting account and can consistently build your savings each month.
However, the highest headline rate requires additional invest and insure categories, so I would focus first on the more practical salary, save and spend criteria.
As OCBC’s flagship savings account, the OCBC 360 Account lets you earn higher interest on your deposits when you carry out everyday banking activities such as crediting your salary, saving, and spending.
From 1 August to 31 December 2026, you can earn up to 2.20% p.a. on the first S$100,000 when you credit your salary, save, and spend.
Those who also insure and invest with OCBC can boost their rate to a maximum 4.70% p.a., though these categories require purchasing eligible financial products.
| Categories met | Current Max EIR from 1 August 2026 |
| Salary + Save | 1.95% p.a. |
| Salary + Save + Spend | 2.20% p.a. |
| Salary + Save + Spend + Insure / Invest | 3.45% p.a. |
| Salary + Save + Spend + Insure + Invest | 4.70% p.a. |
Learn more about the OCBC 360 Account here.
Maybank iSAVvy Savings Account
Why we like it:
The Maybank iSAVvy Savings Account stands out for savers with larger fresh-funds balances who prefer not to credit their salary or meet monthly card-spend requirements.
Its current promotion offers 2.20% p.a. on qualifying fresh funds until 31 January 2027. For someone placing S$150,000 that fully qualifies, this is higher than UOB One’s 1.90% p.a., without the salary and card-spend requirements.
To qualify, I need to increase my average daily balance by at least S$20,000 compared with October 2026, using eligible fresh funds.
For accounts opened during November 2026, the October reference balance is treated as zero.
However, the promotional bonus applies only to the incremental average daily balance. If I already held money in the account during October, I should not assume my entire balance will earn 2.20% p.a.
| Qualifying incremental average daily balance | Base interest rate (p.a.) | Bonus interest rate (p.a.) | Combined rate (p.a.)* |
|---|---|---|---|
| S$20,000 to below S$200,000 | 0.20% | 2.00% | 2.20% |
| S$200,000 and above | 0.80% | 1.40% | 2.20% |
| Source: Maybank’s published promotion rates as of 2 November 2026. The combined rate assumes the full account balance qualifies as incremental fresh funds. Base interest applies to the account balance, while bonus interest applies only to the qualifying incremental average daily balance. | |||
I would also keep the 31 January 2027 expiry in mind and review the available rates afterwards, as the promotional rate is not guaranteed to continue.
Learn more about the Maybank iSAVvy Savings Account and its promotion requirements here.
HSBC Everyday Global Account (EGA)
Why we like it:
HSBC Everyday Global Account now offers two ways to earn additional interest.
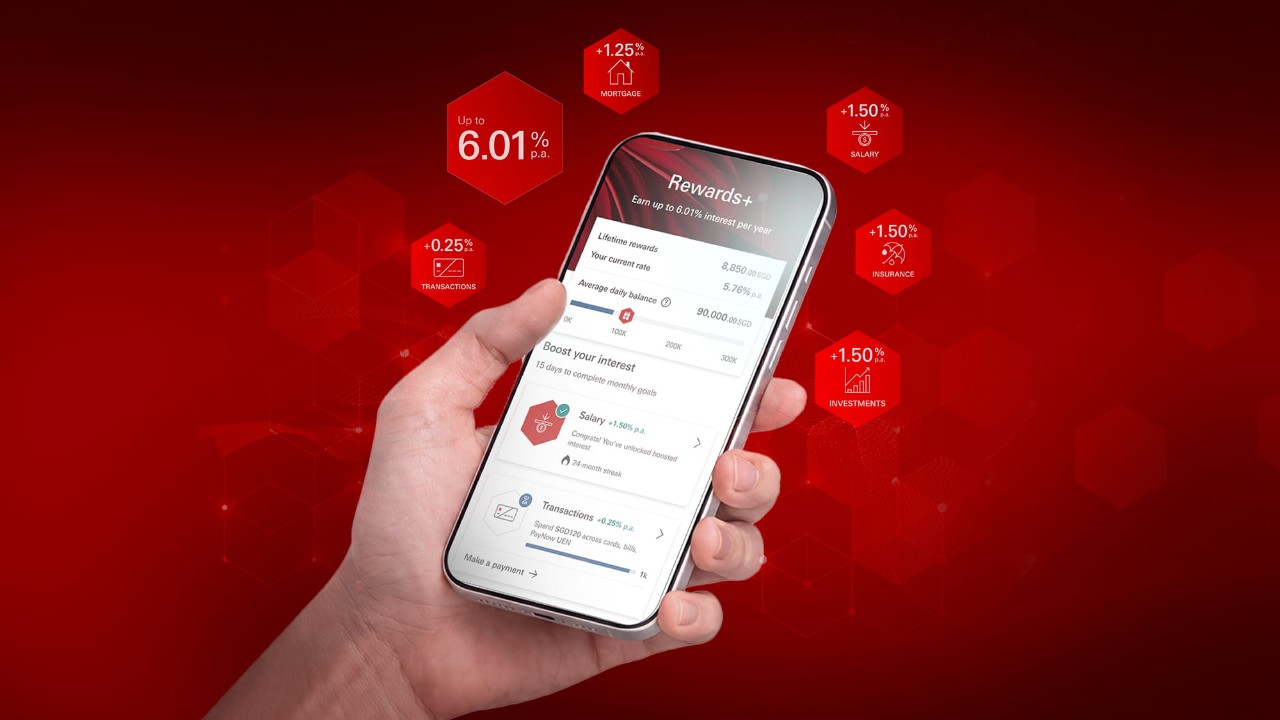
Its November fresh-funds promotion offers up to 2.10% p.a., while Rewards+ Programme offers up to 6.01% p.a. on the first S$100,000 when you meet all five banking and wealth categories.
What stands out is that eligible customers can combine both offers.
Its HSBC Rewards+ Programme offers up to 6.01% p.a. on the first S$100,000:
| Rewards+ category | Qualifying requirement | Additional interest |
|---|---|---|
| Salary | Credit at least S$5,000 monthly via GIRO with narrative “SALA” | 1.50% p.a. |
| Transactions | Make at least S$1,000 in eligible monthly card spending, bill payments or PayNow UEN payments | 0.25% p.a. |
| Investments | Purchase at least S$50,000 of eligible investments in a calendar month | 1.50% p.a. |
| Insurance | Buy an eligible policy with at least S$12,000 annualised regular premium or S$50,000 single premium | 1.50% p.a. |
| Mortgage | Take out a qualifying new HSBC home loan of at least S$500,000 | 1.25% p.a. |
| Prevailing interest | SGD account balance | 0.01% p.a. |
| Maximum total | Meet all five categories | 6.01% p.a. |
For those who prefer not to credit their salary or meet transaction requirements, November’s fresh-funds promotion remains an option:
| Qualifying incremental average daily balance | Wealth customers or non-wealth customers meeting the balance-maintenance condition | Other non-wealth customers |
|---|---|---|
| Below S$500,000 | 2.00% p.a. | 1.80% p.a. |
| S$500,000 to S$5 million | 2.10% p.a. | 1.90% p.a. |
| Source: HSBC’s published November 2026 promotion rates, checked on 12 November 2026. Rates include prevailing interest. | ||
To qualify for November’s offer, your EGA must have been opened on or before 31 July 2026, and you must register by 30 November 2026. Promotional bonus interest applies to qualifying fresh funds that increase your average daily balance above October 2026’s level.
Non-wealth customers can earn the higher promotional rate by keeping their qualifying incremental average daily balance in both December 2026 and January 2027 at least as high as November’s.
However, customers participating in an overlapping EGA deposit promotion, including September’s or October's offer, are excluded. Bonus interest is paid by 31 March 2027, and the account must remain open and in good standing until then.
Learn more about HSBC EGA and its promotion requirements here.
Standard Chartered Bonus Saver
Why we like it:
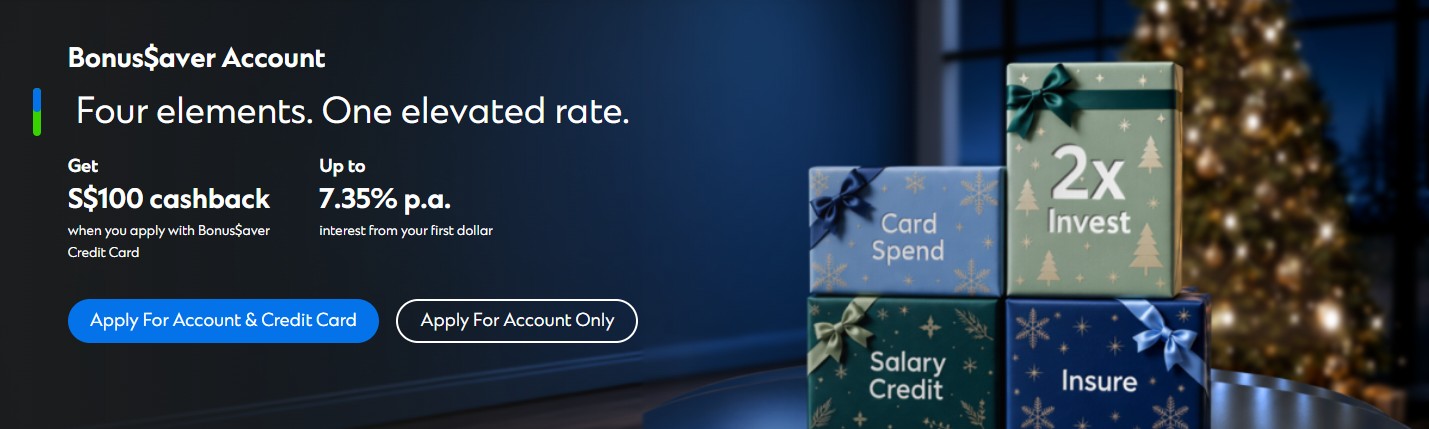
Standard Chartered Bonus$aver stands out for its high headline rate.
It offers a regular maximum rate of 5.85% p.a. on the first S$100,000, rising to 7.35% p.a. for three months for eligible new customers under its Sign-Up Invest Interest Promotion.
However, reaching the promotional maximum requires you to meet the salary, card-spending, investment and insurance requirements, alongside the sign-up promotion conditions.
For those who credit at least S$3,000 in monthly salary and spend at least S$1,000 on eligible Bonus$aver card transactions, the rate remains 1.85% p.a., including prevailing interest.
The same qualifying rate applies across your first S$100,000 of SGD average daily balance, making your potential returns relatively straightforward to calculate.
| Bonus interest component | Current Max EIR from 1 May 2026 |
|---|---|
| Card spend (minimum eligible spend of S$1,000 monthly) | 0.90% p.a. |
| Salary credit (regular inward credit through GIRO, PayNow or FAST) | 0.90% p.a. |
| Invest (invest in eligible Unit Trust or Online Equities of at least S$30,000; bonus interest paid for a consecutive period of 6 months) | 1.50% p.a. |
| Insure (bonus interest paid for a consecutive period of 6 months) | 2.50% p.a. |
| Prevailing interest rate | 0.05% p.a. |
| Total interest on your first S$100,000 eligible deposit balance | 5.85% p.a. |
| Additional Sign-Up Invest Interest: For eligible new customers, paid for three consecutive months | 1.50% p.a. |
| Promotional maximum interest rate for three months | 7.35% p.a |
From 16 October 2026 to 1 February 2027, eligible new-to-Bonus$aver customers can qualify for the additional investment bonus by investing at least S$30,000 in an eligible unit trust in a single subscription, or making at least S$30,000 in cumulative eligible online-equity purchases within a calendar month through SC Online Trading.
The qualifying investment must be made by the end of the month after account opening and maintained for the full three-month promotional holding period.
There is also a S$100 cashback sign-up offer for eligible applicants who successfully apply for both a Bonus$aver Account and a Bonus$aver World Mastercard Credit Card during the promotion period. They must deposit at least S$50,000 in fresh funds by the end of the following month and maintain it until the end of the second month after account opening. The cashback is credited to the credit card account.
Learn more about Standard Chartered Bonus Saver here.
GXS Savings Account
Why we like it:
The GXS Savings Account stands out for savers who want straightforward interest without salary crediting or monthly card-spend requirements.
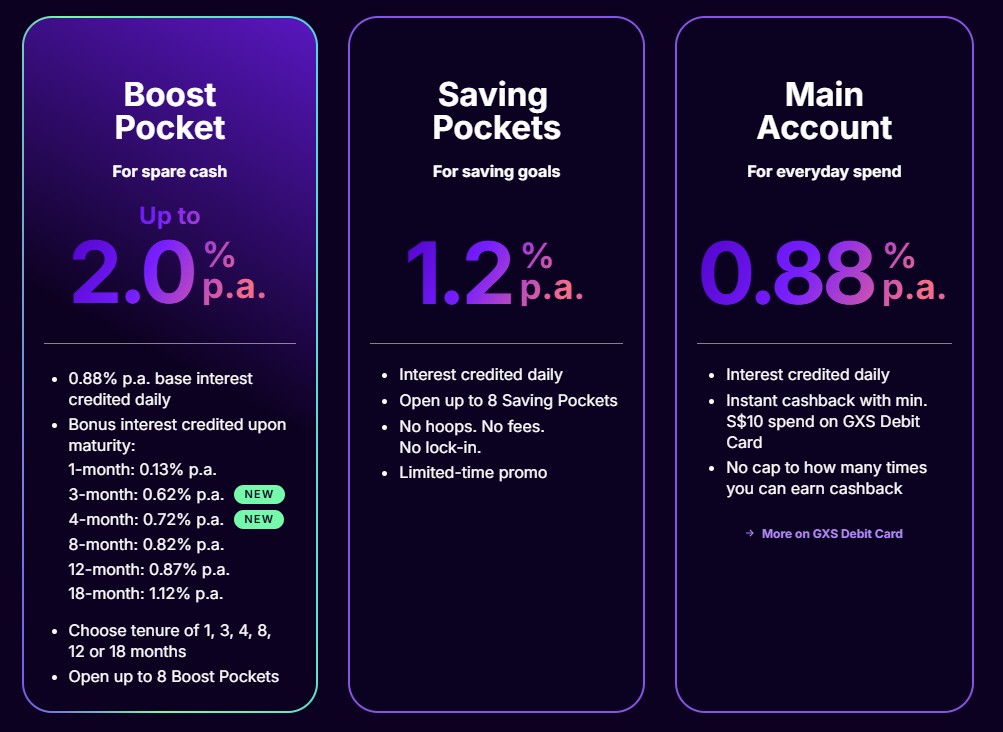
Its Saving Pockets offer a promotional 1.20% p.a., with interest credited daily and no minimum balance requirement. I can also withdraw my money anytime, making this an option for cash I may need at short notice.
For money I can set aside for longer, Boost Pockets offer up to 2.00% p.a., depending on the tenure.
The Boost Pocket rate consists of 0.88% p.a. base interest credited daily, plus bonus interest paid at maturity.
| Boost Pocket tenure | Interest rate (p.a.) |
|---|---|
| 1 month | 1.01% |
| 3 months | 1.50% |
| 4 months | 1.60% |
| 8 months | 1.70% |
| 12 months | 1.75% |
| 18 months | 2.00% |
I can start a Boost Pocket with S$100 and open up to eight Boost Pockets.
What stands out to me is the simplicity. I do not need to credit my salary or meet a minimum monthly card spend to earn these rates.
Learn more about GXS Savings Account here
CIMB FastSaver Account
Why we like it:
The CIMB FastSaver Account has become one of the more competitive options this month if you have fresh funds and can meet the salary or card spend requirements.
It may work best for savers who have spare cash outside CIMB, and are comfortable crediting salary or setting up a standing instruction of at least S$1,000 a month.
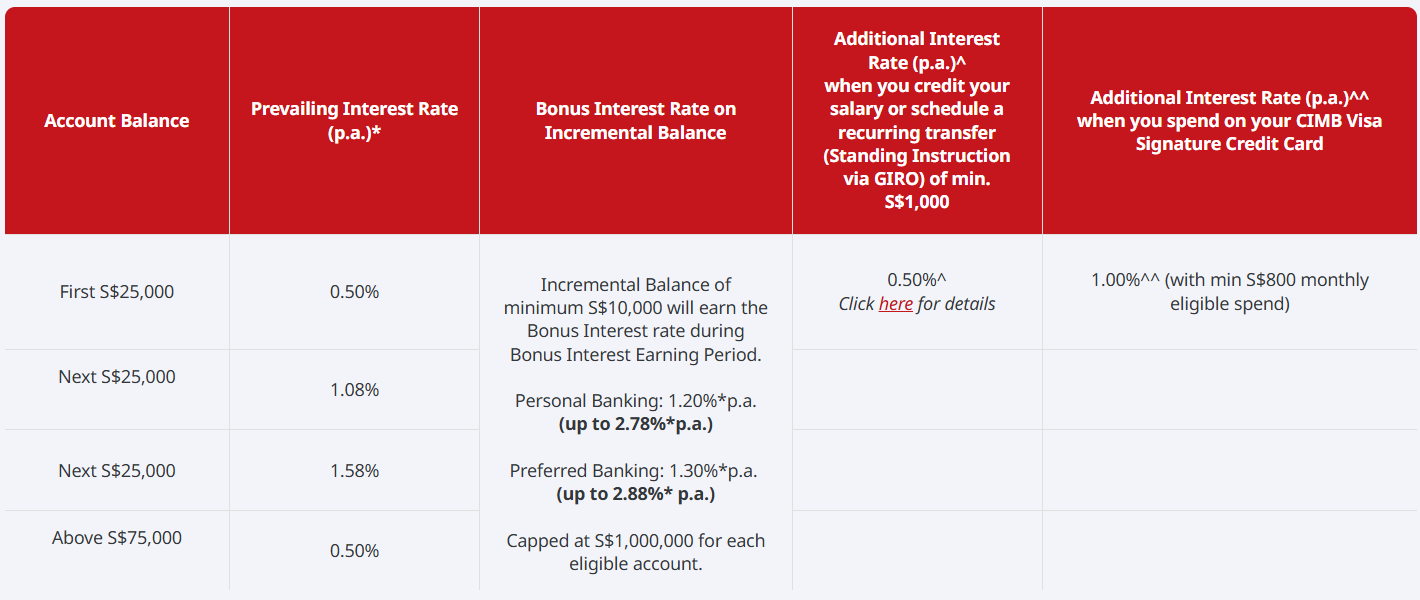
For Personal Banking customers, the November promotion offers 1.20% p.a. bonus interest on qualifying incremental fresh funds, on top of the account’s tiered base interest. On S$75,000 of fully qualifying fresh funds, this works out to approximately 2.25% p.a.
I can earn more by crediting my salary or setting up an eligible standing instruction via GIRO of at least S$1,000 monthly, and spending at least S$800 monthly on the CIMB Visa Signature credit card.
Meeting all these requirements brings the interest rate to 3.20% p.a. on S$25,000, or an effective interest rate of approximately 2.49% p.a. on S$100,000.
However, the promotional rate needs to be understood carefully.
The fresh funds bonus applies only to eligible incremental balances compared with your 31 October 2026 balance, while the salary or standing instruction and card spend bonuses apply only on the first S$25,000.
Here is how the effective interest rate (EIR) works out at different balances for Personal Banking customers:
| Balance | Fresh funds only | Fresh funds + salary/transfer | Fresh funds + salary/transfer + credit card spend |
|---|---|---|---|
| S$25,000 | 1.70% | 2.20% | 3.20% |
| S$50,000 | 1.99% | 2.24% | 2.74% |
| S$75,000 | 2.25% | 2.42% | 2.75% |
| S$100,000 | 2.12% | 2.24% | 2.49% |
| Source: Beansprout calculations based on CIMB rates as of 2 November 2026. Rates are annualised and rounded to two decimal places. Assumes the full balance qualifies as incremental fresh funds and the applicable transaction requirements are met. | |||
Learn more about the CIMB FastSaver Account here.
Best savings account for S$100k of savings, salary credit, and credit card spend
CIMB FastSaver stands out in November if my full S$100,000 qualifies as incremental fresh funds and I meet its salary or standing instruction and card-spend requirements.
For Personal Banking customers, the effective interest rate works out to approximately 2.49% p.a., with at least S$1,000 monthly salary credit or an eligible standing instruction, plus S$800 monthly eligible CIMB Visa Signature card spend.
OCBC 360 remains competitive at 2.20% p.a. if I credit at least S$1,800 in salary, increase my average daily balance by at least S$500 each month, and spend at least S$500 monthly on an eligible OCBC credit card.
If you are an existing HSBC EGA customers, you may earn up to 3.75% p.a. if you are able to meet both its Reward+ criteria and HSBC EGA November 2026 fresh funds promotion.
If I prefer not to move my salary or meet card-spend requirements, Maybank iSAVvy offers 2.20% p.a. on qualifying fresh funds.
Standard Chartered Bonus$aver comes next at about 1.85% p.a. if I credit at least S$3,000 of salary and spend at least S$1,000 monthly on an eligible Bonus$aver card.
| Savings Account | Realistic interest rate (p.a.) |
| HSBC Everyday Global Account (fresh funds and Rewards+) | 3.75% |
| CIMB FastSaver (Personal banking) | 2.49% |
| OCBC 360 | 2.20% |
| Maybank iSAVvy (fresh funds) | 2.20% |
| Trust Bank (fresh funds, Level Up promotion) | 2.20% |
| HSBC Everyday Global Account (fresh funds) | 2.00% |
| UOB Stash | 1.92% |
| Standard Chartered Bonus Saver | 1.85% |
| OCBC Statement Savings Account | 1.91% |
| CIMB StarSaver (Personal banking) | 1.70% |
| SingFinance GoSavers | 1.60% |
| Bank of China Smart Saver | 1.60% |
| Standard Chartered eSaver (fresh funds) | 1.50% |
| UOB One | 1.375% |
| Singapura Finance Vivid Savings Account | 1.28% |
| Hong Leong Finance Premium SAVER Account | 1.20% |
| GXS (Saving Pockets) | 1.20% |
| MariBank (existing user with salary credit, excluding ShopeeVIP bonus) | 1.08% |
| DBS Multiplier | 0.93% |
| Standard Chartered JumpStart | 0.30% |
Source: Official bank websites and Beansprout calculations as of 12 November 2026. Rates assume the applicable qualifying requirements are met. Fresh-funds calculations assume the full S$100,000 qualifies as incremental funds. Promotional rates apply only during their respective promotion periods. Separate cash rewards, card cashback and new-user bonuses are excluded. *GXS’s rate applies to eligible Saving Pocket balances. Check the maximum account balance shown in the app before assuming the full S$100,000 can be deposited. **The DBS illustration assumes 1.80% p.a. on the first S$50,000 and 0.05% p.a. on the remaining S$50,000, giving a blended rate of 0.925% p.a. Actual rates depend on eligible transaction amounts and categories. | |
Best savings account for S$100k of savings without salary deposit and credit card spend
For eligible new users, Mari Savings Account offers up to 2.88% p.a. with ShopeeVIP, although the new-user bonus lasts only 30 days.
For a longer promotional period, Maybank iSAVvy offers 2.20% p.a. on S$100,000 of fully qualifying fresh funds from 1 November 2026 to 31 January 2027, without salary credit or card-spend requirements.
To qualify, I need to increase my average daily balance by at least S$20,000 compared with October 2026 using eligible fresh funds. The bonus applies only to this incremental balance, so any money already in the account during October may lower my overall effective rate.
CIMB FastSaver is another option, offering approximately 2.12% p.a. on S$100,000 of fully qualifying incremental fresh funds for Personal Banking customers. This is slightly below Maybank iSAVvy’s 2.20% p.a., but above the HSBC Everyday Global Account at up to 2.00% p.a., subject to its promotion eligibility and wealth or balance-maintenance conditions.
If I can set aside at least S$50,000 in qualifying fresh funds for 188 days, OCBC Statement Savings Account offers an annualised effective rate of approximately 1.91% p.a., with the funds earmarked for that period.
Alternatively, GXS Boost Pockets offer up to 2.00% p.a. without salary credit or card spend. However, the highest rate requires holding an 18-month Boost Pocket to maturity to receive the bonus interest, so I would weigh the longer commitment against the rates available elsewhere.
| Savings Account | Realistic interest rate (p.a.) |
| MariBank Savings Account (New user and ShopeeVIP, first 30 days) | 2.88% |
| Maybank iSavvy (fresh funds) | 2.20% |
| Trust Bank (fresh funds, Level Up promotion) | 2.20% |
| CIMB FastSaver (Personal banking) | 2.12% |
| HSBC Everyday Global Account (fresh funds) | 2.00% |
| UOB Stash | 1.92% |
| OCBC Statement Savings Account | 1.91% |
| GXS (Boost Pockets*) | Up to 2.00% |
| CIMB StarSaver (Personal banking) | 1.70% |
| SingFinance GoSavers | 1.60% |
| Standard Chartered eSaver (fresh funds) | 1.50% |
| Singapura Finance Vivid Savings Account | 1.28% |
| Hong Leong Finance Premium SAVER Account | 1.20% |
| GXS Bank (Saving Pockets) | 1.20% |
| MariBank | 0.88% |
| OCBC 360 (Save bonus only, including base interest) | 0.70% |
| Standard Chartered JumpStart | 0.30% |
| Bank of China SmartSaver | 0.10% |
| Standard Chartered Bonus Saver | 0.05% |
| DBS Multiplier | 0.05% |
| UOB One | 0.05% |
Rates are annualised and assume the applicable qualifying conditions are met. Fresh-funds calculations assume the full S$100,000 qualifies as incremental funds. Promotional rates apply only during the relevant promotion period. Separate cash rewards are excluded. *GXS rates apply to eligible Pocket balances. Check the maximum account balance shown in the app before assuming the full S$100,000 can be deposited. The 2.00% Boost Pocket rate includes bonus interest payable at maturity. **OCBC 360’s 0.70% comprises the promotional Save bonus of 0.65% on S$100,000 and 0.05% base interest. It requires an increase in average daily balance of at least S$500 each month. | |
Best savings account for S$75k of savings, salary credit, credit card spend, and investment/insurance products purchase
If I am already planning to buy eligible investment or insurance products from a bank, I may be able to earn a higher interest rate on my savings as well.
The Standard Chartered Bonus Saver will offer you an interest rate of up to 5.85% p.a. on the first S$100,000. Eligible new-to-Bonus$aver customers can earn an additional 1.50% p.a. for three months when they meet the qualifying investment requirements, which brings it to the maximum effective interest rate of 7.35% p.a. It still offers the highest headline rate among the major savings accounts in this comparison, although it comes with higher qualifying hurdles.
For HSBC Everyday Global Account, I can earn about 5.85% p.a. on S$75,000 if I meet the both the respective Rewards+ categories and HSBC EGA November 2026 fresh funds promotion
Bank of China SmartSaver follows at 4.60% p.a. on the first S$100,000 if I meet its wealth, salary, card spend and payment requirements.
| Savings Account | Realistic interest rate (p.a.) |
| Standard Chartered Bonus Saver (New-to-BonusSaver Invest) | 7.35% |
| HSBC Everyday Global Account (fresh funds and Rewards+) | 6.75% |
| Standard Chartered Bonus Saver | 5.85% |
| Bank of China SmartSaver | 4.60% |
| OCBC 360 | 3.80% |
| CIMB FastSaver | 2.75% |
| DBS Multiplier | 2.40% |
| Maybank iSAVvy (incremental ADB) | 2.20% |
| Trust Bank (fresh funds, Level Up promotion) | 2.00% |
| OCBC Statement Savings Account | 1.91% |
| Standard Chartered eSaver (fresh funds) | 1.80% |
| CIMB StarSaver | 1.70% |
| SingFinance GoSavers | 1.60% |
| UOB Stash | 1.57% |
| Mari Savings Account (existing user, salary credit and ShopeeVIP) | 1.48% |
| Singapura Finance Vivid Savings Account | 1.28% |
| Hong Leong Finance Premium SAVER Account | 1.20% |
| GXS Bank* (Saving Pockets) | 1.20% |
| Standard Chartered JumpStart | 1.03% |
| UOB One | 1.00% |
| MariBank | 0.88% |
Source: Official bank websites and Beansprout calculations as of 12 November 2026. Rates assume the relevant qualifying requirements are met. Fresh-funds calculations assume the full S$75,000 qualifies as incremental funds. Promotional rates and investment or insurance bonuses apply only for their stated periods. Separate cash rewards and new-user bonuses are excluded. *DBS Multiplier’s 2.40% is an illustrative rate for income crediting and three eligible transaction categories at the applicable transaction tier. Actual rates depend on transaction amounts and categories. | |
What would Beansprout do?
I use savings accounts as one way to keep the cash I need for emergencies and upcoming expenses accessible within my Liquidity Pot.
With different banks offering different rates and qualifying criteria, I would not simply chase the highest headline rate. Instead, I would look at how much cash I have and which requirements I can realistically meet.
If I have S$100,000 of fresh funds and prefer no salary or card-spend requirements, Maybank iSAVvy offers 2.20% p.a., ahead of CIMB FastSaver at approximately 2.12% p.a. for Personal Banking customers. These rates assume my entire balance qualifies as incremental fresh funds.
If I can meet the salary and card-spend requirements, CIMB FastSaver offers approximately 2.49% p.a. on S$100,000, or 3.20% p.a. on S$25,000. This requires at least S$1,000 in qualifying monthly salary credit or an eligible GIRO standing instruction, plus S$800 monthly eligible spend on the CIMB Visa Signature card. I would also check the November eligibility rules, particularly if I participated in October’s promotion.
If I have S$150,000 of fresh funds and prefer no salary or card-spend requirements, I would compare Maybank iSAVvy and Trust bank at 2.20% p.a.
If my savings do not qualify for these fresh-funds promotions, I would compare OCBC 360 at 2.20% p.a. on S$100,000 with UOB One at 1.90% p.a. on S$150,000. Both require qualifying salary credit and card spend, while OCBC 360 also requires me to increase my average daily balance by at least S$500 monthly.
For money I can set aside, I would compare OCBC Statement Savings Account’s approximately 1.91% p.a. over 188 days with GXS’s 2.00% p.a. for an 18-month Boost Pocket. I would keep cash needed for emergencies separate from these longer commitments.
For fewer ongoing requirements, I would consider SingFinance GoSavers at 1.60% p.a. on the first S$100,000.
If I am completely new to MariBank, I would consider opening a Mari Savings Account for cash that I want to keep accessible. Eligible new users can earn up to 2.88% p.a. on the first S$100,000 for the first 30 days. This consists of the prevailing 0.88% p.a. base rate, a 1.60% p.a. new-user bonus and a 0.40% p.a. ShopeeVIP bonus.
If I am a student, NSF or do not have regular income, I would also look at the DBS Multiplier Account if I am 29 years old and below. This is because users in this age group may earn 1.50% p.a. on the first S$50,000 with eligible credit card or PayLah! retail spend, even without income crediting.
If I am already planning to purchase an investment or insurance product with a bank, then I would explore accounts such as Standard Chartered Bonus Saver, HSBC EGA, OCBC 360 Account, or Bank of China SmartSaver. However, I would compare the requirements closely, as the qualifying criteria and interest rates differ across these accounts.
Finally, I would also think about safety and flexibility, not just yield. If scam-risk is a concern, it might be worthwhile considering a "money lock" account which allow you to only access your deposits in person.
Apart from savings accounts, I would also use a mix of fixed deposits, Singapore T-bills and Singapore Savings Bonds and money market funds for my Liquidity Pot within the Beansprout's Four Pot of Wealth.
Compare the latest T-bill, fixed deposit, Singapore Savings Bond (SSB) and savings account rates to find out where you can earn a competitive return on your cash in November 2026.
[Exclusive Beansprout Promotion] Get 8.8% p.a. interest boost coupon for 90 days on S$10,000 (worth S$217) with Longbridge Cash Plus when you sign up for a Longbridge account via Beansprout. Plus get S$80 Fairprice voucher within 5 working days. Learn more about the Longbridge promotion here.
Once you have already set aside enough cash for your safety buffer and upcoming expenses, you may also want to explore how the Four Pots of Wealth framework can help you grow your wealth beyond savings accounts, as well as read our beginner’s guide to start investing in Singapore.
Which savings account are you considering based on your savings amount and the requirements you can meet? Share your circumstances in the comments below or in the Beansprout Telegram community.
Follow Beansprout on Telegram, Youtube, Facebook and Instagram, and add Beansprout as your preferred source on Google so you never miss an update.
Read also
Gain financial insights in minutes
Subscribe to our free weekly newsletter for more insights to grow your wealth
Most Popular

Comments
4 comments
- Kelvin Tan • 02 Jul 2026 12:40 AM
%20--%3e%3csvg%20version='1.1'%20id='Layer_1'%20xmlns='http://www.w3.org/2000/svg'%20xmlns:xlink='http://www.w3.org/1999/xlink'%20x='0px'%20y='0px'%20viewBox='0%200%20160.45%20160.45'%20style='enable-background:new%200%200%20160.45%20160.45;'%20xml:space='preserve'%3e%3cstyle%20type='text/css'%3e%20.st0{fill:%2300DBA4;}%20%3c/style%3e%3cg%3e%3cg%3e%3cpath%20class='st0'%20d='M80.23,0C35.99,0,0,35.99,0,80.23s35.99,80.23,80.23,80.23c44.24,0,80.23-35.99,80.23-80.23S124.46,0,80.23,0%20z%20M80.23,149.37c-1.73,0-3.45-0.09-5.15-0.21l0-38.76c-1.44-31.08,14.86-34.75,32.13-38.65c5.66-1.28,11.08-2.5,15.76-4.7%20c1.78,15.32-1.66,28.48-9.68,37.18c-0.11,0.11-10.83,10.24-23.27,10.24c-1.12,0-2.26-0.08-3.4-0.26l-1.72,10.94%20c1.73,0.27,3.44,0.4,5.11,0.4c16.97,0,30.39-12.77,31.2-13.57c11.35-12.3,15.63-30.42,12.07-51.01l-2.17-12.46l-10.42,7.15%20c-3.7,2.54-9.63,3.87-15.93,5.29c-16.97,3.82-42.62,9.6-40.75,49.71v36.77c-30.32-7.32-52.92-34.67-52.92-67.21%20c0-38.13,31.02-69.15,69.15-69.15c38.13,0,69.15,31.02,69.15,69.15S118.36,149.37,80.23,149.37z'/%3e%3cpath%20class='st0'%20d='M56.13,44.13c-3.86-0.87-7.5-1.69-9.57-3.11l-9.25-6.35l-1.92,11.06c-2.41,13.89,0.52,26.16,8.48,34.77%20c0.37,0.36,7.58,7.23,17.36,8.83c0.43-1.57,0.92-3.09,1.48-4.54c0.85-2.19,1.85-4.26,3-6.21c-7.3,0.3-13.91-5.81-13.92-5.81%20c0,0,0,0,0,0c-4.44-4.81-6.53-11.78-6.09-19.96c2.57,0.91,5.31,1.52,8.01,2.13c8.98,2.02,16.94,3.83,18.8,15.11%20c0.56-0.52,1.13-1.04,1.72-1.53c2.54-2.12,5.24-3.84,8-5.27C77.55,48.96,64.62,46.04,56.13,44.13z'/%3e%3c/g%3e%3c/g%3e%3c/svg%3e) Beansprout • 07 Jul 2026 03:42 AM
- Singa • 12 Apr 2026 10:28 AM
- CIMB • 02 Jul 2025 07:49 AM
- Beansprout • 07 Jul 2026 04:07 AM
- James • 18 Apr 2025 03:28 AM
- Beansprout • 07 Jul 2026 03:45 AM