
UOB One Account review: Earn up to 1.90% p.a. effective interest rate (September 2026)
Savings Account
By Beansprout • 08 Sep 2026
Why trust Beansprout? We’ve been awarded Best Investment Website at the SIAS Investors’ Choice Awards 2025

Make Beansprout your preferred source on Google
Add us on Google to see more of our insights in your search results
Learn about the latest UOB One Account interest rates, requirements and promotions, and see how much you can earn on S$50,000 to S$150,000.
What happened?
The UOB One Account remains one of the simpler high-yield savings accounts to maximise in Singapore.
As of 8 September 2026, I can earn an effective interest rate (EIR) of up to 1.90% p.a. on S$150,000 by spending at least S$500 a month on an eligible UOB card and crediting a salary of at least S$1,600.
UOB advertises interest of up to 3.40% p.a., but this rate only applies to the final S$25,000 within the highest balance tier. My effective interest rate across the full S$150,000 is 1.90% p.a.
If I cannot credit my salary, I can make three GIRO debit transactions each month instead, although the interest I earn will be lower.
Unlike some other high-yield savings accounts, I do not need to buy an insurance or investment product to maximise the UOB One Account.
In this UOB One Account review, I will look at the latest interest rates, how much I can actually earn, the requirements to qualify and how it compares with other savings accounts.
What is the UOB One account?
The UOB One account is the flagship savings account from UOB that allows you to earn bonus interest by meeting a few monthly requirements.
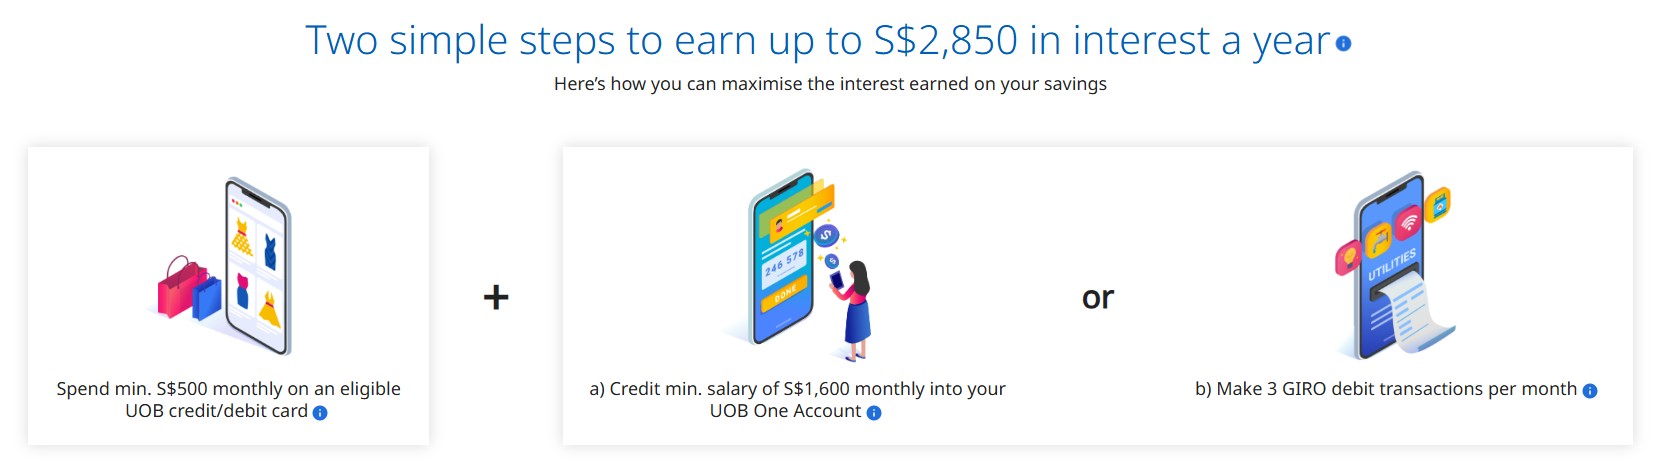
To qualify for bonus interest, all you need to do is:
- Spend at least S$500 each month on eligible UOB credit or debit cards; and
- Either credit your salary of at least S$1,600 through GIRO, PayNow or FAST, or make 3 GIRO debit transactions per month.
Unlike some other high-yield accounts, the UOB One account does not require you to purchase insurance or an investment product to unlock the highest tier.
What is the current UOB One Account interest rate?
The UOB One Account uses a tiered interest-rate structure.
This means the advertised interest rate does not apply to my entire account balance. Different portions of my savings earn different rates.
To understand how the interest rate on the UOB One account works, let us look at the breakdown below.
Total interest p.a. | |||
| Account monthly average balance | Spend min. S$500 (per calendar month) on eligible UOB Card | Spend min. S$500 (per calendar month) on eligible UOB Card AND make 3 GIRO debit transactions | Spend min. S$500 on eligible UOB Card AND credit your salary via GIRO, PayNow or FAST |
| First $75,000 | 0.65% | 1.00% | 1.00% |
| Next $50,000 | 0.05% | 2.00% | 2.50% |
| Next $25,000 | 0.05% | 0.05% | 3.40% |
| Above S$150,000 | 0.05% | 0.05% | 0.05% |
| Source: UOB One account page | |||
We shall start by illustrating the interest rate earned on the UOB One account if you are able to credit your salary of at least S$1,600.
For the first S$75,000 of your monthly average balance, you earn an interest rate of 1.00% p.a. if you are able to spend at least S$500 on an eligible UOB card and credit your salary.
The interest rate earned rises to 2.50% p.a. on your next S$50,000 of monthly average balance, all the way up to 3.40% p.a. on your next S$25,000 monthly average, bringing your total balance to S$150,000.
| Account monthly average balance | Maximum Interest earned when you spend minimum S$500 on eligible UOB card and credit salary of at least S$1,600 |
| First S$75,000 | S$750 |
| S$125,000 | S$2,000 |
| S$150,000 | S$2,850 |
| Source: UOB One account page | |
We can also look at the effective interest rate earned on the UOB One account across various tiers. To calculate the effective interest rate, we can add the total interest received across different tiers.
The effective interest rate shows the overall interest rate earned across my account balance after taking the different interest tiers into account.
You might also be interested to know that UOB now recognises eligible salary credits through GIRO, PayNow or FAST, with the required transaction descriptions such as ‘GIRO-SALA’, ‘PAYNOW SALA’ or ‘FAST SALA’.
| Account balance | Maximum effective interest rate for saver who meet card spend of minimum $500 AND credit salary from 1 December 2025 |
| First S$75,000 | 1.00% |
| S$125,000 | 1.60% |
| S$150,000 | 1.90% |
| Source: UOB One account page | |
What is the interest rate earned on the UOB One account if I am unable to credit my salary?
If you are unable to credit your salary, you can always make 3 GIRO debit transactions in each calendar month to qualify for the bonus interest rate.
If you meet the S$500 card-spend requirement and make three GIRO debit transactions each month, you can earn an EIR of up to 1.40% p.a. on S$125,000.
If you increase your balance to S$150,000, the EIR falls to about 1.18% p.a., as the final S$25,000 earns only 0.05% p.a.
| Account monthly average balance | Interest rate p.a. |
|---|---|
| First S$75,000 | 1.00% |
| Next S$50,000 | 2.00% |
| Next S$25,000 | 0.05% |
| Above S$150,000 | 0.05% |
If you are wondering how to make at least 3 GIRO payments, I have some ideas for you below:
- Credit card bills (Yes! I was also amazed to find out that this method counts – say yay to paying credit card bills on time and no to paying late fees)
- Electricity bills
- Mobile phone bills
- Income tax (apply with IRAS)
Which UOB cards count towards the S$500 spend?
UOB currently lists the UOB One Card, UOB Lady's Cards, UOB EVOL Credit Card and Lazada-UOB Card among the eligible credit cards.
Eligible debit cards include the UOB One Debit Visa Card, UOB One Debit Mastercard, UOB Lady's Debit Card and UOB FX+ Debit Card. You can find the list of eligible cards here.
Eligible local and overseas retail transactions can generally count towards the S$500 requirement, subject to UOB's exclusions. Selected recurring insurance payments may also qualify.
What matters is that the transaction is posted within the relevant calendar month, so I would avoid leaving my S$500 spend until the last day of the month.
How does UOB calculate my account balance and interest?
The UOB One bonus interest is based on my monthly average balance, rather than simply looking at how much is in my account on the last day of the month.
UOB calculates the monthly average balance by adding my day-end account balances for the month and dividing this by the number of calendar days.
The base interest of 0.05% p.a. is calculated based on daily balances, while the bonus interest is calculated at the end of each calendar month based on the monthly average balance.
This means topping up the account only near the end of the month would not give me the same interest as maintaining the same balance throughout the month.
What should I take note of with the UOB One Account?
UOB One does not require you to deposit fresh funds to be eligible for the bonus interest rate. However, there are a few conditions I would take note of.
Also, the interest rate earned on your UOB One account falls to 0.05% per annum for the portion of your monthly average balances above S$150,000.
To maximise your interest earned, you might want to consider the UOB Stash account or another high-yield savings account for balances above S$150,000.
Are there any promotions for the UOB One Account?
Learn more about the UOB Level Up Your Savings Promotion here.
How does UOB One compare with OCBC 360, DBS Multiplier and other savings accounts?
The main advantage of UOB One is its relatively simple structure.
I do not need to grow my account balance every month or purchase an insurance or investment product to achieve its maximum EIR.
However, that does not necessarily mean it pays the highest interest for every account balance.
For example, the OCBC 360 Account currently offers an EIR of up to 2.20% p.a. on S$100,000 when I meet its Salary, Save and Spend requirements during its current Save bonus promotion. At the same S$100,000 balance, UOB One offers an EIR of about 1.38% p.a.
However, UOB One becomes more competitive at higher balances because its bonus interest extends up to S$150,000.
Based on our calculations, UOB One starts to pull ahead of OCBC 360 at around S$131,000 under the current rates and assumptions. You can read our detailed comparison of the UOB One vs OCBC 360 savings accounts.
DBS Multiplier works differently. Its bonus interest depends on my eligible income and transactions across different DBS categories, with bonus rates of up to 4.10% p.a. on eligible balances of up to S$100,000.
To make the comparison more meaningful, I looked at the effective interest rate I could earn at different account balances, assuming I meet the relatively accessible salary, save and card-spend requirements without buying insurance or investment products.
- UOB One: I spend at least S$500 on an eligible UOB card and credit at least S$1,600 of salary each month.
- OCBC 360: I credit at least S$1,800 of salary, increase my average daily balance by at least S$500 monthly and spend at least S$500 on an eligible OCBC card. The calculation includes the limited-time Save bonus available until 31 December 2026.
- DBS Multiplier: I credit eligible income and transact in one eligible category, qualifying for 1.80% p.a. on the first S$50,000 in the comparison scenario.
Here’s how the interest rates compare across different account balances as of 8 September 2026, so you can decide which bank offers the best return for your savings.
| Account balance | UOB One EIR | OCBC 360 EIR | DBS Multiplier EIR | Winner |
|---|---|---|---|---|
| S$75,000 | 1.00% | 1.80% | 1.22% | OCBC 360 |
| S$100,000 | 1.38% | 2.20% | 0.93% | OCBC 360 |
| S$125,000 | 1.60% | 1.77% | 0.75% | OCBC 360 |
| S$150,000 | 1.90% | 1.48% | 0.63% | UOB One |
| S$200,000 | 1.44% | 1.13% | 0.49% | UOB One |
| S$250,000 | 1.16% | 1.39% | 0.40% | OCBC 360 |
| Source: Various bank websites, Beansprout Compare Savings Accounts tool, as of 8 September 2026 | ||||
To help you decide between the UOB One account and the OCBC 360 account, use the calculator below to compare how much interest you would get with the UOB One account and the OCBC 360 with the new interest rates.
What are the eligibility requirements for the UOB One account?
To qualify for the UOB One account, you must fulfill the following requirements.
- You will need to be 18 years and above to open a UOB One account.
- The minimum initial deposit for the UOB One account is S$1,000.
- You will also need to maintain a monthly average balance in your UOB One account of at least S$1,000, or a S$5 fall-below fee will be imposed. This fall-below fee is waived for the first 6 months for accounts opened online.
- A S$30 early account closure fee will be levied if you close your UOB One account within 6 months from opening.
The full terms and conditions can be found here.
How to open a UOB One Account
You can open a savings account online here, get approval within minutes and start transacting instantly.
To apply you will require the following:
- New to UOB customers, existing to UOB customers and joint applicants: Retrieve with Myinfo using Singpass login
- Existing to UOB customers: Personal Internet Banking login details
- Existing to UOB customers applying for single-named account application: Credit/Debit card number and PIN
Learn more about the UOB One Account here.
What would Beansprout do?
I think the UOB One Account remains relatively straightforward if I already use a UOB card and can credit my salary into the account every month.
The main thing I would look at is how much cash I actually have.
If I have S$50,000 to S$75,000, the EIR is only around 1.00% p.a. even after meeting the card-spend and salary requirements. I would compare this against other high-interest savings accounts in Singapore before deciding where to keep my money.
As my balance approaches S$125,000 to S$150,000, UOB One becomes more attractive because the higher interest tiers start to make a bigger difference.
At S$150,000, I can earn up to S$2,850 a year, equivalent to an EIR of 1.90% p.a., without needing to buy an insurance or investment product.
However, I would generally avoid keeping substantially more than S$150,000 in the account purely for interest, since the excess earns only 0.05% p.a.
If I cannot credit my salary, I would also be mindful that the three-GIRO route reaches its highest EIR of 1.40% p.a. at S$125,000, before the marginal interest rate falls sharply for the next S$25,000.
For money in my Liquidity Pot, the UOB One Account offers the advantage of keeping my savings accessible while earning some interest.
To make the excess cash work harder, I could also consider the UOB Stash account or another high-yield savings account for cash above UOB One's S$150,000 bonus-interest cap.
To find out which savings account allows your money to work harder, check out our guide to the best savings accounts with the highest interest rates in Singapore.
I would still compare UOB One's rates and flexibility with other savings accounts, as well as options such as fixed deposits, T-bills and Singapore Savings Bonds, before deciding where to keep my cash.
Follow us on Telegram, Youtube, Facebook and Instagram to get the latest financial insights on savings, investing and retirement planning.
This article contains affiliate links. Beansprout may receive a share of the revenue from your sign-ups to keep our site sustainable. You can view our editorial guidelines here.

Find out which savings account allows you to earn the highest interest rate on your savings.
Read also
Gain financial insights in minutes
Subscribe to our free weekly newsletter for more insights to grow your wealth
Most Popular

Questions and Answers
2 questions
- ling • 02 Dec 2024 08:16 AM
- Carrie • 02 Feb 2024 11:27 PM
