
UOB Stash Account: Interest rate up to 1.92% p.a.(November 2026)
Savings Account
By Beansprout • 04 Nov 2026
Why trust Beansprout? We’ve been awarded Best Investment Website at the SIAS Investors’ Choice Awards
UOB Stash Account offers up to 1.92% p.a. EIR on S$100,000. See its interest rates, minimum balance, fees, promotions and UOB One comparison.

The UOB Stash Account currently offers an effective interest rate of up to 1.92% p.a. for deposits of S$100,000 with very few requirements to earn a higher interest rate.
Unlike typical high-yield savings accounts such as UOB One, OCBC 360, or DBS Multiplier, the UOB Stash Account functions more like a traditional savings account where you don’t need to meet multiple spending or income crediting criteria to earn bonus interest.
This makes the UOB Stash Account relatively straightforward, but there is an important catch: if your monthly average balance falls, you may only earn the 0.05% p.a. base interest for that month.
So, whether you are a student, a retiree or simply looking for a fuss-free account to park your cash, the UOB Stash Account could be worth a closer look.
In this guide, we look at how the UOB Stash Account interest rate works, the key conditions and drawbacks, how it compares with other savings accounts, and the latest promotions available.
What is the UOB Stash Account?
The UOB Stash Account is a savings account that allows you to earn an effective interest rate of up to 1.92% p.a. on your deposits simply when you maintain or increase your balances.
There is no requirement to credit your salary, spend a minimum amount on a credit card, buy an insurance or investment product, or make GIRO transactions to earn the Stash bonus interest.
Interest is paid monthly and there is no lock-in period on the underlying account.
However, the interest you receive depends on both your account balance and whether you meet the monthly average balance requirement.
What is the current interest rate for the UOB Stash Account?
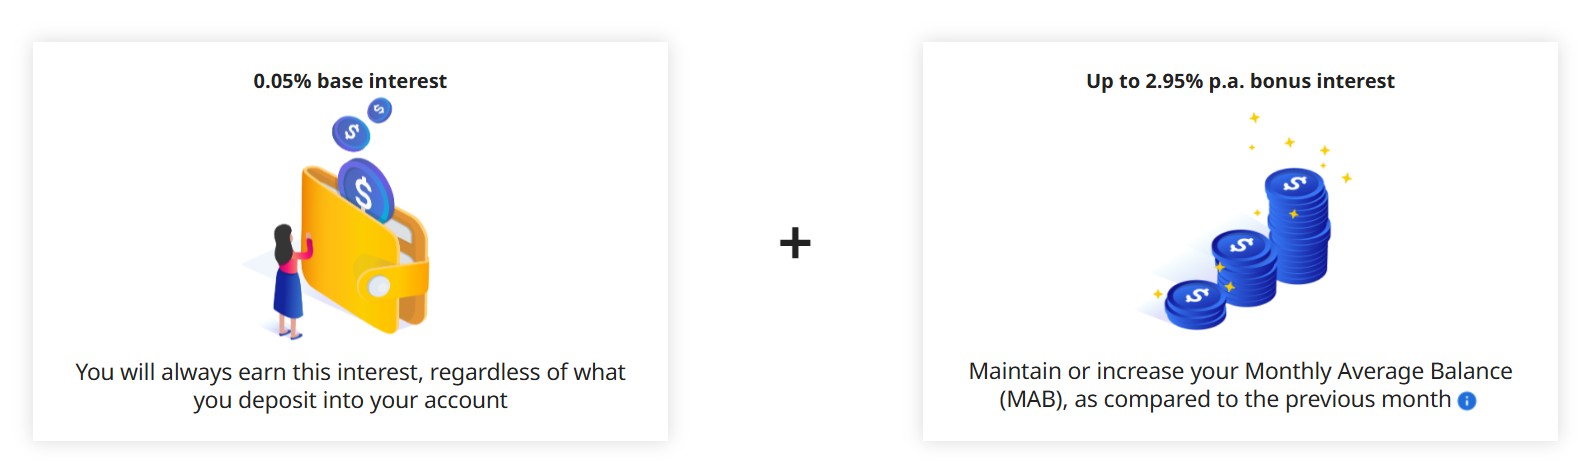
The UOB Stash Account offers a base interest rate of 0.05% p.a., and a bonus interest rate of up to 2.95% p.a.
To qualify for bonus interest, your account's monthly average balance (MAB) must be:
- Above S$10,000 and;
- Maintain or increase the account balance from last month’s balance.
Here is how the interest rate is applied across the different balance tiers:
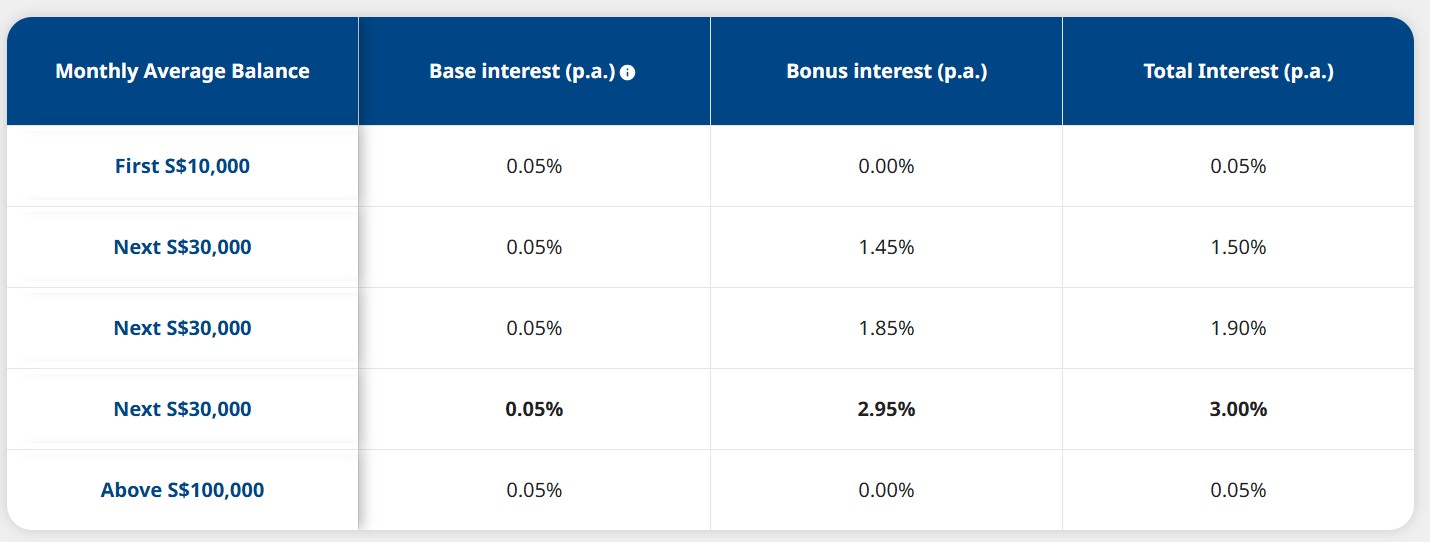
While the highest balance tier earns 3.00% p.a., this does not mean that your entire S$100,000 earns 3.00%.
Because the interest is applied progressively across the different tiers, UOB states that the maximum effective interest rate is 1.92% p.a. on S$100,000
This works out to about S$1,920 in interest over one year if you keep S$100,000 in the account and continue to meet the monthly average balance requirement.
| Monthly average balance | Approx. UOB Stash EIR |
|---|---|
| S$20,000 | 0.78% p.a. |
| S$40,000 | 1.14% p.a. |
| S$60,000 | 1.39% p.a. |
| S$80,000 | 1.66% p.a. |
| S$100,000 | 1.92% p.a. |
| Source: UOB rates as of 3 November 2026. | |
How do I qualify for the UOB Stash bonus interest?
The main requirement is relatively straightforward.
The UOB Stash Account does not require you to fulfill numerous requirements to receive the bonus interest rates.
There’s no need to spend a minimum amount on a credit card, make investment/insurance purchases or credit your salary.
Putting it simply, your monthly average balance (MAB) for the current month must be equal to or higher than your MAB in the previous month.
Monthly average balance is calculated by adding up the end-of-day balance for every day of the month and dividing this by the number of calendar days in that month.
For example, if my MAB was S$50,000 last month and remains at S$50,000 this month, I would still qualify for the bonus interest.
I do not need to increase my account balance every month. Maintaining the same MAB is sufficient.
What happens if my UOB Stash balance falls?
This is the main condition I would pay attention to.
For example, assume my monthly average balance was S$100,000 last month.
If I withdraw some cash and my monthly average balance falls to S$99,500 this month, I would no longer meet the condition for bonus interest.
Instead, I would receive only the 0.05% p.a. base interest for that month.
This means that while there is no lock-in period, withdrawing money can have a meaningful impact on the interest I earn.
However, making a withdrawal does not automatically mean I will miss out on the bonus interest. UOB says I can top up the account again within the same month. If my eventual monthly average balance meets or exceeds the previous month's MAB, I can still qualify for bonus interest.
UOB TMRW and Personal Internet Banking also allow customers to check the amount they need to top up and maintain for the month.
So while UOB Stash does not have salary-crediting or card-spending requirements, maintaining my monthly average balance is itself the key requirement.
Is there any catch to the UOB Stash Account?
The main drawback of the UOB Stash Account would be the need to maintain or increase your account balance from that of the previous month to qualify for the bonus interest.
For example, if your monthly average balance falls to S$99,500 from S$100,000 the month before, the amount of interest you will earn for the month falls to the base interest rate of 0.05%.
Also, the first S$10,000 in the UOB Stash Account earns just a 0.05% interest rate. As your balance goes above S$100,000, it will revert to the base interest rate of only 0.05%.
The flip side of the liquidity offered by a deposit account is that the interest rates are subject to change, and you are not able to ‘lock-in’ the interest rates like for fixed deposits.
UOB Stash Account vs UOB One Account
Another decision is whether I would be better off using the UOB Stash Account or UOB One Account.
Here is how their requirements compare:
| UOB Stash Account | UOB One Account | |
|---|---|---|
| Maximum effective interest rate | 1.92% p.a. | 1.90% p.a. |
| Balance for maximum EIR | S$100,000 | S$150,000 |
| Minimum card spend for maximum EIR | None | S$500 per month |
| Salary credit required for maximum EIR | No | At least S$1,600 per month |
| Main condition | Maintain or increase MAB | Card spend + salary credit |
| Funds accessible | Yes | Yes |
The UOB One Account currently offers a maximum effective interest rate of 1.90% p.a. on S$150,000 when I spend at least S$500 on an eligible UOB card and credit at least S$1,600 of salary each month.
So if I am already able to meet these requirements, I would compare the higher UOB One balance for maximum EIR first.
On the other hand, if I do not want to manage card spending or salary-crediting requirements, UOB Stash has a simpler condition.
The trade-off is that I need to be confident that I can maintain my monthly average balance.
Can I use UOB One and UOB Stash together?
If I have a larger amount of cash, one option is to use both the UOB One Account and UOB Stash Account.
The UOB One Account currently offers a maximum effective interest rate of 1.90% p.a. on S$150,000, provided I meet the relevant card spending and salary crediting requirements.
The UOB Stash Account offers a maximum effective interest rate of 1.92% p.a. on S$100,000 when I maintain or increase my monthly average balance.
If I keep S$150,000 in UOB One and another S$100,000 in UOB Stash, I could earn about S$4,770 in total interest over a year under the current rates, assuming I continue to meet the requirements for both accounts.
Across the combined S$250,000, that works out to an effective interest rate of about 1.91% p.a.
The advantage is that the money in both accounts remains accessible, unlike placing the cash into a fixed deposit for a specified tenure.
However, the two accounts have different conditions. I would need to continue meeting the UOB One spending and salary-crediting requirements, while maintaining or increasing the monthly average balance in UOB Stash to earn its bonus interest.
How does the UOB Stash Account compare to other fuss-free savings accounts?
UOB Stash stands out from savings accounts such as UOB One, OCBC 360 and DBS Multiplier because there is no need to credit a salary or meet a minimum card spend to earn bonus interest.
However, this does not necessarily mean it will offer the highest return for every amount of savings.
The first S$10,000 in UOB Stash earns only 0.05% p.a., while its maximum effective interest rate of 1.92% p.a. is reached at S$100,000.
Its returns are now closer to other simple savings accounts in Singapore.
You can find out how the latest options compare in our guide to the best savings accounts in Singapore
| Account | Key conditions | Max effective interest rate (p.a.) | Deposit limit |
|---|---|---|---|
| UOB Stash Account | Maintain or increase monthly average balance | 1.92% | Up to S$100,000 |
| GXS Boost Pocket | 18-month Boost Pocket; bonus interest credited upon maturity | 2.00% | Up to S$95,000 across Boost Pockets |
| OCBC Statement Savings Account | Minimum S$50,000 incremental fresh funds; no withdrawals during selected period | ~1.90% EIR for 188 days | S$50,000 to S$5 million of qualifying fresh funds |
| SingFinance GoSavers Account | No minimum balance, salary crediting or monthly spending requirement | 1.30% | First S$250,000 earns 1.30% p.a. |
| Mari Savings Account | No conditions | 0.88% | N/A |
| Stanchart JumpStart Account | Aged 18 – 26 only | 1.50% | Up to S$50,000 |
| Source: Beansprout calculations as of 3 November 2026 | |||
Are there any promotions for the UOB Stash Account?
Stash Savings Streak Challenge: Get up to S$195 cash rewards
UOB's stash savings streak challenge rewards depositors with cash rewards when you deposit at least S$1,000 into your UOB Stash Account each month for up to six months.
You would receive a S$20 cash reward for depositing S$1,000 into your account every month for the first three months.
Then, you would receive a S$45 cash reward for depositing S$1,000 into your account every month for the subsequent three months.
In total, you would receive cash rewards of S$195 if you have successfully deposited S$1,000 every month for six consecutive months.
| Savings Streak Month | Cash Reward |
| 1 | S$20 |
| 2 | S$20 |
| 3 | S$20 |
| 4 | S$45 |
| 5 | S$45 |
| 6 | S$45 |
| Total cash reward | S$195 |
| Source: UOB Stash Account page | |
To qualify, you would need to maintain an end-of-month balance of S$50,000 in your UOB Stash Account and not make any withdrawals.
The campaign is valid for users who are starting their savings streak from 1 October 2026 to 31 December 2026, subject to qualifying criteria.
UOB Online Account Opening Weekly Promotion: Get up to S$150 cash
If you are opening a new eligible UOB savings account online, you may also qualify for the UOB Online Account Opening Weekly Promotion, which runs from 1 November 2026 to 31 December 2026.
To qualify, you will generally need to:
- Open an eligible UOB savings account online during the promotion period
- Deposit at least S$10,000 in fresh funds within the same calendar month
- Maintain at least S$10,000 until the end of the following calendar month
The promotion is limited to the first 500 eligible customers during each promotion week.
The cash reward depends on your customer status:
| Customer | Cash reward |
|---|---|
| First 250 New-to-UOB Deposits customers | S$150 |
| First 250 Existing UOB Deposits customer | S$50 |
Eligible accounts: UOB One Account, UOB Stash Account, UOB Uniplus Account, UOB Lady’s Saving Account, KrisFlyer UOB Account and UOB Privilege Account.
UOB Festive Savings Promotion: Earn up to S$1,000 cash when you deposit up to S$150,000 in new funds
UOB is running a Festive Savings Promotion which will reward depositors with up to S$1,000 in cash for New-to-UOB deposits customers who deposit at least S$150,000 in new funds in its highest tier offering.
The reward details are shown in the table below.
| New funds amount | Cash Credit Amount (for Existing-to-UOB Deposits customers | Cash Credit Amount (For New-to-UOB Deposits Customers) |
| S$20,000 | S$80 | S$80 |
| S$50,000 | S$230 | S$230 |
| S$100,000 | S$500 | S$500 |
| S$150,000 | S$800 | S$1,000 |
| Source: UOB Stash Account page | ||
You would need to register your participation by filling in the form on the promotion page or via Rewards+ on the UOB TMRW app by 31 December 2026.
UOB SalaryPlus Promotion: get up to S$260 cash
UOB is also offering up to S$260 in cash rewards under its SalaryPlus Promotion.
After registering for the promotion, you can receive:
- S$180 for crediting a monthly salary of at least S$1,600, or at least S$500 for a full-time National Serviceman
- S$50 for crediting eligible CDP dividends of at least S$50 per transaction
- S$30 for making an eligible GIRO bill payment of at least S$30, or an eligible UOB home or car loan repayment
Together with the Online Account Opening Weekly Promotion, an eligible customer may receive up to S$410 in cash rewards, subject to meeting the respective promotion requirements.
Eligible accounts: UOB Passbook Savings Account, UOB Uniplus Account, UOB Stash® Account, UOB One Account, UOB Lady’s Savings Account or KrisFlyer UOB Account.
Note: You must not have already received similar UOB rewards, and/or performed these activities in your UOB account between 2023 and 31 December 2026.
Also, You won’t be eligible for the SalaryPlus Promotion if you’ve already received any reward from UOB (cash or otherwise) under any previous UOB salary-crediting, GIRO, or dividend-credit promotions.
What are the UOB Stash Account minimum balance and fees?
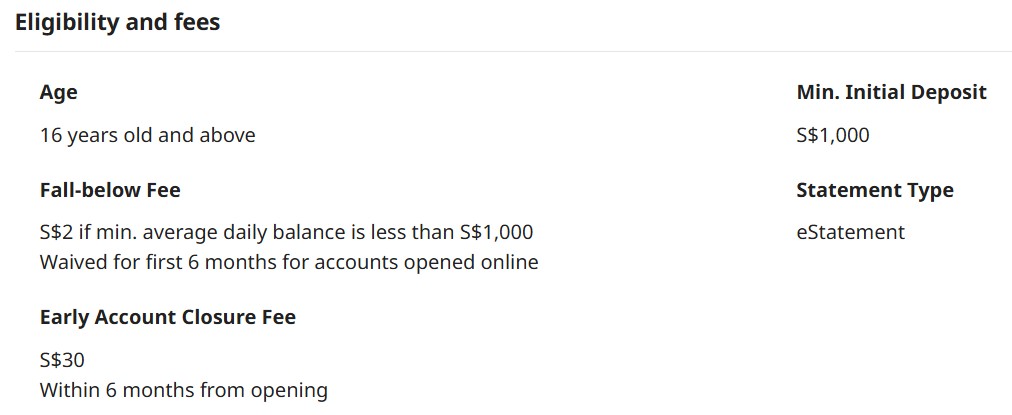
Another advantage of the UOB Stash Account is that it is easy to qualify for opening an account. You can open an account if you are 16 years old and above.
The minimum initial deposit for the UOB Stash Account is S$1,000.
If your monthly account balance falls below S$1,000, a S$2 fall-below fee will be imposed.
This is waived for the first six months for accounts opened online.
How to apply for the UOB Stash Account
To open a UOB Stash Account, follow these simple steps.
Step 1: Visit the UOB Stash account sign up form.
Step 2: Click on “Next”
Step 3: Apply with bank details or Singpass
You can even select to open the UOB One Account simultaneously if you don’t already have one.
Learn more about the UOB Stash Account here.

What would Beansprout do?
If I wanted to keep up to S$100,000 accessible without needing to credit my salary or meet a minimum card spend, I would consider the UOB Stash Account if I expect my monthly average balance to remain relatively stable.
For money in my Liquidity Pot, the UOB Stash Account offers the advantage of keeping my savings accessible while still earning interest.
At S$100,000, the account currently offers a maximum effective interest rate of 1.92% p.a., which works out to about S$1,920 of interest over a year if I continue to meet the monthly average balance requirement.
The main consideration for me would be whether I expect to withdraw from the account regularly. If my monthly average balance falls below the previous month's, I may earn only the 0.05% p.a. base interest for that month.
If I can meet the UOB One Account's card spending and salary crediting requirements, I would also compare its maximum effective interest rate of 1.90% p.a. on S$150,000. For additional cash beyond that amount, I can then compare UOB Stash with other savings options.
I would consider the UOB Stash Account promotions separately from the underlying account. For up to S$150,000 of qualifying new funds, existing UOB customers can receive up to S$800 while new-to-deposits customers can receive up to S$1,000, but the funds have to be earmarked for approximately seven months.
Not sure if UOB Stash is the right fit? Check out our guide to the best savings accounts in Singapore to find the savings account that best fits your needs.
I would also compare UOB Stash's rates and flexibility with other options for my cash, including fixed deposits, T-bills and Singapore Savings Bonds, before deciding where to keep my cash.
Follow us on Telegram, Youtube, Facebook and Instagram to get the latest financial insights on savings, investing and retirement planning.
This article contains affiliate links. Beansprout may receive a share of the revenue from your sign-ups to keep our site sustainable. You can view our editorial guidelines here.

Find out which savings account allows you to earn the highest interest rate on your savings.
Read also
Gain financial insights in minutes
Subscribe to our free weekly newsletter for more insights to grow your wealth
Most Popular

Questions and Answers
3 questions
- Jonathan • 21 Jun 2025 09:41 AM
- junyuan • 07 Nov 2024 03:53 AM
- rk • 27 Nov 2024 07:11 AM
- Dan • 04 Oct 2024 06:40 AM
- faridah • 07 Nov 2024 03:56 AM
