
How much do you need to retire in Singapore? 6 retirement planning lessons from MoneyOwl
CPF & Retirement
By Gerald Wong, CFA • 30 Oct 2026
Why trust Beansprout? We’ve been awarded Best Investment Website at the SIAS Investors’ Choice Awards 2025

Make Beansprout your preferred source on Google
Add us on Google to see more of our insights in your search results
How much do you really need to retire comfortably in Singapore? We speak with MoneyOwl's CEO and Chief Investment Officer about why retirement planning is more than reaching a savings target, and how CPF LIFE and investments can help provide retirement income.
What happened?
How much do we really need for retirement?
For many Singaporeans, this is one of the biggest financial questions we face, especially when we come across reports suggesting that we need S$550,000 or even more to retire comfortably.
But is there really a single number that tells us whether we have enough?
In the latest Beansprout Podcast, I spoke with Chuin Ting Weber, CEO and Chief Investment Officer of MoneyOwl, about how Singaporeans can approach retirement planning.
Chuin Ting shared why focusing on a large retirement savings target may not be the most useful starting point, and how we can instead plan around the income we need in retirement.
We also discussed the role of CPF LIFE, the risks of relying on investment income, and how MoneyOwl's Retirement Planner can help us understand whether we are on track.
Here are six key lessons from our conversation.
How much do you need to retire? 6 retirement planning lessons from interview with Chuin Ting Weber, CEO and Chief Investment Officer of MoneyOwl
#1 - Retirement planning is not just about reaching S$1 million
One of the most common questions about retirement planning is how much we need to save.
We often see estimates suggesting that Singaporeans need S$500,000, S$1 million or even S$1.4 million to retire comfortably.
However, Chuin Ting believes that focusing on a single savings target can be misleading.
The reason is that the amount we need depends on two important factors: our desired retirement lifestyle and how we intend to generate income from our savings.
During our conversation, she shared an example comparing two different approaches to retirement income.
In comparison, she explained that a CPF Full Retirement Sum of S$220,400 could provide a male CPF LIFE member with approximately S$1,700 in monthly payouts under the Standard Plan, based on the assumptions used in her example.
According to the CPF Board's published 2026 retirement sum figures, the Full Retirement Sum for members turning 55 in 2026 is S$220,400, with an estimated payout of S$1,780 per month from age 65 under the CPF LIFE Standard Plan.
The difference illustrates why we cannot simply compare retirement savings targets without considering how the money will be used.
For example, withdrawing a fixed amount from cash savings is very different from receiving monthly payouts through an annuity such as CPF LIFE.
An annuity pools longevity risk across members and can provide income for as long as we live, while cash savings may eventually run out.
This process of turning our accumulated savings into retirement income is known as decumulation.
| Approach | Example discussed | What matters |
|---|---|---|
| Drawing from retirement savings | S$550,000 for S$1,600 monthly income over 20 years | How savings are invested, withdrawn and sustained |
| Receiving CPF LIFE payouts | S$220,400 Full Retirement Sum, with approximately S$1,700 monthly payout cited in the interview | Lifelong income through an annuity, subject to applicable CPF LIFE terms |
| Source: Beansprout x MoneyOwl podcast transcript. Figures are interview examples rather than directly comparable projections. CPF's published 2026 illustration is S$1,780 per month from age 65 for a male member on the Standard Plan. | ||
The key lesson is that rather than asking whether we have accumulated S$1 million, we should first understand how much income we need and how our savings can provide it.
#2 - A good retirement plan needs to be sufficient, safe and flexible
Having enough savings is only one part of retirement planning.
Chuin Ting introduced MoneyOwl's Sufficiency, Safety and Flexibility (SSF) framework, which considers three dimensions of retirement income adequacy.
| Factor | What it means | What we need to consider |
|---|---|---|
| Sufficiency | Having enough income to cover retirement expenses | Whether income can cover our spending, inflation and the duration of retirement |
| Safety | Having reliable sources of retirement income | Whether income can continue even during periods of market uncertainty |
| Flexibility | Being able to access money when needed | Whether we can meet unexpected expenses without disrupting our retirement plan |
For sufficiency, Chuin Ting explained that we need to consider more than our spending in the first year of retirement.
Our retirement income also needs to last long enough and account for the rising cost of living.
She suggested planning for retirement to last around 25 to 30 years, with the possibility of living beyond age 90.
However, simply trying to generate the highest possible retirement income could expose us to additional risks.
For example, an investment product advertising a distribution rate of 7% or 8% may appear more attractive than a lower-paying alternative.
But the distribution may not be sustainable, and part of it could come from our original investment capital rather than investment returns.
This is why safety matters, particularly for income that we depend on to meet essential expenses.
At the same time, putting all our retirement savings into an annuity may leave us with insufficient flexibility.
We may still need access to cash for unexpected medical expenses, home repairs or other financial needs.
The challenge is finding an appropriate balance between these three factors, rather than maximising any one of them.
#3 - CPF LIFE can form the foundation of our retirement income
One of Chuin Ting's strongest messages was that Singaporeans should start their retirement planning by understanding what they already have in CPF.
In particular, she highlighted the role of CPF LIFE in providing lifelong retirement income.
CPF LIFE is a national annuity scheme that provides monthly payouts for as long as we live.
Unlike a retirement portfolio that may eventually be depleted through withdrawals, CPF LIFE helps address the risk of outliving our savings.
This makes it particularly relevant for covering essential retirement expenses.
Chuin Ting explained that she would separate retirement spending into two broad categories.
The first consists of essential expenses, such as food, utilities and other daily living costs.
For these expenses, having a reliable income source is more important than maintaining complete flexibility.
The second category consists of additional lifestyle expenses, such as holidays, hobbies and other discretionary spending.
For these expenses, flexibility becomes more important because we may be able to adjust our spending depending on our financial circumstances.
This distinction helps explain how CPF LIFE can fit into a broader retirement plan.
| Retirement needs | Potential source of income | Main consideration |
|---|---|---|
| Essential living expenses | CPF LIFE | Reliable lifelong payouts |
| Additional lifestyle expenses | Diversified investment portfolio | Potential returns and flexibility |
| Unexpected expenses | Accessible cash savings | Liquidity and capital stability |
CPF LIFE payouts are not necessarily sufficient to cover every retirement expense, and their purchasing power may decline over time because of inflation.
However, Chuin Ting believes that CPF LIFE provides a useful starting point before considering other retirement income products.
The more useful question is how much of our essential spending can CPF LIFE cover, rather than whether it can fund our desired retirement lifestyle.
#4 - The 4% withdrawal rule can help us plan investment income
After establishing a foundation of retirement income through CPF LIFE, we may still need additional income to support our desired lifestyle.
Chuin Ting shared that MoneyOwl favours using a diversified, low-cost investment portfolio for this additional layer.
Rather than relying entirely on dividends, the approach considers the total return from investments, including income and capital gains.
One method MoneyOwl uses as a planning reference is the 4% withdrawal rule.
Under the traditional version of this rule, a retiree withdraws 4% of the initial investment portfolio in the first year of retirement and subsequently adjusts that amount for inflation.
For example, someone retiring with a S$500,000 investment portfolio would initially withdraw S$20,000 a year, or approximately S$1,667 a month.
The following year's withdrawal would then be adjusted based on inflation rather than simply recalculated as 4% of the remaining portfolio.
| Initial investment portfolio | First-year withdrawal at 4% | Monthly equivalent |
|---|---|---|
| S$250,000 | S$10,000 | S$833 |
| S$500,000 | S$20,000 | S$1,667 |
| S$750,000 | S$30,000 | S$2,500 |
| S$1,000,000 | S$40,000 | S$3,333 |
| Source: Beansprout calculations based on a hypothetical initial withdrawal rate of 4%. Figures are illustrative and do not represent guaranteed or sustainable payouts. | ||
However, Chuin Ting emphasised that the 4% withdrawal rule is not a guarantee that our savings will last throughout retirement.
The rule draws on historical research, largely involving US investment portfolios, and its effectiveness depends on factors such as asset allocation, market returns, inflation and retirement duration.
One particularly important risk is the order in which investment returns occur.
For example, if our investment portfolio falls by 20% from S$100,000 to S$80,000, it would need to recover by 25% just to return to its original value.
If we are also withdrawing money during the downturn, the remaining portfolio would need an even stronger recovery.
This is commonly known as sequence-of-returns risk.
It explains why a portfolio that delivers reasonable long-term returns may still struggle to support retirement withdrawals if markets perform poorly during the early years of retirement.
Therefore, Chuin Ting prefers a diversified, low-cost portfolio rather than relying heavily on a small number of dividend-paying stocks.
While dividends can provide cash flow, dividend-paying companies can still experience falling share prices, reduced earnings or dividend cuts.
The key lesson is that retirement income should be planned around the sustainability of withdrawals, rather than simply targeting the highest possible dividend yield.
#5 - Retirement planning should start with what we already have
Another lesson from our conversation was that retirement planning does not need to begin with complicated calculations.
Instead, Chuin Ting suggested starting by understanding our existing financial position.
This includes our CPF savings, cash, investments, current income and expected retirement expenses.
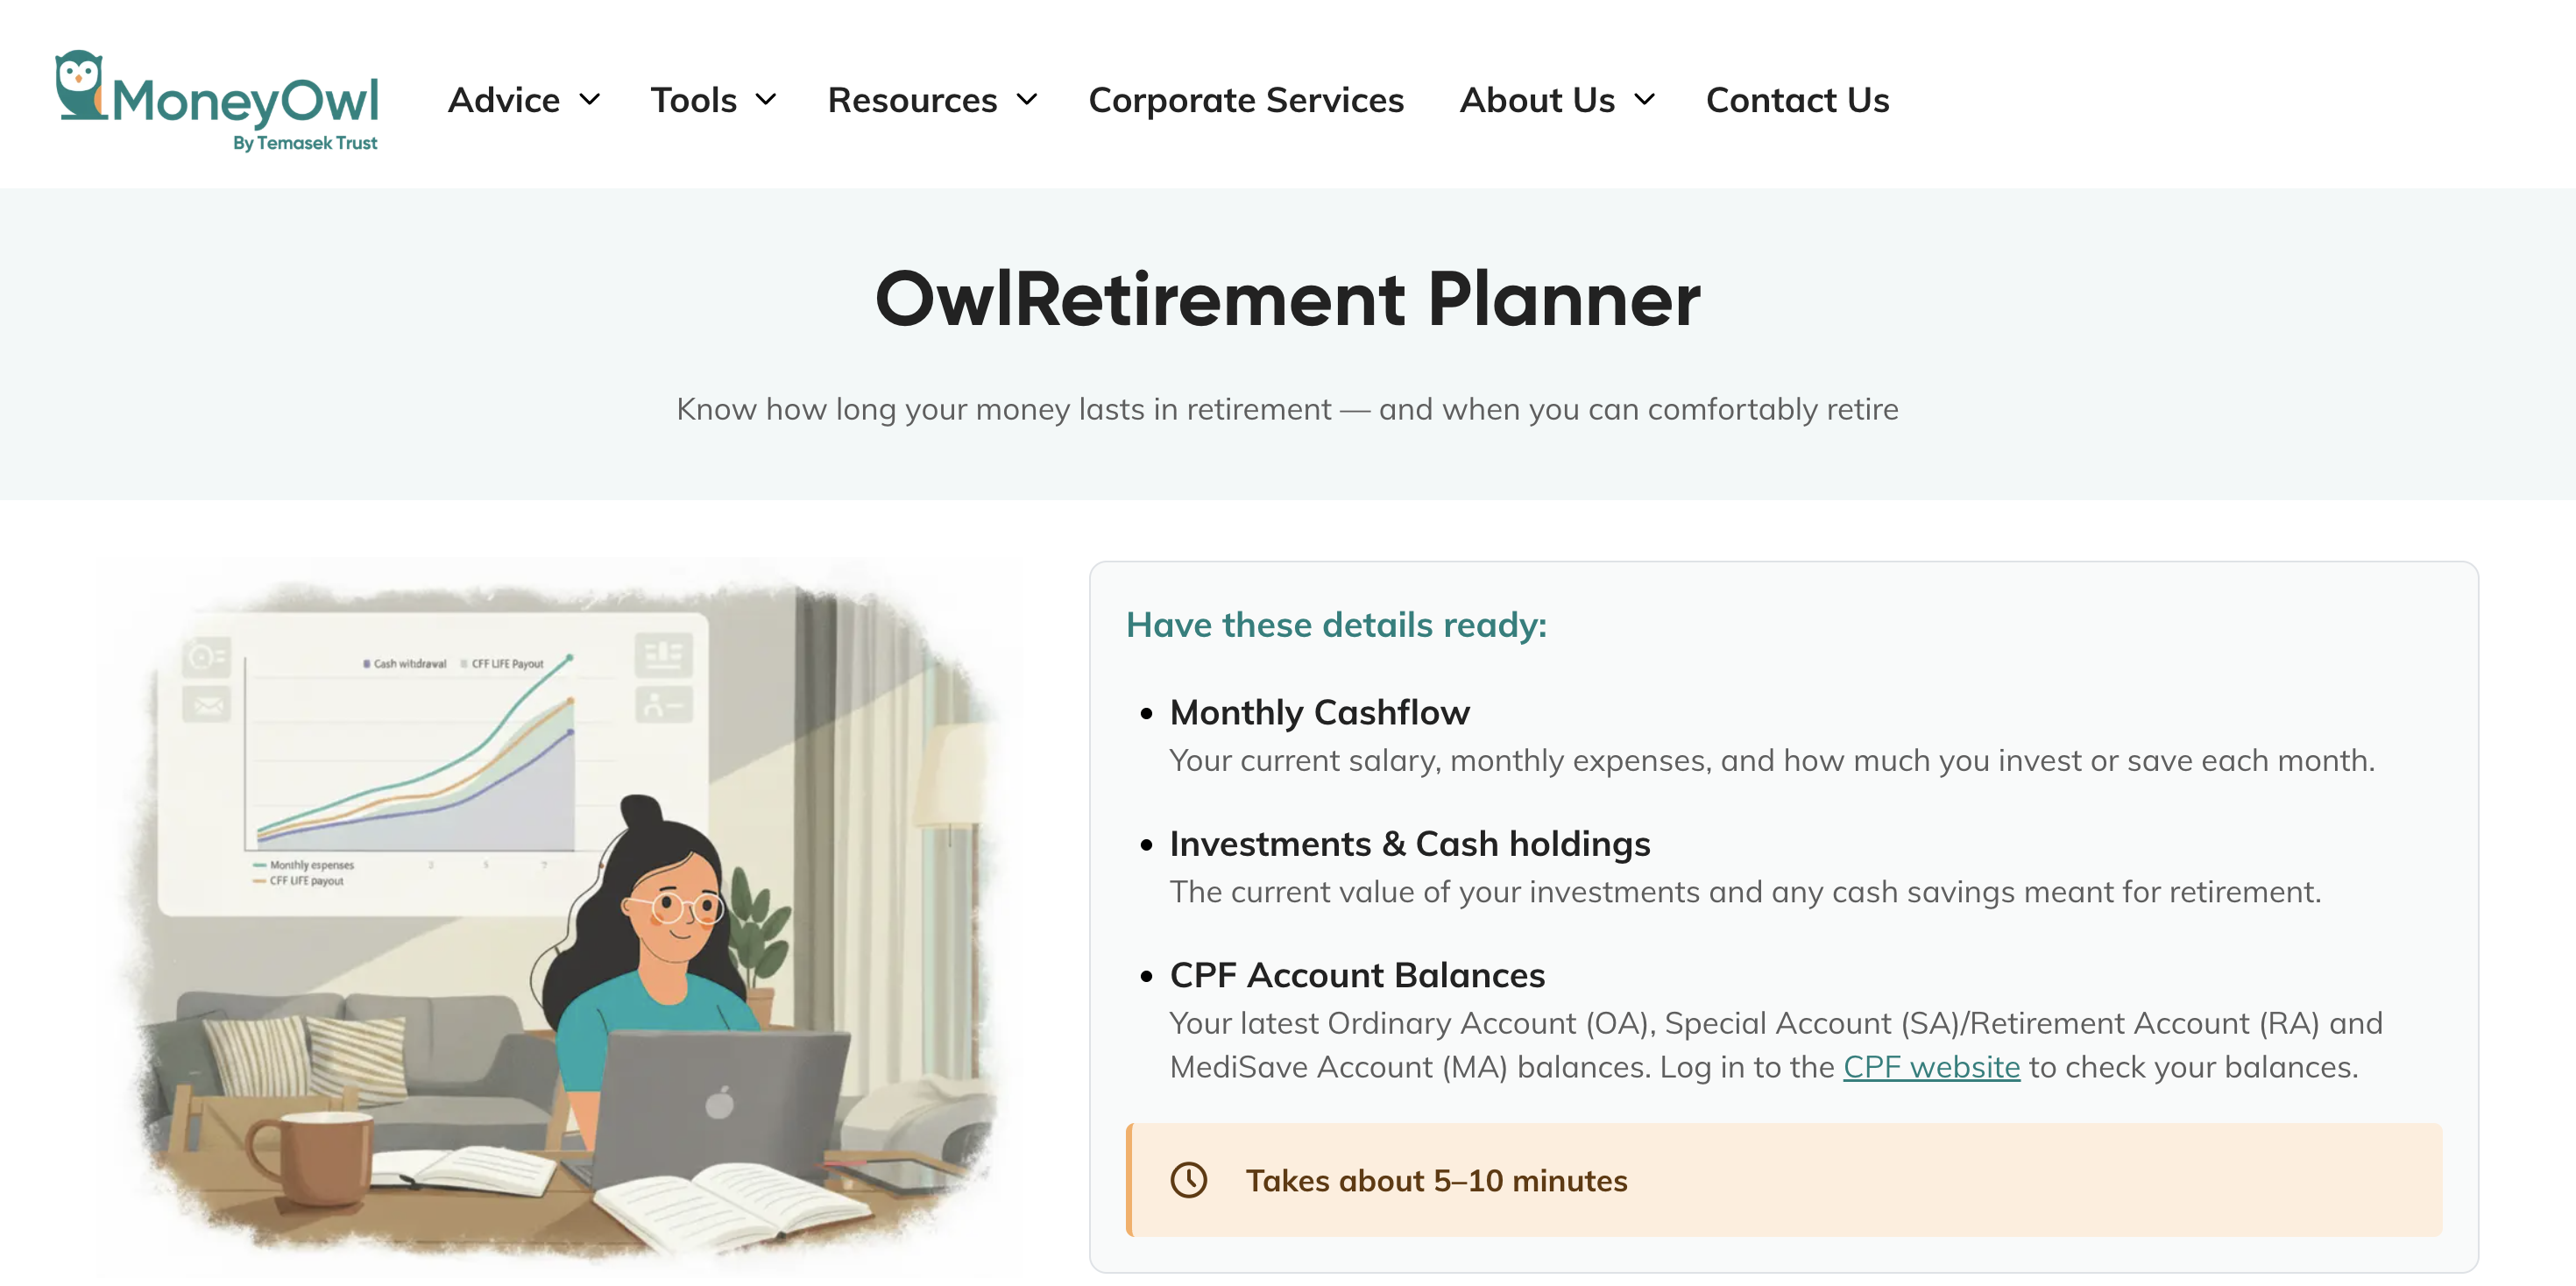
To help Singaporeans bring these different pieces together, MoneyOwl developed an OwlRetirement Planner.
According to Chuin Ting, the planner was designed to provide a consolidated view of retirement income, rather than focusing only on CPF balances or investment portfolios separately.
Users can enter information such as their current salary, expected salary growth, CPF balances, investments, savings and desired retirement spending.
The tool then projects potential retirement income from different sources, including CPF LIFE, investment withdrawals and available cash.
It also assesses the projected retirement income against MoneyOwl's Sufficiency, Safety and Flexibility framework.
This can help us identify whether our retirement income may fall short of our expected spending or whether we have sufficient flexibility to meet unexpected needs.
Chuin Ting shared that most users could complete an initial assessment in around five to ten minutes, provided they have their financial information ready.
She also explained that the planner allows users to test different retirement scenarios, although access to some features requires subscribing to MoneyOwl's mailing list.
I think the useful part of such a tool is not necessarily the exact retirement number it produces.
Rather, it helps us see how our different sources of retirement income fit together and which assumptions have the greatest impact on our plan.
For example, we may discover that CPF LIFE already covers a meaningful portion of our essential expenses.
Alternatively, we may realise that our projected retirement income depends heavily on investment returns, leaving us more exposed to market downturns than expected.
These projections are based on assumptions and should not be treated as guaranteed outcomes, but they can provide a starting point for making more informed decisions.
#6 - If we are not on track for retirement, we still have options
One concern that often prevents people from planning for retirement is the fear of discovering that they have not saved enough.
However, Chuin Ting pointed out that identifying a retirement shortfall is useful because it allows us to consider what we can change.
For example, we may be able to increase our savings, adjust our retirement spending expectations or work for a few more years.
We could also review how our investments are structured or whether additional CPF contributions could help strengthen our retirement income.
Each decision comes with trade-offs.
Delaying retirement may allow us to accumulate more savings while reducing the number of years we need to fund.
Increasing our investment exposure may improve potential long-term returns, but it also introduces greater market risk.
Making additional CPF contributions could increase our future retirement income, subject to CPF rules and limits, but may reduce the cash we have available for other needs.
Meanwhile, reducing our expected retirement spending may make our financial plan more achievable, although it could require lifestyle adjustments.
The purpose of retirement planning is not necessarily to find a way to retire as early as possible.
It is to understand which trade-offs we are comfortable making and whether our financial resources can support the retirement lifestyle we want.
Chuin Ting also highlighted housing wealth as another potential consideration for Singaporeans, although MoneyOwl's planner did not yet incorporate a home monetisation module at the time of the interview.
This is particularly relevant for homeowners who may have substantial wealth tied up in their property but relatively limited liquid savings.
The important point is that retirement planning is not a one-time exercise.
As our income, expenses and financial circumstances change, we can revisit our assumptions and adjust our plans accordingly.
Watch the full podcast episode here.
Enjoyed this insight? Follow Beansprout on Telegram, Youtube, Facebook and Instagram, and add Beansprout as your preferred source on Google so you never miss an update.
Read also
Gain financial insights in minutes
Subscribe to our free weekly newsletter for more insights to grow your wealth
Most Popular

Comments
0 comments