
UI Boustead REIT's debut DPU beats expectations
REITs
By Goh Lay Peng • 06 Nov 2026
Global Wealth Technology Pte. Ltd. is regulated by the Monetary Authority of Singapore (MAS) as a licensed Financial Adviser.

Make Beansprout your preferred source on Google
Add us on Google to see more of our insights in your search results
UI Boustead REIT (UIBU) reported its first set of results, ending 30 September 2026. DPU debut of 3.71 cents was 0.8% ahead of forecast. At S$0.77, UIBU trades at FY27 distribution yield 8.8%.
UI Boustead REIT - DPU debut exceeds forecast
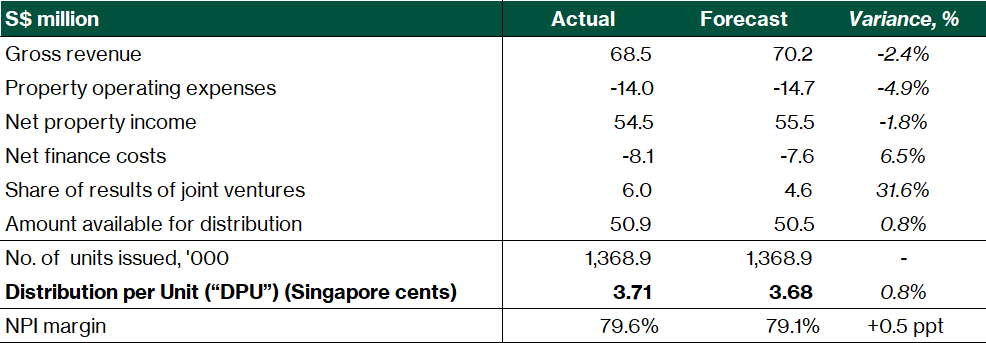 |
Source: UI Boustead REIT results presentation Note : Forecast figures are pro-rated from the prospectus forecast for 1 February to 31 March 2026 and the projection for the year ending 31 March 2027 |
UI Boustead REIT (UIBU) reported its first set of results, covering the period from 3 July 2025 to 30 September 2026.
The REIT was a dormant private trust until 11 March 2026, so actual income covers only the period from the IPO date 12 March 2026.
Gross revenue was S$68.5 million, 2.4% below forecast.
Property operating expenses were 4.9% below forecast. As a result, net property income (NPI) was S$54.5 million, or 1.8% lower.
Management attributes the NPI shortfall to occupancy below forecast and a weaker Japanese yen against the Singapore dollar.
Net finance costs of S$8.1 million were 6.5% above forecast, mainly because of higher debt costs in Japan. The Bank of Japan raised its policy rate to 1.25% from 1.0% in September and signalled that further hikes are possible.
Expected FY2027 Japanese Yen distribution income has been substantially hedged into Singapore dollars.
DPU of 3.71 cents was 0.03 cents or 0.8% ahead of the 3.68 cents forecast. The distribution comprises 2.98 cents of taxable income, 0.32 cents of tax-exempt income and 0.41 cents of capital distribution. The capital portion is about 11% of the DPU.
At S$0.77, UIBU trades at FY27 distribution yield 8.8%.
We think overall performance for the reported period was satisfactory, including the better than expected net property margin, at 79.6%.
Amount available for distribution – variance to Forecast, S$ ‘000 |
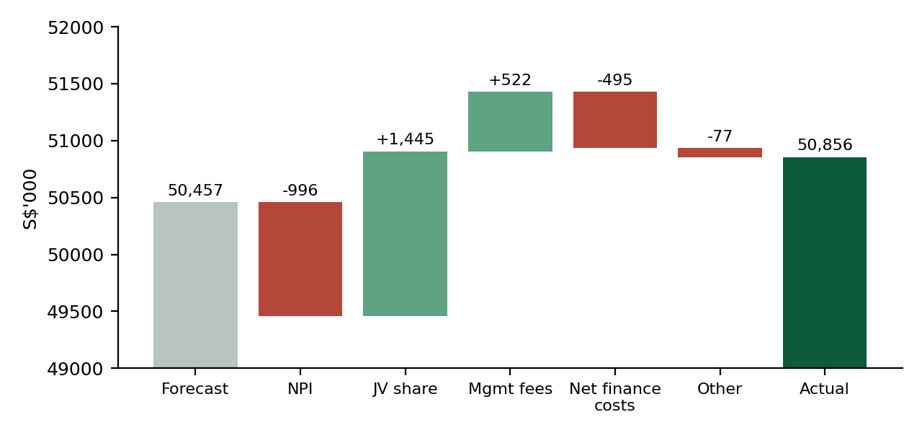 |
Source: Company data, Beansprout research. Note : “Other” is the residual between the sum of the listed line items and the reported variance |
The variance bridge against forecast highlights the key drivers of the outperformance in distributable income.
Share of income of joint ventures was S$1.4 million higher than forecast. UI Boustead REIT recorded higher income from share of results of joint ventures, mainly attributed to better performance at Razer SEA HQ and 6 Tampines Industrial Avenue 5.
Management fees was S$0.52 million lower, partly absorbed by S$0.49 million of higher net finance costs.
Management fees are paid 80% in units by election, but the effective proportion in units was about 53% for the period from listing to 30 September 2026.
 |
Source: UI Boustead REIT results presentation |
Healthy balance sheet
 |
Source: UI Boustead REIT results presentation |
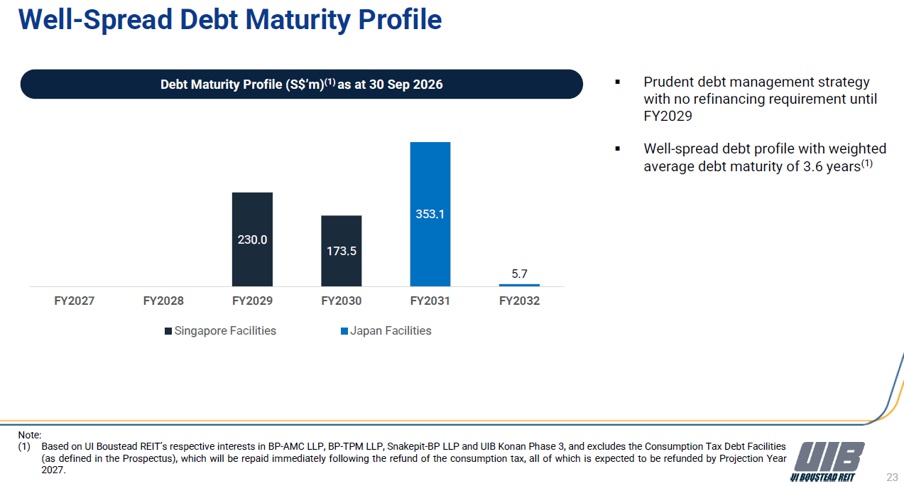
UI Boustead REIT maintains a well-spread debt maturity profile, with no refinancing requirements until FY2029.
As at 30 September 2026, its weighted average debt maturity stood at 3.6 years, providing the REIT with sufficient visibility to manage its refinancing needs.
47% of the total borrowings will mature after five years.
The absence of near-term refinancing requirements provides the manager with time to plan ahead and manage funding costs.
Balance sheet highlights |
 |
Source: UI Boustead REIT results |
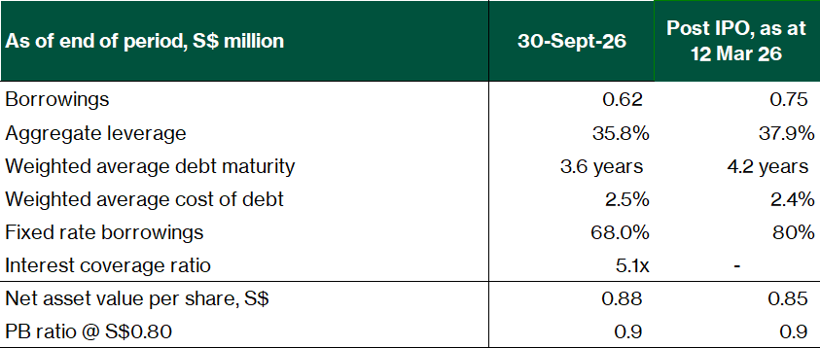
The REIT's prudent capital management is also reflected in its aggregate leverage of 35.8%, weighted average all-in cost of debt of 2.5% and interest coverage ratio of 5.1 times as at 30 September 2026.
Aggregate leverage was 35.8% as at 30 September 2026, leaving about S$320 million of debt headroom to the 45% regulatory limit
In addition, approximately 68% of its debt is on a fixed-rate basis, providing some protection against interest rate volatility.
Japan debt is 46% of the total, and the REIT maintains a natural capital hedge of about 65% on its Japan assets.
Total debt, by type and currency 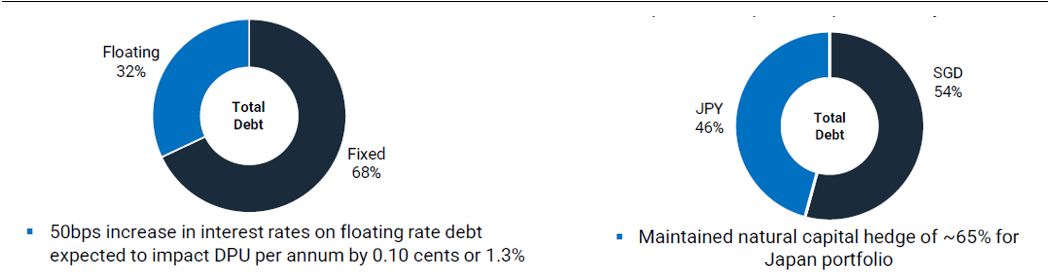 |
Source: UI Boustead REIT results presentation |
Portfolio performance improved on higher occupancy in Japan
 |
Source: UI Boustead REIT results presentation |
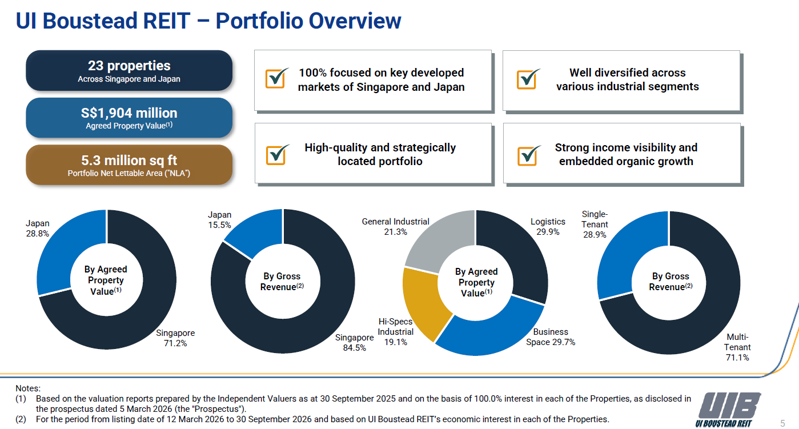
The portfolio of 23 properties (21 in Singapore, two in Japan) has an agreed property value of S$1.9 billion.
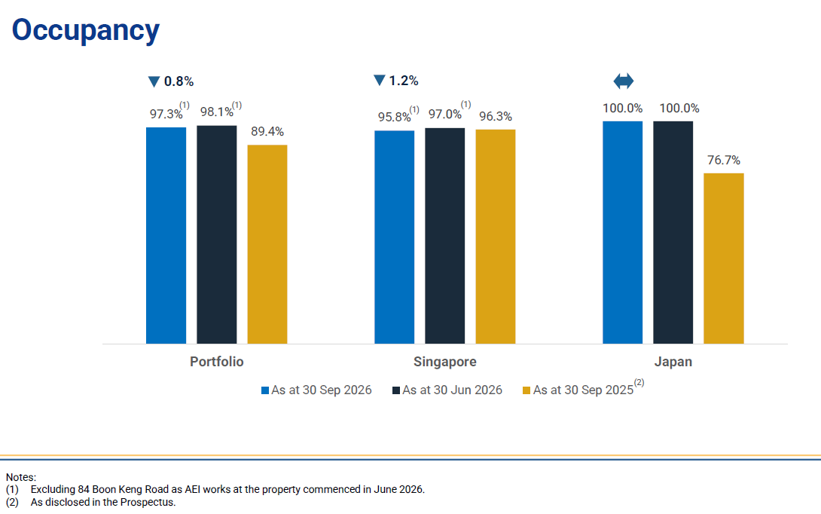
Committed occupancy was 97.3% as at 30 September 2026, excluding 84 Boon Keng Road where asset enhancement works started in June 2026.
That is 0.8 ppt lower than at 30 June 2026 but well above the 89.4% disclosed in the prospectus as at 30 September 2025.
The Japan portfolio is fully occupied (76.7% a year earlier).
Singapore occupancy fell 1.2 ppt to 95.8%, with logistics down 2.0 ppt to 98.0% and business space up 0.2 ppt to 96.3%.
The weakest assets by committed occupancy are 12 Changi North Way (80.5%, logistics), 6 Tampines Industrial Avenue 5 (86.6%) and ALICE@Mediapolis (91.6%). The occupancy gaps at these three assets have the most leasing upside, and the main risk if vacancy persists.
 |
Source: UI Boustead REIT results presentation |
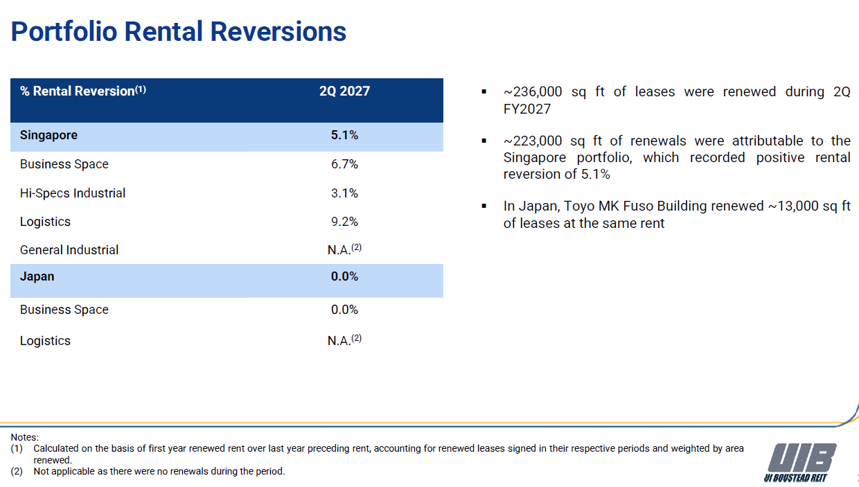
About 236,000 sq ft of leases were renewed in the quarter to 30 September 2026.
Of which about 223,000 sq ft was in Singapore at a +5.1% reversion.
Logistics was strongest at +9.2%, followed by business space at +6.7% and Hi-Specs industrial at +3.1%.
In Japan, about 13,000 sq ft at Toyo MK Fuso Building was renewed at the same rent.
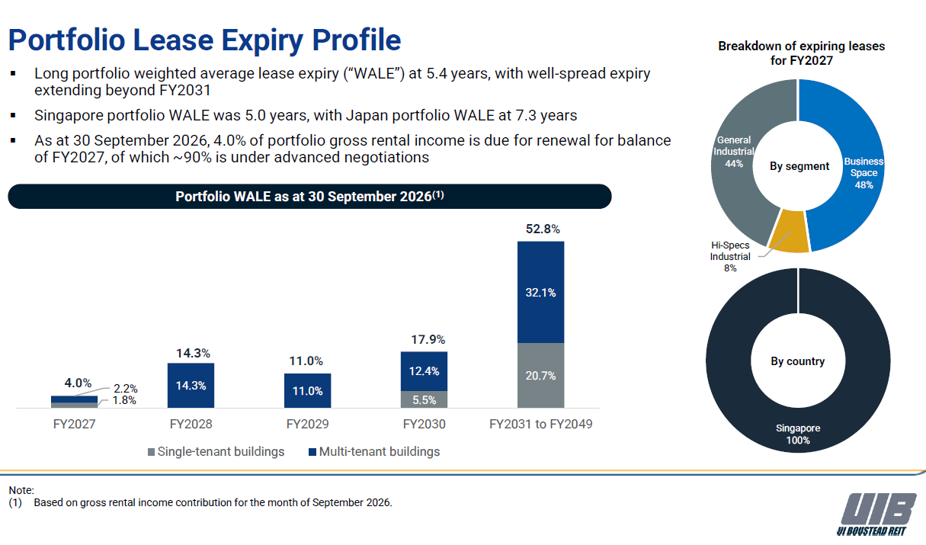 |
Lease expiry is well spread. WALE is 5.4 years (Singapore 5.0 years, Japan 7.3 years).
Only 4.0% of gross rental income expires in the rest of FY2027, with about 90% of that under advanced negotiations.
FY2028 is the next heavier year at 14.3%, and management has started engaging those tenants.
The top 10 tenants contribute about 48% of NPI with a WALE of 7.8 years, and all are owned by Fortune 500, Fortune 500 Europe or listed multinational corporations.
Portfolio metrics |
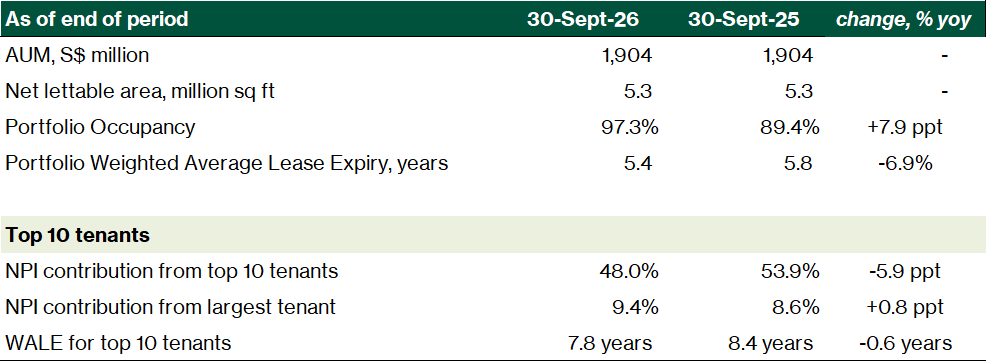 |
Updates on co-developments and AEI
UIBU leverages on its fully-integrated platform to execute a differentiated strategy.
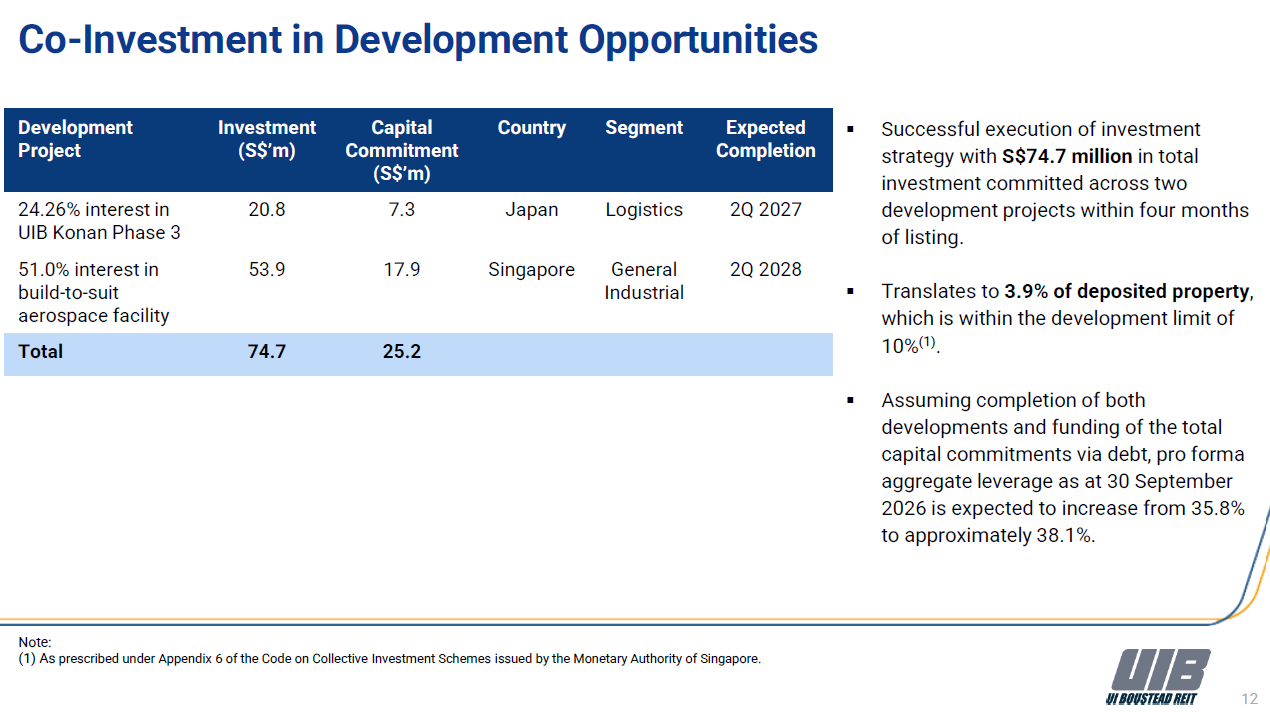
In April and May 2026, UIBU separately announced two co-investments with the Sponsor. The two deals totalled S$74.7 million of investment value and S$25.2 million of capital commitment.
Both come with options to buy the balance interest, which gives a visible acquisition pipeline.
The 4.8% yield on cost at UIB Konan Phase 3 compares with the 4.0% yield at which the balance can be bought, indicating a development margin of about 80 bps.
The aerospace facility has a much higher 8.6% yield on cost and a long lease of about 22.5 years with built-in escalations.
 |
Source: UI Boustead REIT results presentation |
Both developments are on schedule.
The REIT’s S$74.7 million interest equals 3.9% of deposited property against the 10% development limit.
Funding the S$25.2 million of capital commitments entirely with debt would lift aggregate leverage from 35.8% to about 38.1%.
With units yielding about 8.3%, buying the balance of Konan Phase 3 at a 4.0% yield would be dilutive if funded with new equity and accretive only if debt-funded, so the funding mix will determine whether these acquisitions lift DPU.
Asset enhancement initiative on track to completion |
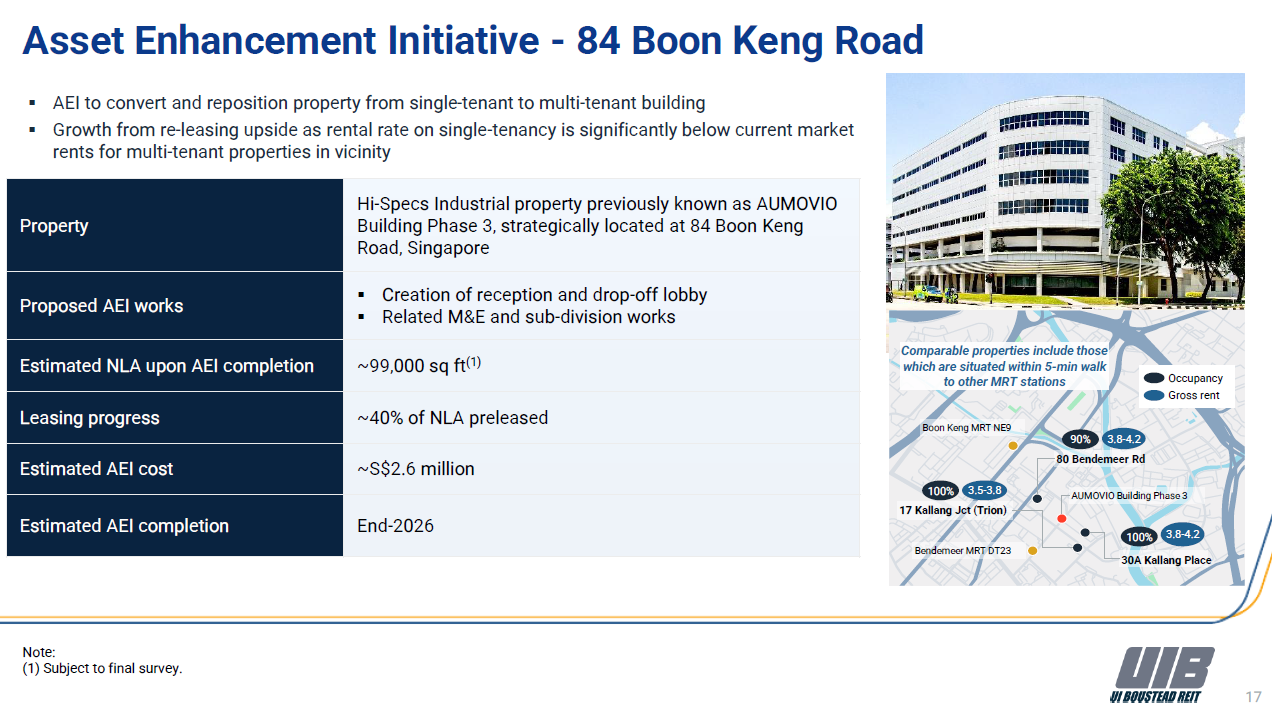 |
Separately, the asset enhancement at 84 Boon Keng Road is on track to complete by end-2026 at an estimated cost of S$2.6 million.
It converts the property from single-tenant to multi-tenant, adds a reception, lift lobby and drop-off area, and gives about 99,000 sq ft of NLA.
About 40% of NLA is pre-committed.
Management says the existing rent is significantly below multi-tenant market rents nearby, where comparable buildings quote gross rents of S$3.50 to S$4.20 psf.
Upon completion, this property will contribute to the reported portfolio occupancy.
Valuation
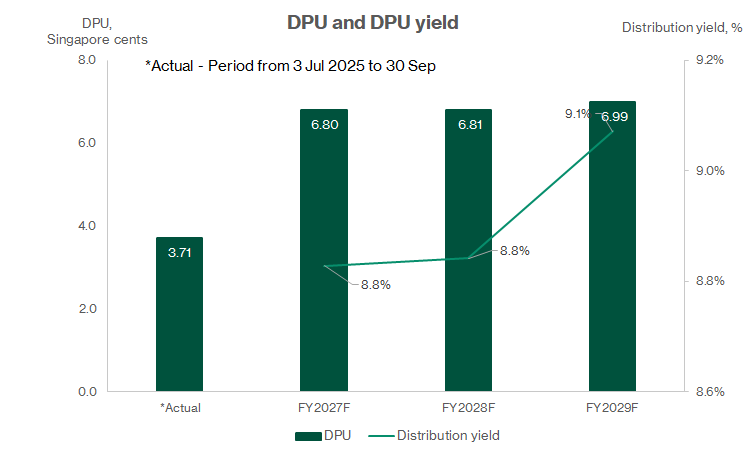 |
At the current price S$0.77, UI Boustead REIT offers distribution yield 8.8% versus the peers’ average distribution yield of 7.2% for FY2027E. Based on visible pipeline from organic growth and inorganic asset acquisition, UI Boustead REIT is able to deliver the projected distribution yield.
In addition, there are potential uplift to the distribution income from acquisition and co-development opportunities.
Based on the reported net asset value (NAV) of S$0.88 per unit as at 30 September 2026, UIBU is trading at P/B ratio of 0.88x, below the sector average P/B of 1.05x.
Peer comparison |
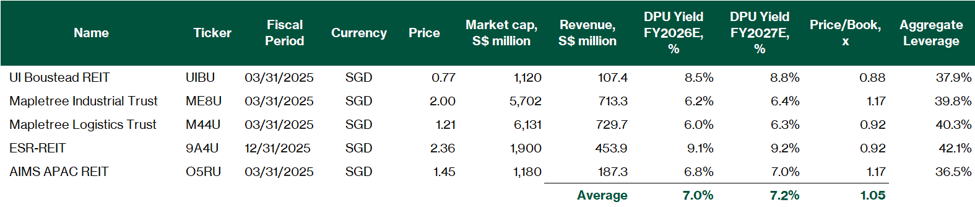 |
Source: Factset, Beansprout research, as at 2 November 2026 |
Key risks
Key risks include concentrated two-market exposure, foreign exchange risk, lease expiry and tenant concentration risk, and regulatory exposure.
Concentrated asset type and geographic exposure
UI Boustead REIT's portfolio is exclusively comprised of industrial, logistics and business space assets in Singapore and Japan. While both are developed markets which offer attractive fundamentals, the REIT's financial performance is exposed to risks specific to these two markets and sectors.
Limited duration of lease tenures
The lease tenures of industrial land of Singapore are typically limited to 30 years, relatively short compared to other commercial land use. For UI Boustead REIT, 13 of the 21 Singapore Properties have lease tenure of less than 30 years. A significant portion of operating profits is generated from these properties of limited duration. The 13 properties account for 61.4% of the portfolio’s operating profits in FY2025. Besides the loss of income, the decay in lease terms will also adversely affect the valuation of the portfolio.
Lease expiry and tenant concentration risk
While the portfolio has a healthy WALE of 5.8 years, approximately 38.5% of tenants by Gross Rental Income have balance leases of less than three years. Any failure to renew leases at favourable terms or the early departure of a major tenant — such as AUMOVIO, which has already issued a notice of termination of its lease at AUMOVIO Building Phase 3 — could adversely affect the REIT's distributable income.
Foreign exchange risk
28.8% of the IPO Portfolio by Agreed Property Value is in Japan. Distributions from the Japan Properties will be impacted by fluctuations in the SGD/JPY exchange rate. The REIT may employ hedging strategies to mitigate this risk, though there is no assurance that these will fully offset currency movements.
Interest rate risk
While approximately 80% of borrowings are on fixed rates, rising interest rates could increase refinancing costs upon debt maturity, reduce distribution coverage, and compress the yield spread relative to risk-free rates, affecting unit price performance.
Regulatory and planning risk
Industrial and logistics properties in Singapore are subject to JTC land lease conditions, URA zoning requirements, and evolving environmental regulations. In Japan, ongoing regulatory changes affecting logistics operations may affect the operating environment.
Related links:
- UI Boustead REIT share price history and share price target
- UI Boustead REIT dividend history and forecast
Check out Beansprout guide to the best stock trading platforms in Singapore with the latest promotions to UI Boustead REIT.
Download the full report here.
Join the Beansprout Telegram group for the latest insights on Singapore stocks, REITs, bonds and ETFs.
Important Disclosures
Analyst Certification and Disclosures
The analyst(s) named in this report certifies that (i) all views expressed in this report accurately reflect the personal views of the analyst(s) with regard to any and all of the subject securities and companies mentioned in this report and (ii) no part of the compensation of the analyst(s) was, is, or will be, directly or indirectly, related to the specific views expressed by that analyst herein. The analyst(s) named in this report (or their associates) does not have a financial interest in the corporation(s) mentioned in this report.
An associate is defined as (i) the spouse, or any minor child (natural or adopted) or minor step-child, of the analyst; (ii) the trustee of a trust of which the analyst, his spouse, minor child (natural or adopted) or minor step-child, is a beneficiary or discretionary object; or (iii) another person accustomed or obliged to act in accordance with the directions or instructions of the analyst.
Company Disclosure
Global Wealth Technology Pte Ltd (“Beansprout”) does not have any financial interest in the corporation(s) mentioned in this report.
Disclaimer
This report is provided by Beansprout for the use of intended recipients only and may not be reproduced, in whole or in part, or delivered or transmitted to any other person without our prior written consent. By accepting this report, the recipient agrees to be bound by the terms and limitations set out herein.
You acknowledge that this document is provided for general information purposes only. Nothing in this document shall be construed as a recommendation to purchase, sell, or hold any security or other investment, or to pursue any investment style or strategy. Nothing in this document shall be construed as advice that purports to be tailored to your needs or the needs of any person or company receiving the advice. The information in this document is intended for general circulation only and does not constitute investment advice. Nothing in this document is published with regard to the specific investment objectives, financial situation and particular needs of any person who may receive the information.
Nothing in this document shall be construed as, or form part of, any offer for sale or subscription of or solicitation or invitation of any offer to buy or subscribe for any securities. The data and information made available in this document are of a general nature and do not purport, and shall not in any way be deemed, to constitute an offer or provision of any professional or expert advice, including without limitation any financial, investment, legal, accounting or tax advice, and shall not be relied upon by you in that regard. You should at all times consult a qualified expert or professional adviser to obtain advice and independent verification of the information and data contained herein before acting on it. Any financial or investment information in this document are intended to be for your general information only. You should not rely upon such information in making any particular investment or other decision which should only be made after consulting with a fully qualified financial adviser. Such information do not nor are they intended to constitute any form of financial or investment advice, opinion or recommendation about any investment product, or any inducement or invitation relating to any of the products listed or referred to. Any arrangement made between you and a third party named on or linked to from these pages is at your sole risk and responsibility.
You acknowledge that Beansprout is under no obligation to exercise editorial control over, and to review, edit or amend any data, information, materials or contents of any content in this document. You agree that all statements, offers, information, opinions, materials, content in this document should be used, accepted and relied upon only with care and discretion and at your own risk, and Beansprout shall not be responsible for any loss, damage or liability incurred by you arising from such use or reliance.
This document (including all information and materials contained in this document) is provided “as is”. Although the material in this document is based upon information that Beansprout considers reliable and endeavours to keep current, Beansprout does not assure that this material is accurate, current or complete and is not providing any warranties or representations regarding the material contained in this document. All opinions contained herein constitute the views of the analyst(s) named in this report, they are subject to change without notice and are not intended to provide the sole basis of any evaluation of the subject securities and companies mentioned in this report. Any reference to past performance should not be taken as an indication of future performance. To the fullest extent permissible pursuant to applicable law, Beansprout disclaims all warranties and/or representations of any kind with regard to this document, including but not limited to any implied warranties of merchantability, non-infringement of third-party rights, or fitness for a particular purpose.
Beansprout does not warrant, either expressly or impliedly, the accuracy or completeness of the information, text, graphics, links or other items contained in this document. Neither Beansprout nor any of its affiliates, directors, employees or other representatives will be liable for any damages, losses or liabilities of any kind arising out of or in connection with the use of this document. To the best of Beansprout’s knowledge, this document does not contain and is not based on any non-public, material information. The information in this document is not intended for distribution to, or use by, any person or entity in any jurisdiction where such distribution or use would be contrary to law or regulation, or which would subject Beansprout to any registration requirement within such jurisdiction or country. Beansprout is not licensed or regulated by any authority in any jurisdiction or country to provide the information in this document.
As a condition of your use of this document, you agree to indemnify, defend and hold harmless Beansprout and its affiliates, and their respective officers, directors, employees, members, managing members, managers, agents, representatives, successors and assigns from and against any and all actions, causes of action, claims, charges, cost, demands, expenses and damages (including attorneys’ fees and expenses), losses and liabilities or other expenses of any kind that arise directly or indirectly out of or from, arising out of or in connection with violation of these terms, use of this document, violation of the rights of any third party, acts, omissions or negligence of third parties, their directors, employees or agents. To the extent permitted by law, Beansprout shall not be liable to you, any other person, or organization, for any direct, indirect, special, punitive, exemplary, incidental or consequential damages, whether in contract, tort (including negligence), or otherwise, arising in any way from, or in connection with, the use of this document and/or its content. This includes, without limitation, liability for any act or omission in reliance on the information in this document. Beansprout expressly disclaims and excludes all warranties, conditions, representations and terms not expressly set out in this User Agreement, whether express, implied or statutory, with regard to this document and its content, including any implied warranties or representations about the accuracy or completeness of this document and the content, suitability and general availability, or whether it is free from error.
If these terms or any part of them is understood to be illegal, invalid or otherwise unenforceable under the laws of any state or country in which these terms are intended to be effective, then to the extent that they are illegal, invalid or unenforceable, they shall in that state or country be treated as severed and deleted from these terms and the remaining terms shall survive and remain fully intact and in effect and will continue to be binding and enforceable in that state or country.
These terms, as well as any claims arising from or related thereto, are governed by the laws of Singapore without reference to the principles of conflicts of laws thereof. You agree to submit to the personal and exclusive jurisdiction of the courts of Singapore with respect to all disputes arising out of or related to this Agreement. Beansprout and you each hereby irrevocably consent to the jurisdiction of such courts, and each Party hereby waives any claim or defence that such forum is not convenient or proper.
Read also
Gain financial insights in minutes
Subscribe to our free weekly newsletter for more insights to grow your wealth
Most Popular

Comments
0 comments