
AutoWealth SmartSave: What to know about its workplace savings and investment scheme
Robo Advisor
Powered by
By Nicole Ng • 20 Nov 2026
Why trust Beansprout? We’ve been awarded Best Investment Website at the SIAS Investors’ Choice Awards
Explore how AutoWealth SmartSave works, what it offers employees and employers, and the key considerations to keep in mind.
This post was created in partnership with AutoWealth. All views and opinions expressed in this article are Beansprout’s objective and professional opinions.
What happened?
I have been thinking about how to build up my retirement savings while keeping up with everyday expenses.
Setting money aside is one part of the process, but deciding how to invest it and managing those investments over time can feel more complicated.
Some employers offer savings and investment programmes as part of their employee benefits, providing access to managed investments and financial guidance.
One example is AutoWealth SmartSave, a workplace financial wellness scheme offered through participating employers.
The arrangements can differ between companies, so I would want to understand the investments, fees, and conditions before participating.
In this article, I look at how SmartSave works, what it offers employees and employers, and the key considerations to keep in mind.
What is AutoWealth SmartSave?
AutoWealth is a Singapore-based digital wealth management platform founded in 2015. It is licensed by the Monetary Authority of Singapore to provide financial advisory services.
Alongside its retail portfolios, AutoWealth offers SmartSave, a financial wellness scheme that employers can incorporate into their employee benefits.
The service covers four areas:
- Plan administration: Support for running the workplace scheme.
- Trust setup: Assistance with establishing a trust arrangement as part of the scheme, where applicable.
- Managed investments: Investment portfolios managed through AutoWealth.
- Financial advice: Access to guidance on financial planning and the scheme.
SmartSave’s investment plans and platform can be customised to an organisation’s requirements.
This means employees should refer to their own employer’s scheme documents to understand the arrangements available to them.
How does SmartSave help employees manage their retirement savings?
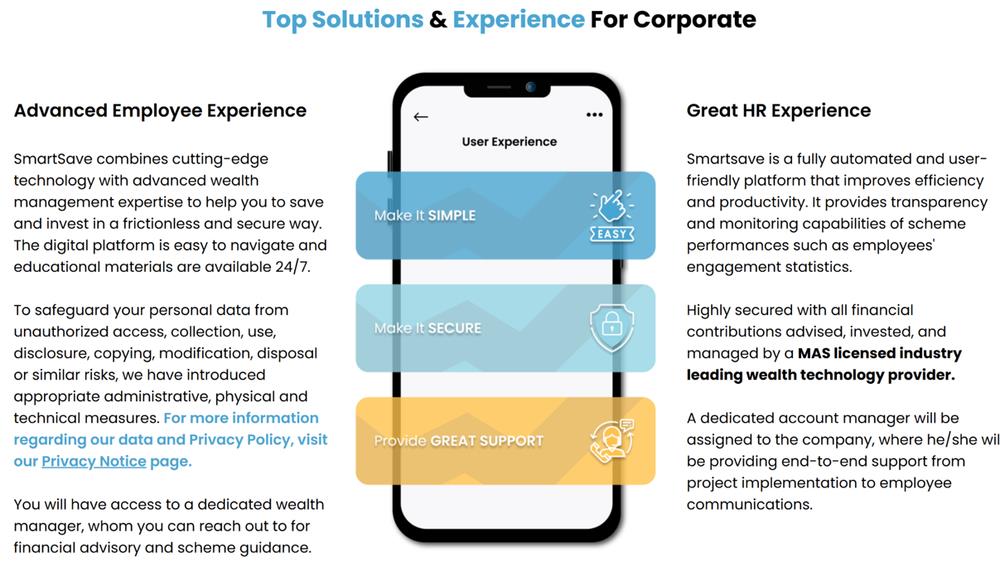
For employees, SmartSave brings investment tools, portfolio information, and access to guidance into one platform.
Here are the main features I would look at when considering it for retirement planning.
#1 – Goal-setting and portfolio recommendations
SmartSave allows employees to set financial goals through its digital platform.
The process described in AutoWealth’s materials includes completing a risk assessment and receiving a portfolio recommendation based on the employee’s risk profile.
This provides a starting point for employees who prefer guidance on their investment allocation rather than selecting individual investments themselves.
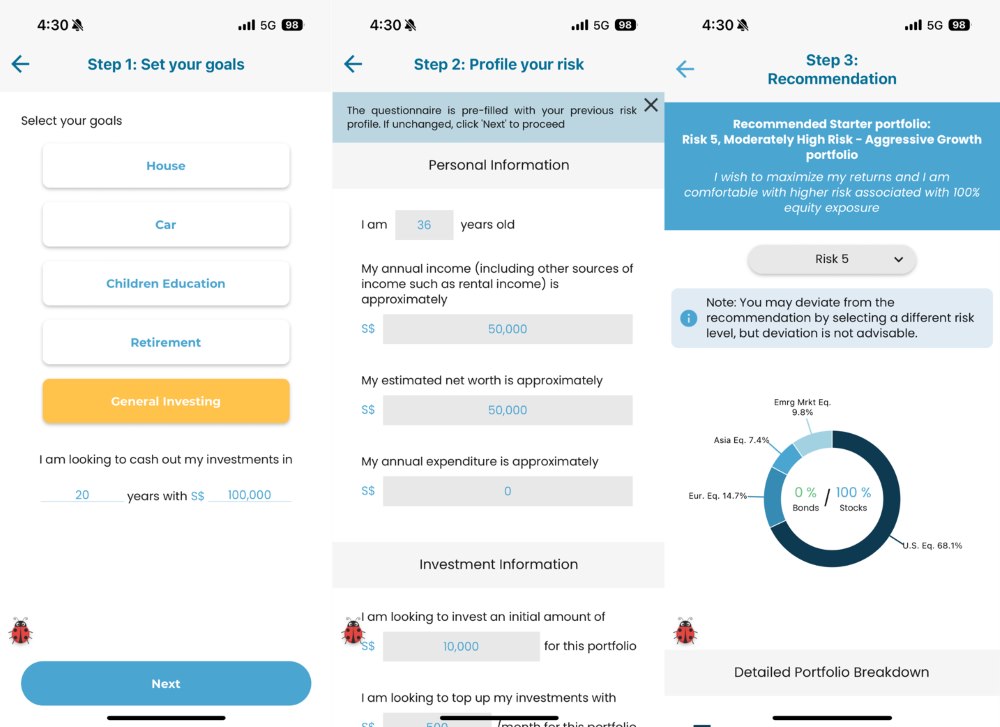
For me, the important consideration is whether the portfolio matches both the goal and the time available to work towards it.
Money intended for retirement many years away may have a different investment horizon from money needed for a home purchase.
I would consider when I expect to need the money, my other financial commitments, and how much of a decline I could accept.
#2 – Managed investments and portfolio rebalancing
SmartSave provides a managed investment service with globally diversified investments.
Diversification spreads exposure across investments and markets, reducing reliance on any single holding. However, the portfolio’s actual risk still depends on what it holds and the allocation to different assets.
AutoWealth also manages the portfolio over time, including rebalancing when needed.
For example, when market movements cause the allocation to drift from its target, rebalancing adjusts the holdings towards the intended mix.
The practical benefit is that employees do not need to select and manage each investment or calculate portfolio adjustments themselves.
The trade-off is delegating those decisions to the investment manager and paying any applicable fees.
#3 – Access to a dedicated wealth manager
SmartSave users have access to an assigned wealth manager for financial advice and guidance on the scheme.
This gives employees a point of contact when they want to understand the investment approach or discuss their financial circumstances.
For someone new to investing, that support may help explain how the portfolio works and why its value changes over time.
I would also use these discussions to understand whether changes in my circumstances, such as a planned home purchase or approaching retirement, warrant a review of my investment plan.
#4 – Financial education and portfolio information
SmartSave provides educational materials through its digital platform.
Employees can also access reports covering transactions, fees, and investment performance.
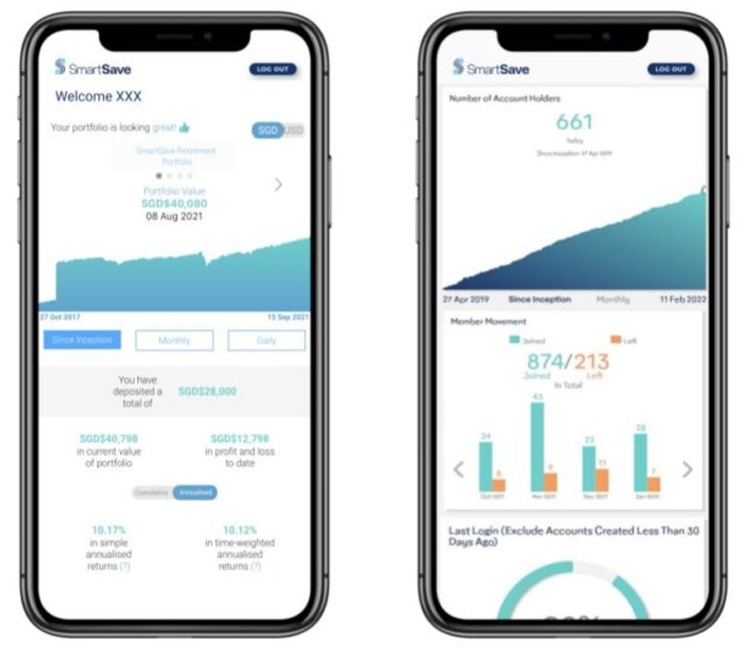
This allows employees to monitor their investments even though the portfolio is professionally managed.
I would use this information to understand how much I have contributed, the fees incurred, and whether the portfolio continues to match my goals.
When reviewing performance, I would consider the investment horizon and level of risk taken, rather than judge the portfolio solely on short-term returns.
How can employers offer a retirement savings scheme through SmartSave?
SmartSave includes services to help employers establish and administer a workplace savings and investment scheme.
AutoWealth can customise the investment plans and platform according to the organisation’s requirements, with support for scheme design, administration and employee communications.
A dedicated account manager supports the employer through implementation and ongoing management.
Reporting tools provide information on employee engagement, activity and trends, helping HR teams assess how the scheme is being used.
For employers, the decision would involve considering the objectives of the programme, its costs, the administrative arrangements and the support employees will receive.
For employees, the relevant outcome is what their own scheme provides and the conditions attached to participation.
How companies use SmartSave for employee retirement planning
AutoWealth states that it administers corporate retirement schemes for companies that include Fortune 100 and Fortune 500 businesses.
This provides an example of how an employer can incorporate investment management and financial guidance into its benefits programme.
Such arrangements may also be relevant to foreign employees who do not receive CPF contributions and need to make separate provisions for retirement.
However, the terms depend on the employer’s scheme. Participation by a large company does not guarantee investment returns or mean that every employee receives the same benefits.
What should employees consider before investing their retirement savings?
The availability of a workplace scheme is a starting point. I would still assess its terms and investments against my own financial needs.
#1 – Understand the contribution and withdrawal rules
I would first check who can participate, how contributions are made, and whether the employer contributes.
If employer contributions are available, I would look at any conditions attached, including whether I need to remain employed for a specified period before becoming entitled to them.
I would also check the withdrawal arrangements and what happens to my investments if I leave the company.
These details can affect how the scheme fits into my financial plans, particularly if I may need the money before retirement.
#2 – Look at the underlying investments and risks
A managed portfolio can still fall in value.
I would want to understand the underlying investments, the mix of assets and any foreign currency exposure.
A portfolio with a larger equity allocation may offer greater long-term growth potential, but can also experience larger market swings. Currency movements may affect returns when measured in Singapore dollars.
Diversification and rebalancing help manage portfolio exposure. They do not guarantee returns or prevent losses.
#3 – Check the total costs
I would review all charges that apply to my employer’s scheme, including management, administration and underlying investment costs where applicable.
I would also check which costs are borne by the employer and which are deducted from my investments.
SmartSave’s corporate arrangements can be customised, so I would use the fee schedule provided for my scheme rather than assume that AutoWealth’s published retail fees apply.
The question is whether the total cost makes sense for the investment management, advice and other services I receive.
#4 – Consider how it fits with my existing savings
A workplace investment scheme would form one part of my overall financial plan.
I would look at it alongside my CPF savings, cash reserves and other investments to understand my combined exposure.
For example, if my existing investments already have substantial equity exposure, I would consider whether the SmartSave portfolio increases that exposure beyond what I am comfortable holding.
I would also keep money for unexpected expenses and near-term commitments accessible, rather than assume an investment portfolio can serve the same purpose as cash savings.
What savings and investment options does AutoWealth offer outside the workplace?
SmartSave is offered through participating employers, but AutoWealth also provides separate retail investment portfolios.
Individual investors can access managed portfolios with risk-based allocations, diversification and ongoing rebalancing without participating in an employer’s scheme.
However, the retail products have their own investments, fees, minimum amounts and account terms. Any benefits offered through an employer’s SmartSave scheme would not automatically apply.
For a closer look at its cash investment offering, read our guide to AutoWealth Starter.
If you are considering investing CPF savings, our guide to AutoWealth’s managed CPF portfolios explains the investments, costs and trade-offs involved.
What would Beansprout do?
I would start by deciding what the money is for and when I expect to need it.
Within Beansprout’s four pots of wealth, money set aside for long-term growth may form part of my Growth Pot.
Before committing that money to investments, I would keep enough in my Liquidity Pot for unexpected expenses and near-term commitments.
If my employer offers SmartSave, I would review the scheme’s contribution rules, fees, withdrawal arrangements and investment options.
The managed portfolios and access to a wealth manager may be relevant if I prefer guidance and do not want to handle investment selection and rebalancing myself.
I would weigh those services against the costs, the investment decisions I would delegate, and the risk of losses.
I would also assess the scheme alongside my existing CPF savings and investments, so that it serves a clear purpose within my overall portfolio.
For employers considering a workplace financial wellness scheme, learn more about SmartSave and enquire with AutoWealth about its corporate arrangements.
For individual investors considering a managed portfolio outside the workplace, explore AutoWealth’s retail offerings here.
Disclaimers and Important Information
Investments always involve risks and the possibility of losses. Any reference to past performance is not necessarily indicative of and is no guarantee to the future or likely performance of your investments. This advertisement has not been reviewed by the Monetary Authority of Singapore.
Read also
Gain financial insights in minutes
Subscribe to our free weekly newsletter for more insights to grow your wealth
Most Popular

Questions and Answers
0 questions