
CICT net property income rose 13.8% in 3Q: Our Quick Take
Stocks
By Gerald Wong, CFA • 29 Oct 2026
Global Wealth Technology Pte. Ltd. is regulated by the Monetary Authority of Singapore (MAS) as a licensed Financial Adviser.

Make Beansprout your preferred source on Google
Add us on Google to see more of our insights in your search results
CapitaLand Integrated Commercial Trust (CICT) reported a 13.8% year-on-year increase in 3Q 2026 net property income (NPI) to S$334.9 million, helped by Paragon’s first quarter of contribution.
CICT 3Q 2026 business updates highlights
CapitaLand Integrated Commercial Trust has released its business update for the third quarter of 2026. Key highlights include:
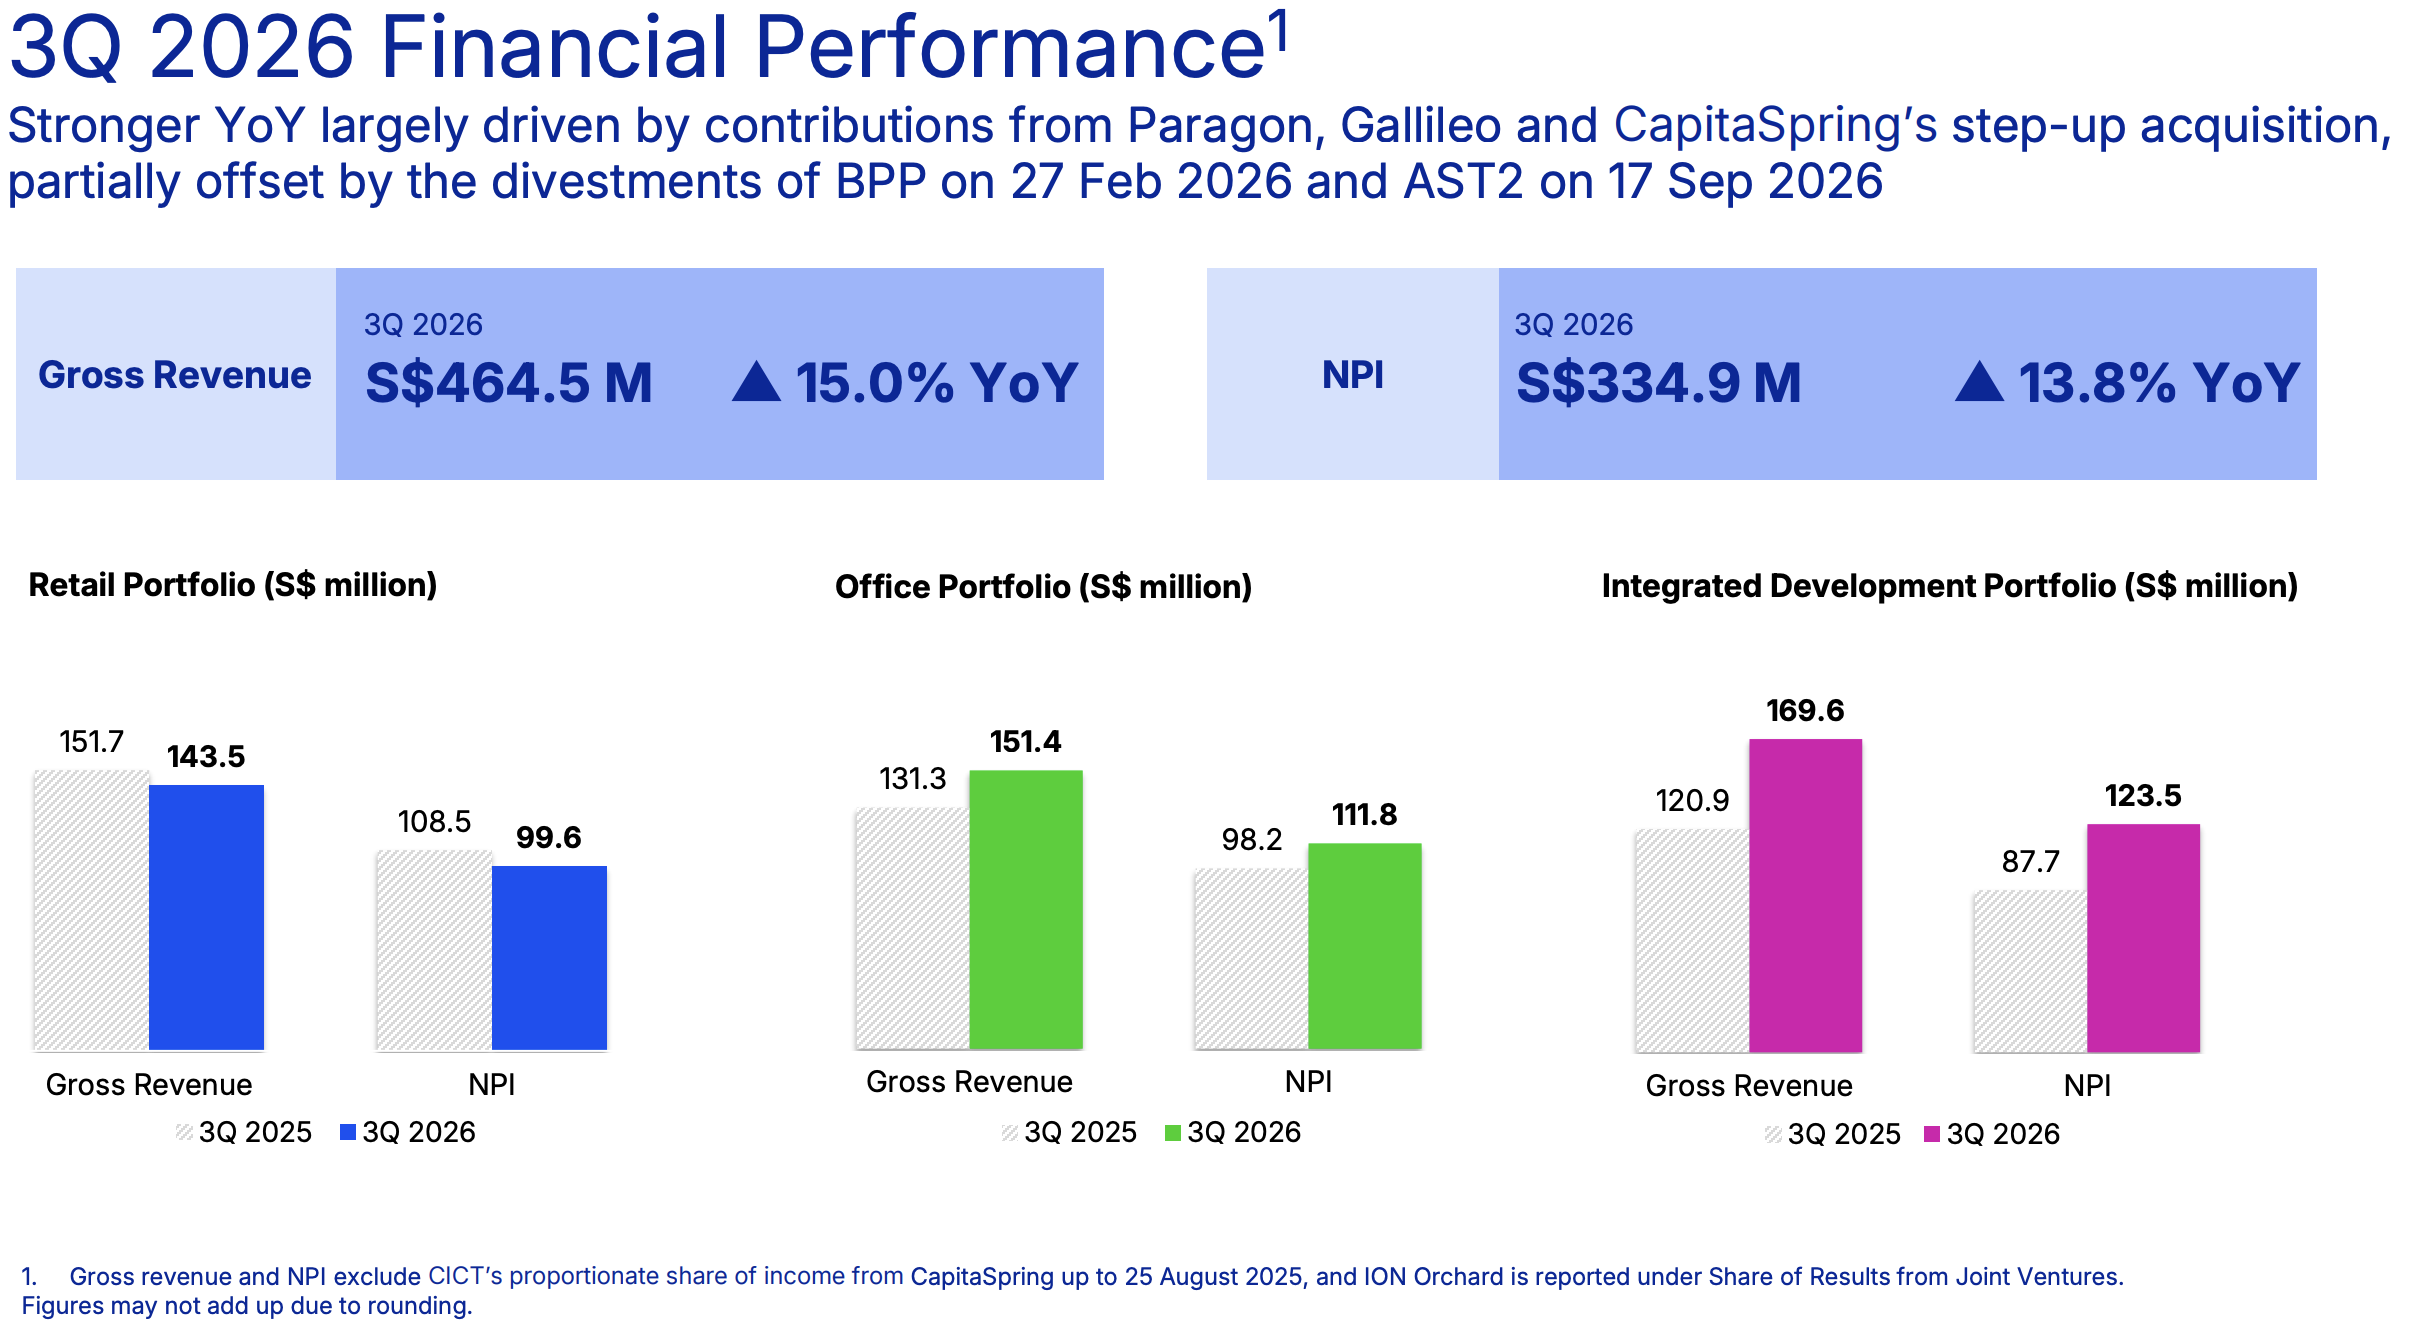
- 3Q 2026 gross revenue: S$464.5 million (+15.0% year-on-year)
- 3Q 2026 NPI: S$334.9 million (+13.8% year-on-year)
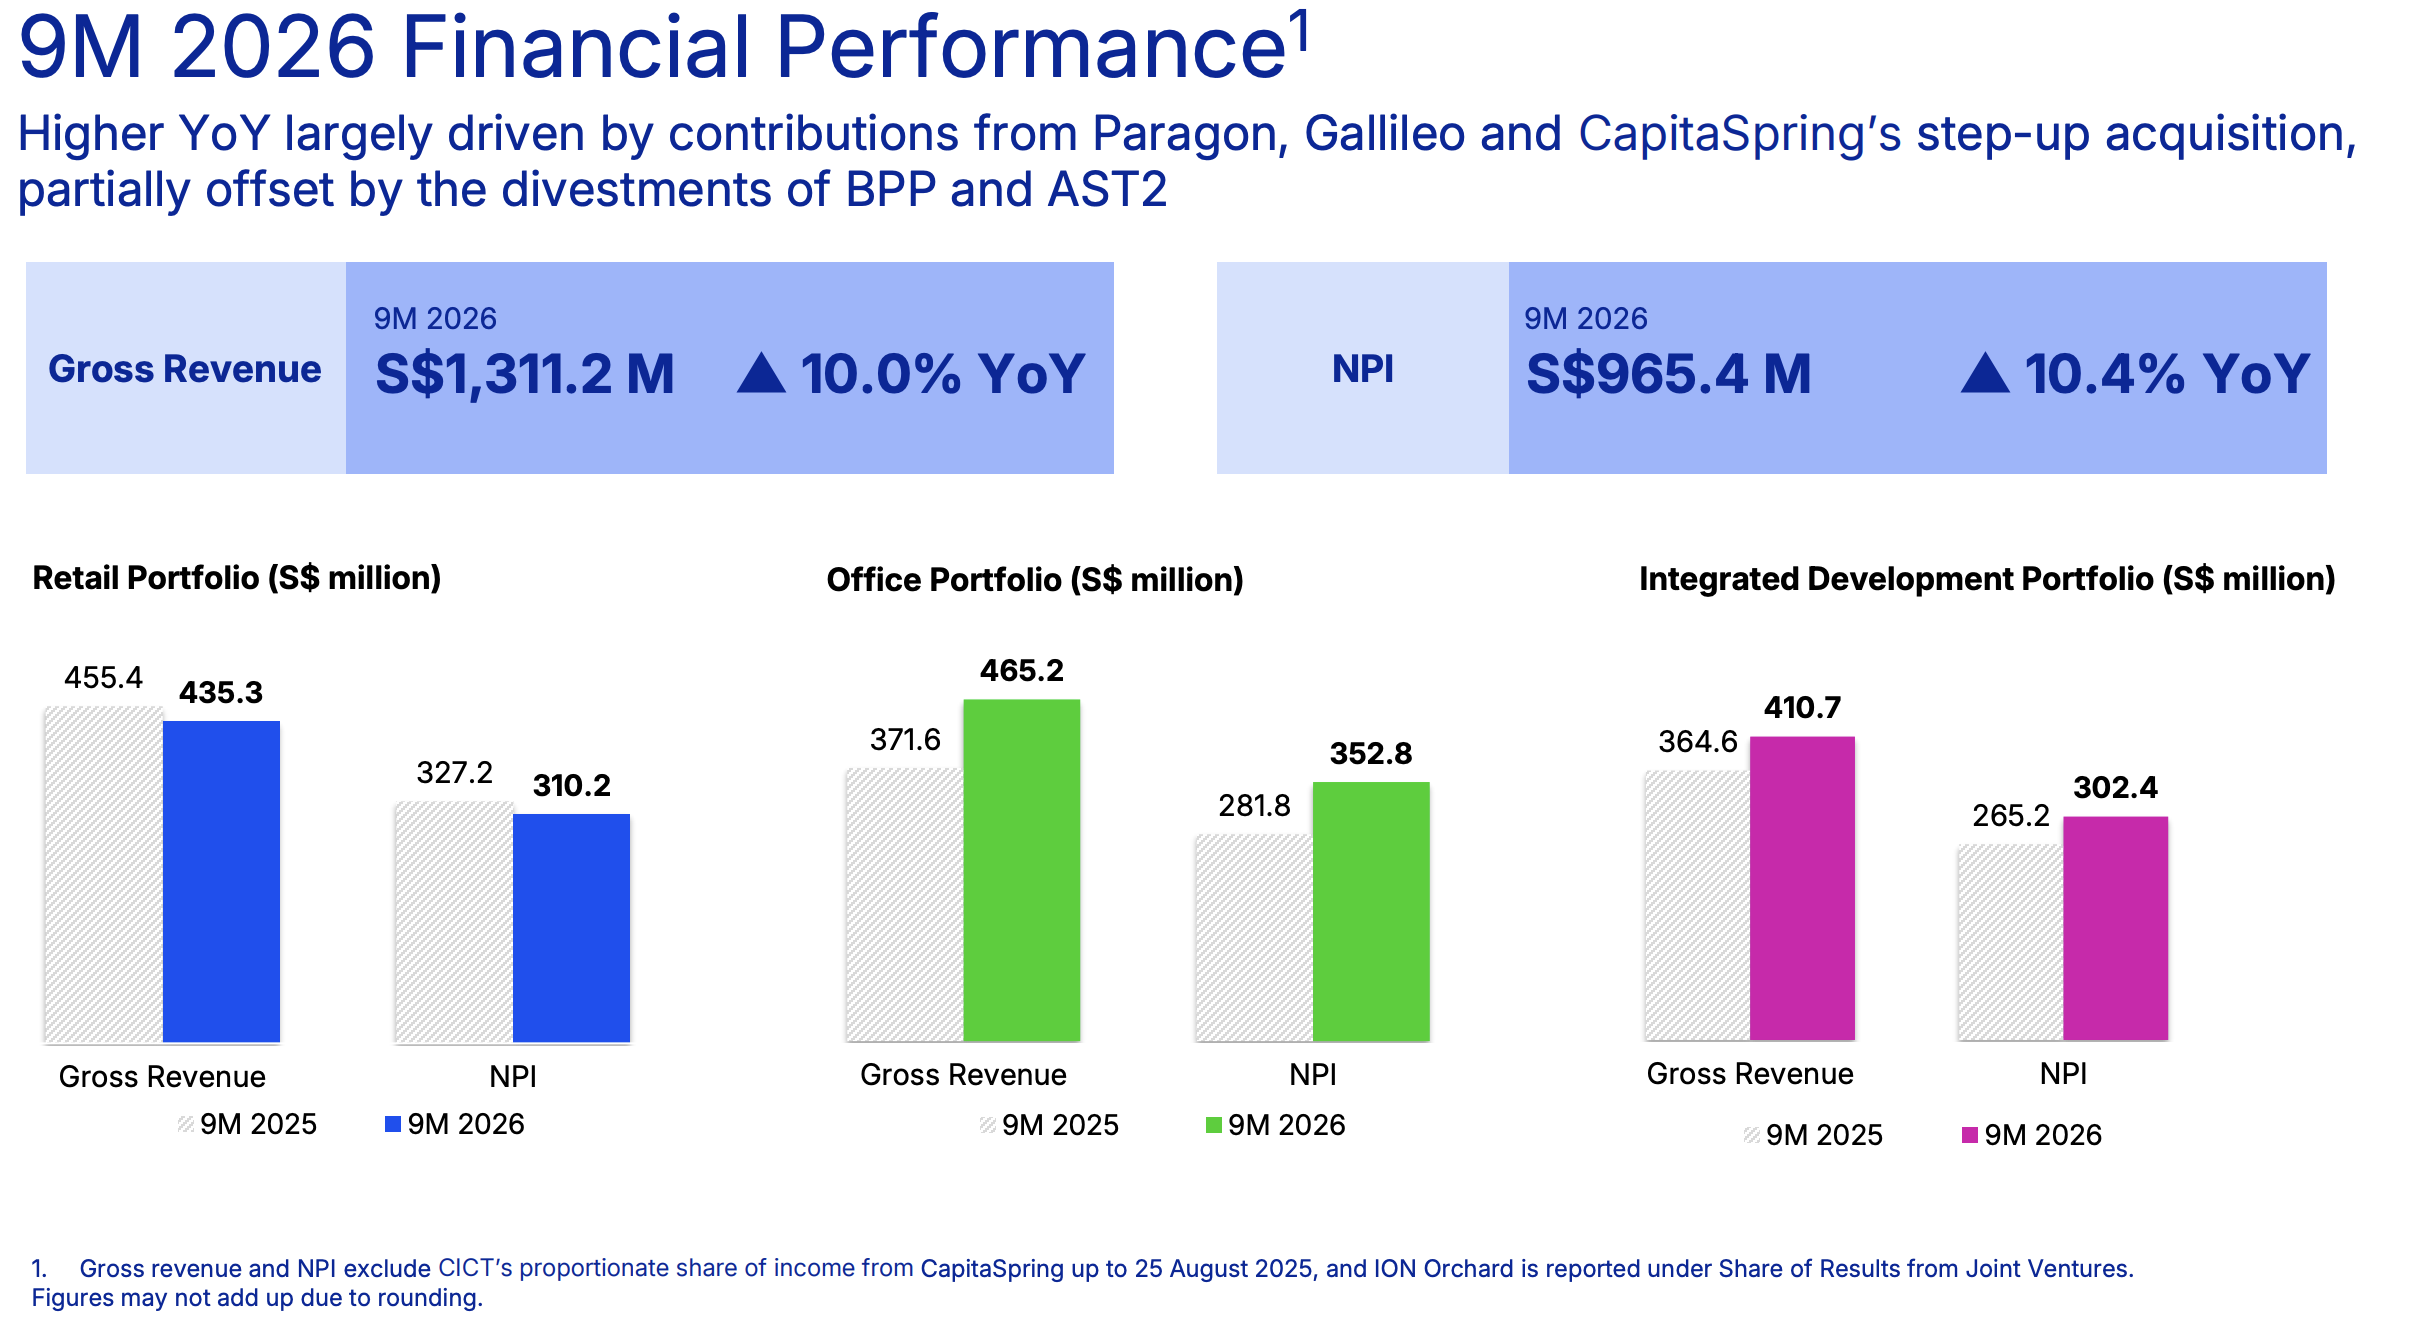
- 9M 2026 gross revenue: S$1,311.2 million (+10.0% year-on-year)
- 9M 2026 NPI: S$965.4 million (+10.4% year-on-year)
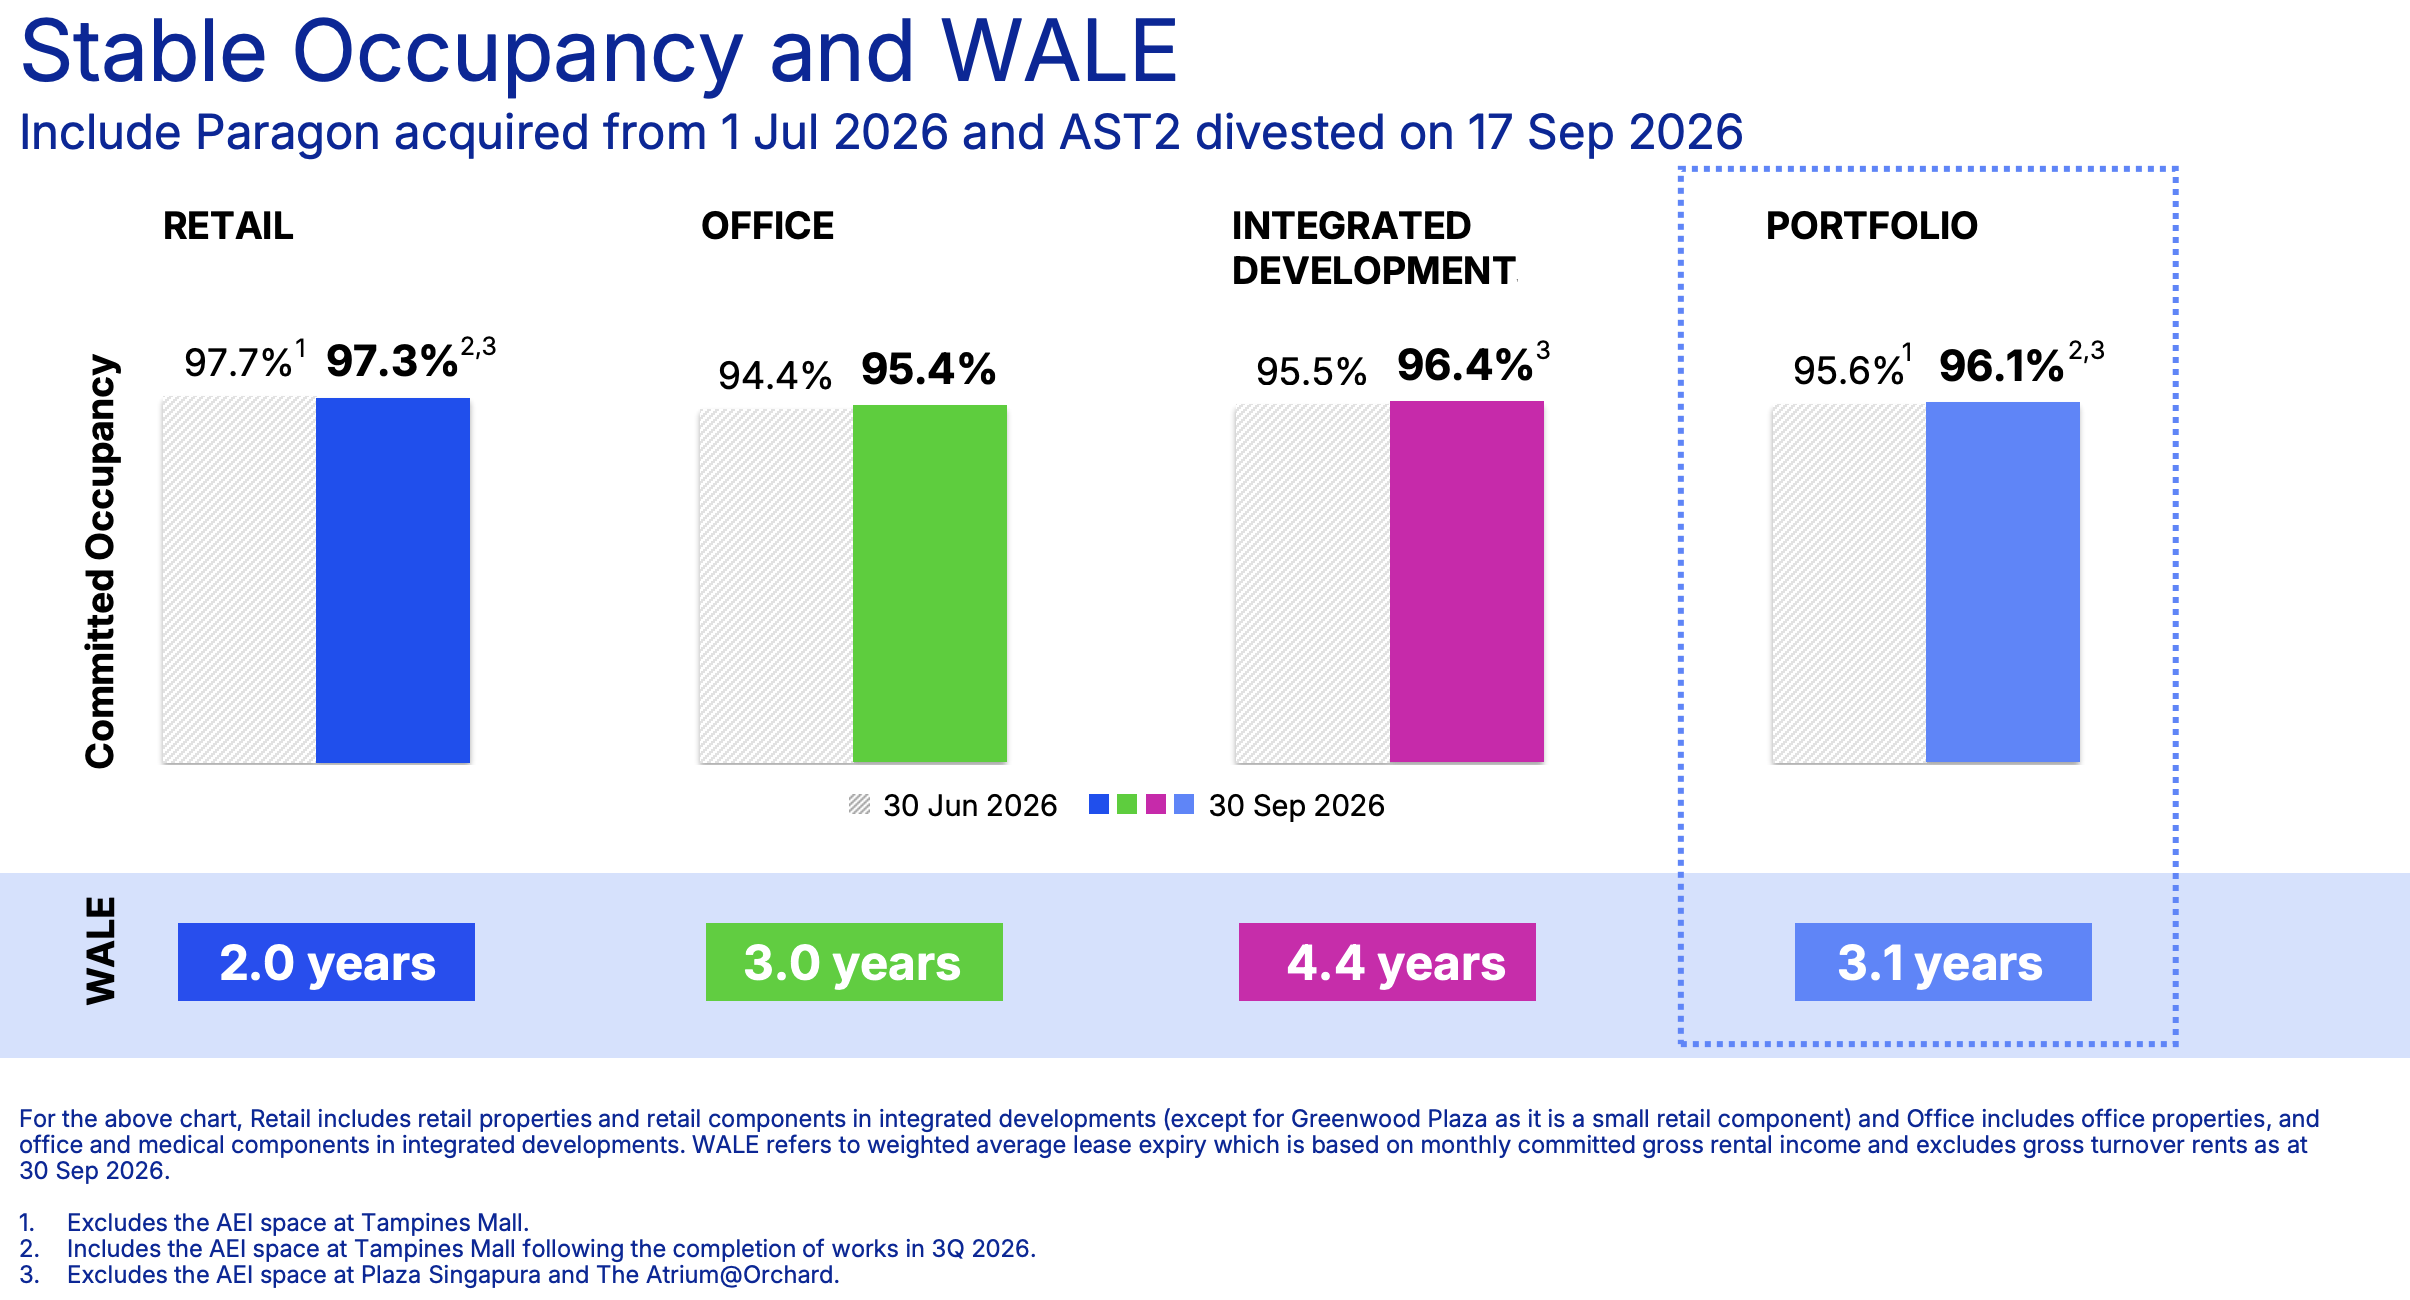
- Portfolio occupancy: 96.1%, up 0.5 percentage points quarter-on-quarter (retail 97.3%, office 95.4%, integrated development 96.4%)
- 9M 2026 rental reversion: +4.6% for retail, +7.1% for office
What we learnt from CapitaLand Integrated Commercial Trust's 3Q 2026 business update
#1 – Paragon, Gallileo and CapitaSpring lifted 3Q NPI by 13.8%
Gross revenue rose 15.0% year-on-year to S$464.5 million in 3Q 2026.
NPI grew 13.8% to S$334.9 million.
The main drivers were Paragon, which CICT acquired on 1 July 2026, contributions from Gallileo in Frankfurt, and the full consolidation of CapitaSpring following the step-up to 100% ownership in August 2025.
This was partly offset by the divestments of Bukit Panjang Plaza in February 2026 and Asia Square Tower 2 on 17 September 2026.
By segment, integrated development NPI jumped to S$123.5 million in 3Q 2026, from S$87.7 million a year earlier.
Office NPI rose to S$111.8 million, from S$98.2 million.
Retail NPI dipped to S$99.6 million, from S$108.5 million, largely reflecting the loss of income from Bukit Panjang Plaza.
For the first nine months of 2026, NPI rose 10.4% year-on-year to S$965.4 million, an acceleration from the 8.7% growth recorded in 1H 2026.
As this is a business update, CICT did not declare a distribution for the quarter. The REIT pays distributions on a half-yearly basis.
#2 – Occupancy improved, led by office
Portfolio occupancy rose to 96.1% as at 30 September 2026, from 95.6% in the previous quarter.
Office occupancy saw the biggest improvement, rising to 95.4% from 94.4%.
Integrated development occupancy also rose to 96.4% from 95.5%.
Retail occupancy eased slightly to 97.3% from 97.7%, as the figure now includes the newly completed AEI space at Tampines Mall. It remains well above URA’s islandwide retail occupancy rate of 93.5%.
Portfolio WALE edged up to 3.1 years, while no single tenant contributed more than 5% of gross rental income.
#3 – Rental reversions improved further
Rental reversions improved across both retail and office.
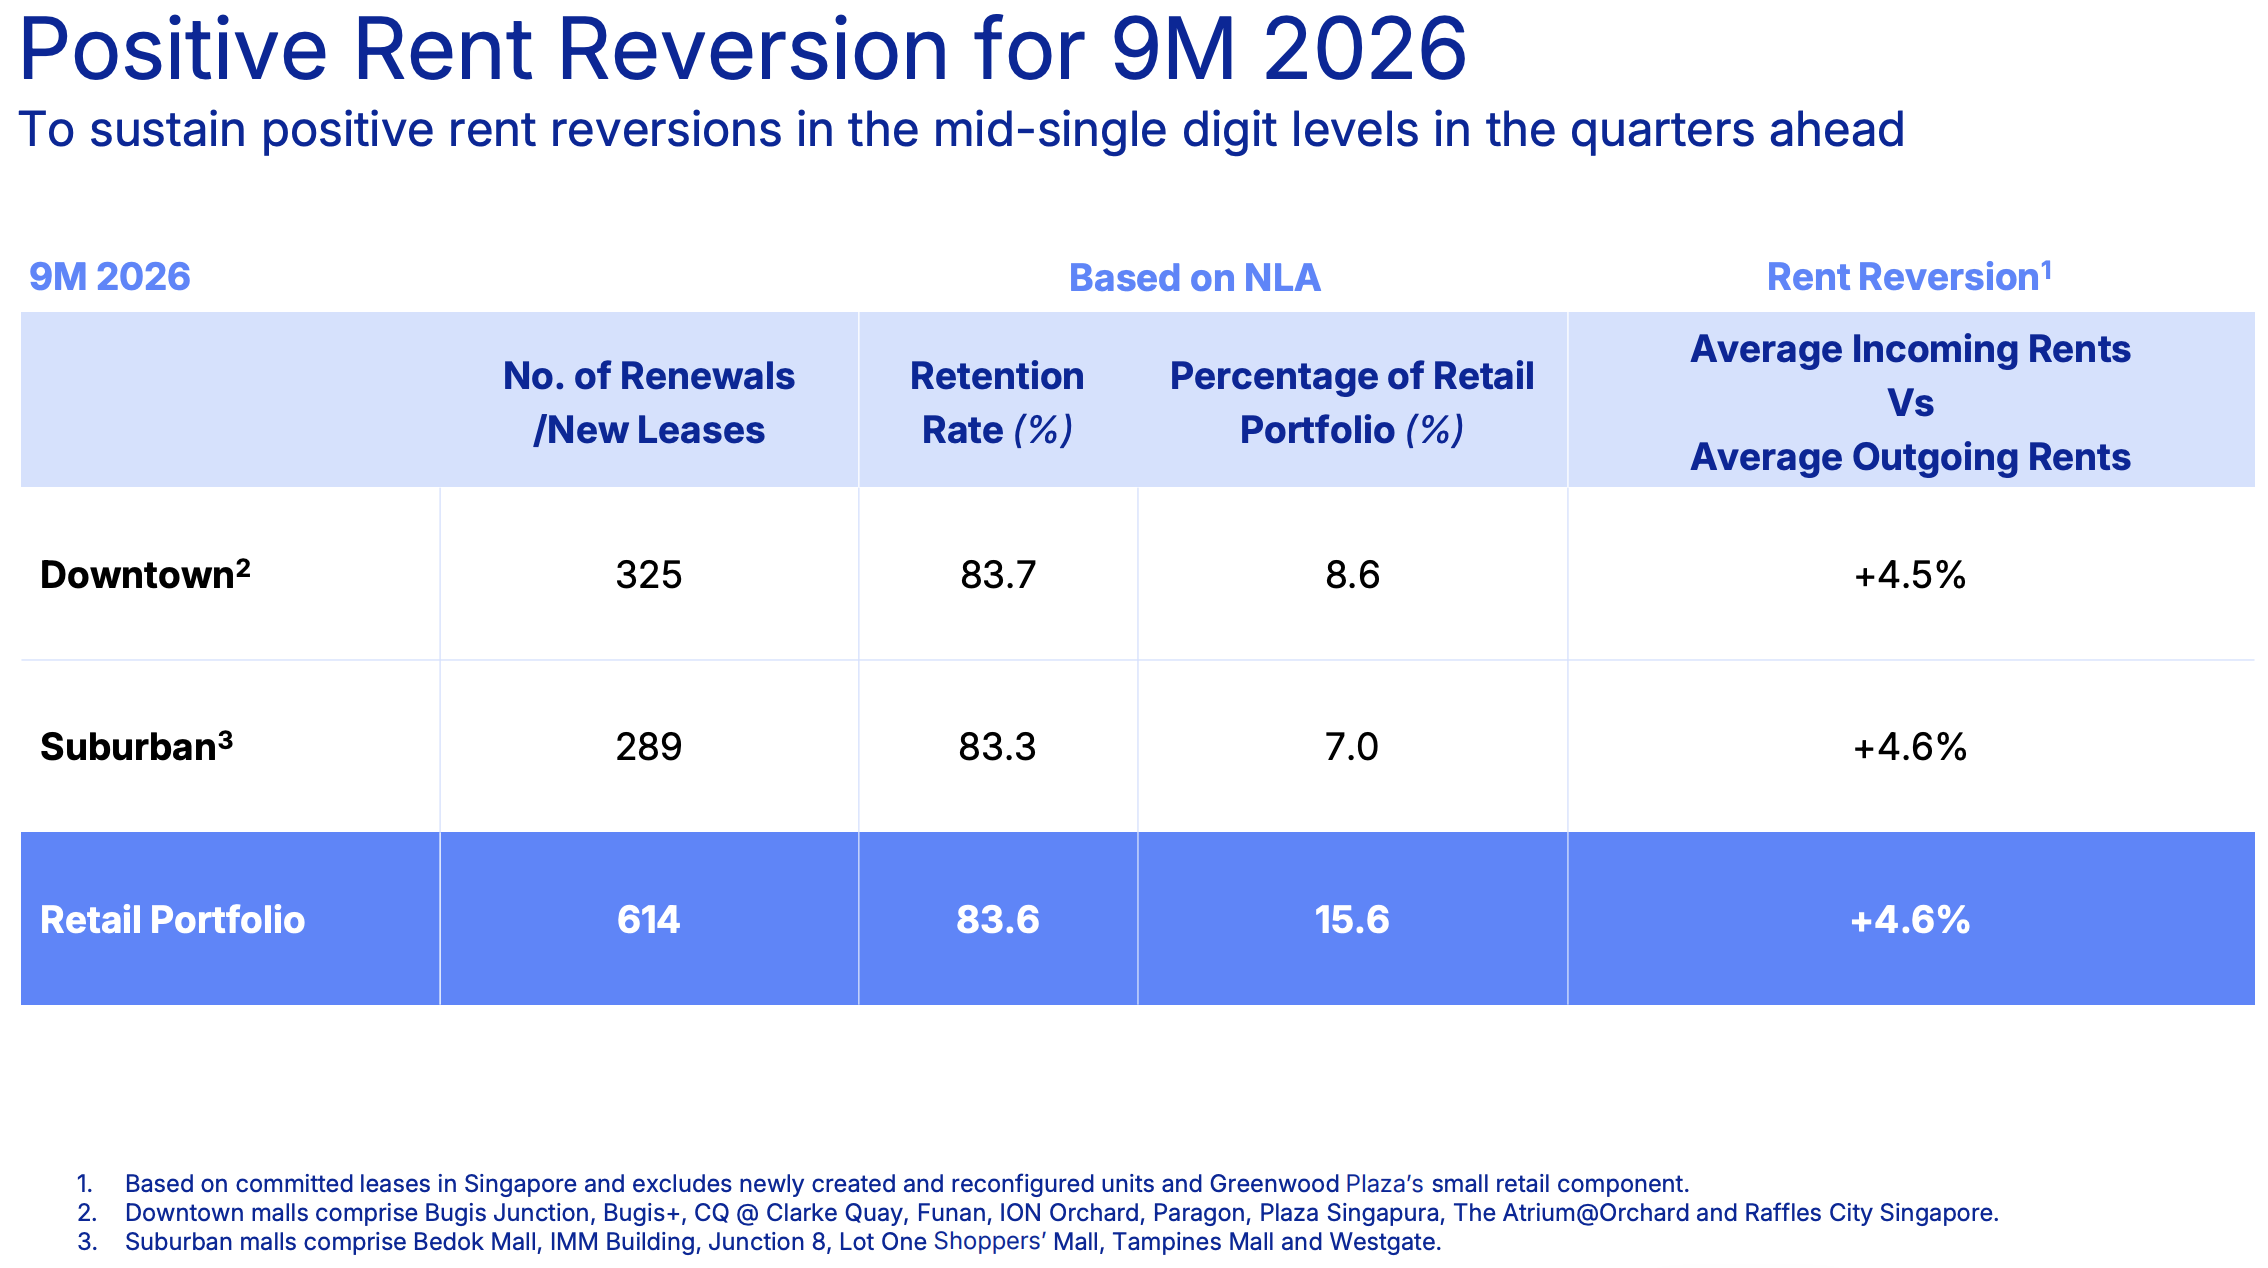
CICT achieved retail rental reversion of 4.6% for 9M 2026, up from 4.0% in 1H 2026.
Downtown and suburban malls recorded similar reversions, at 4.5% and 4.6% respectively.
Office rental reversion rose to 7.1% for 9M 2026, from 6.5% in 1H 2026.
Tenant retention rates stood at 83.6% for retail and 79.1% for office, with the office figure improving from 70.8% in 1H 2026.
Retail tenant sales per square foot rose 2.1% year-on-year for 9M 2026, or 2.0% on a like-for-like basis excluding Paragon. Shopper traffic rose 2.3% year-on-year.
Management expects to sustain positive rental reversions in the mid-single digits for both retail and office in the quarters ahead.
#4 – Gearing rose while cost of debt eased
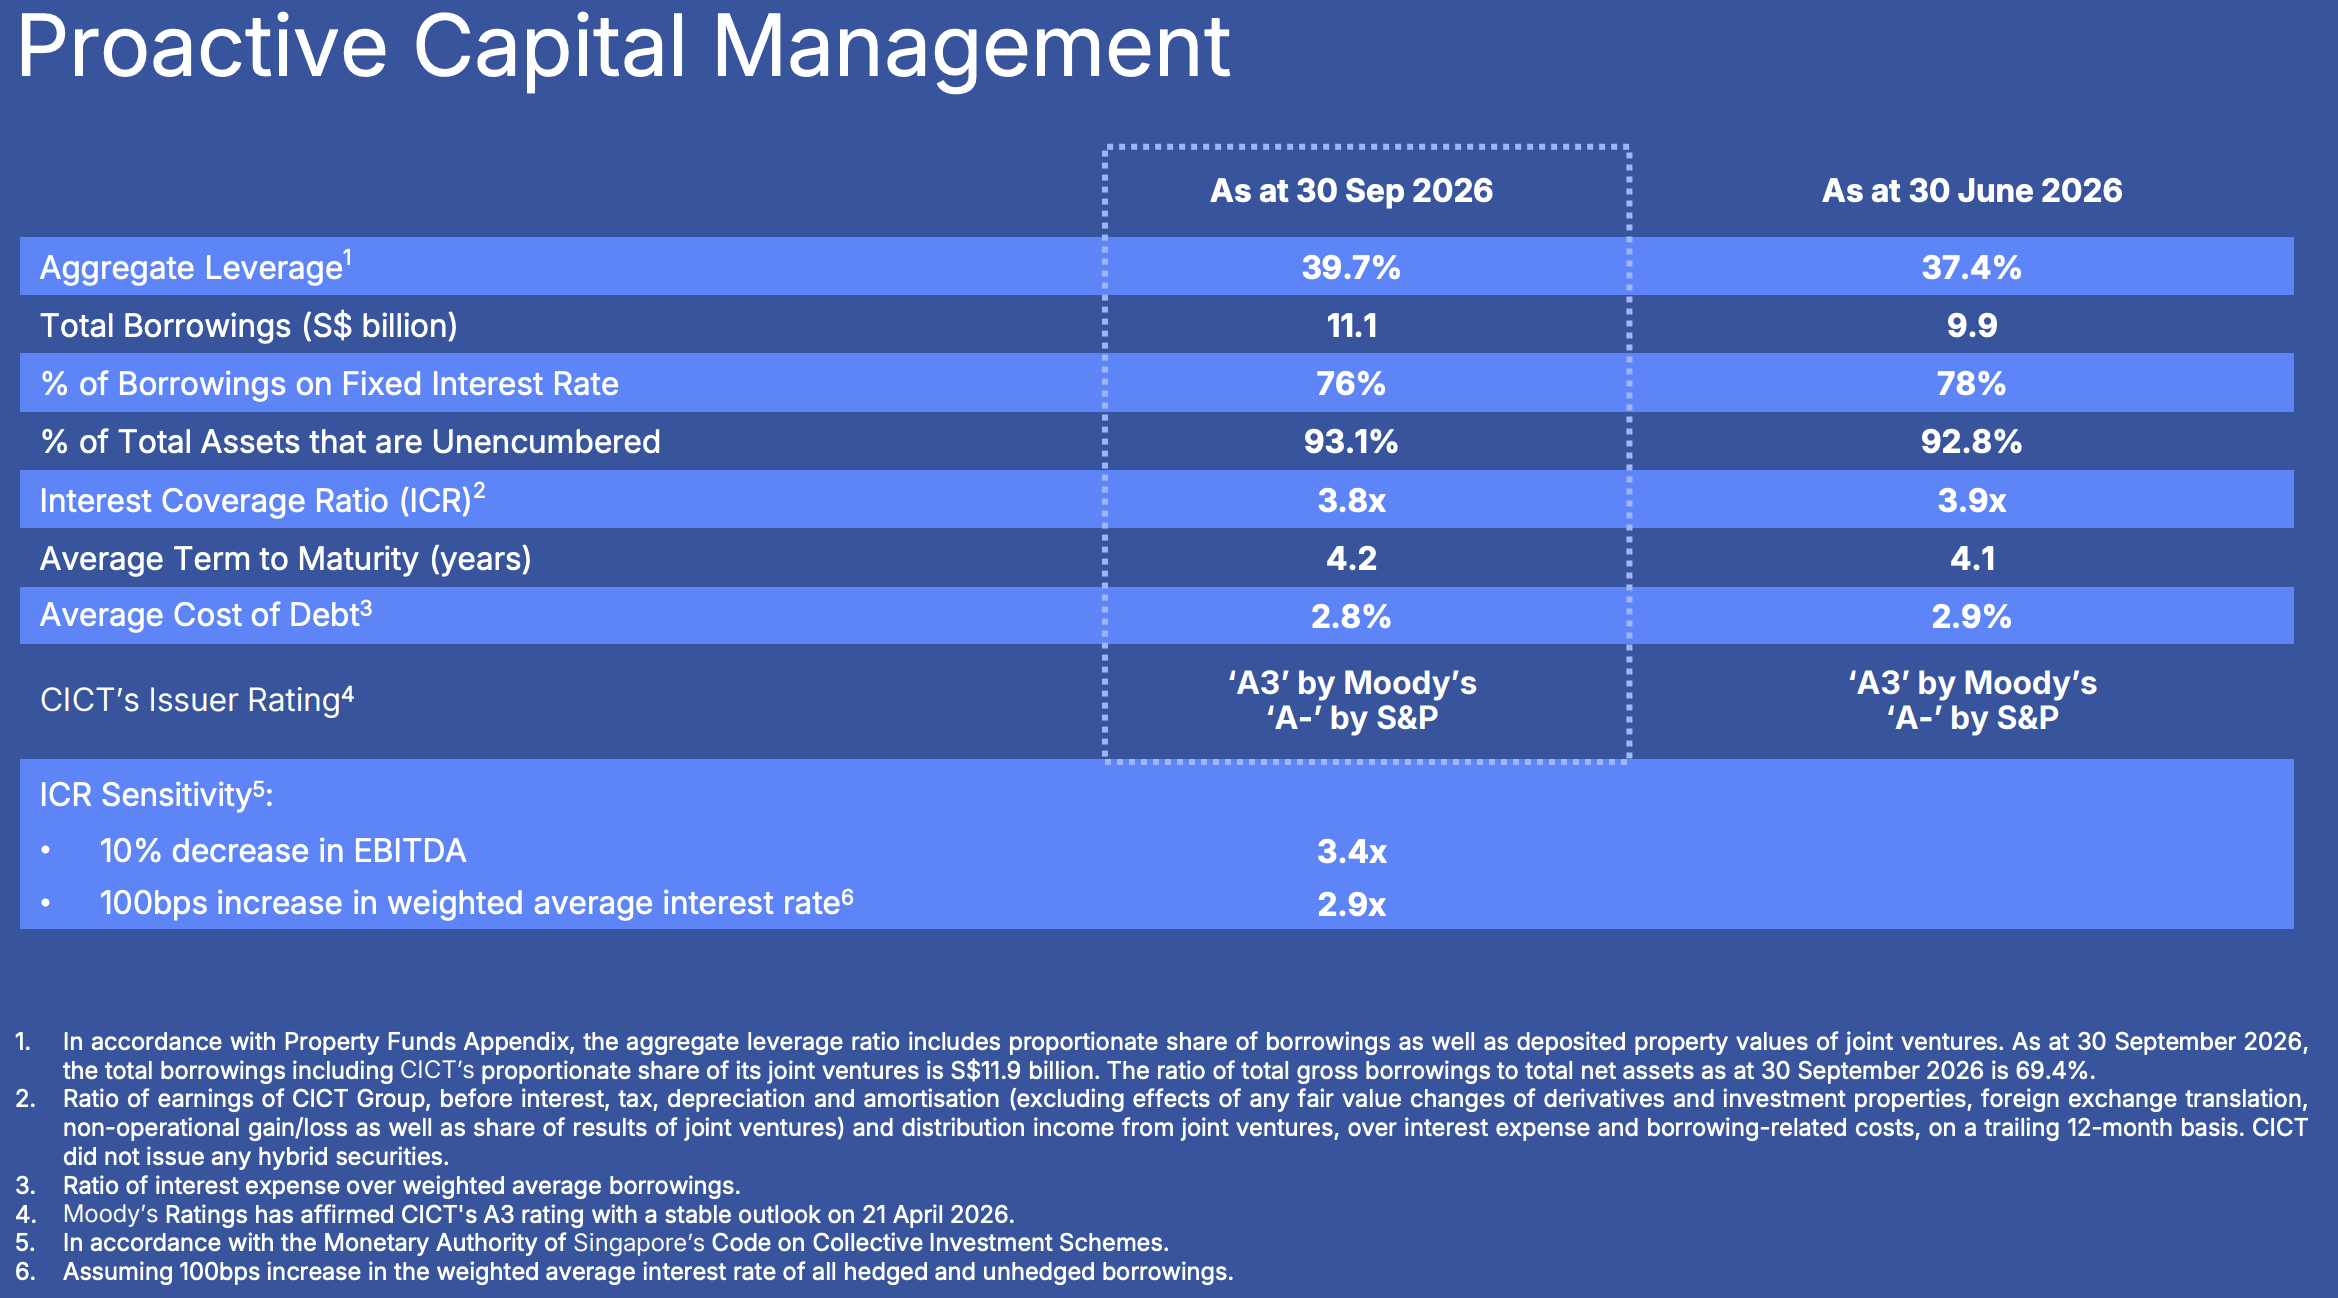
Aggregate leverage rose to 39.7% as at 30 September 2026, from 37.4% in the previous quarter.
Total borrowings increased to S$11.1 billion from S$9.9 billion, after CICT completed the S$3.9 billion Paragon acquisition on 1 July 2026.
The average cost of debt eased to 2.8% from 2.9%.
In September, CICT issued S$400 million of fixed-rate green notes due 2031 at 2.646%.
About 76% of borrowings were on fixed rates, within management’s target range of 70% to 80%.
Interest coverage stood at 3.8 times, while the average debt maturity lengthened slightly to 4.2 years.
CICT’s issuer ratings were maintained at A3 by Moody’s and A- by S&P.
Based on management’s sensitivity analysis, a 1 percentage point increase in interest rates would reduce DPU by an estimated 0.33 cents.
#5 – Asia Square Tower 2 divestment completed, Tampines Mall AEI done
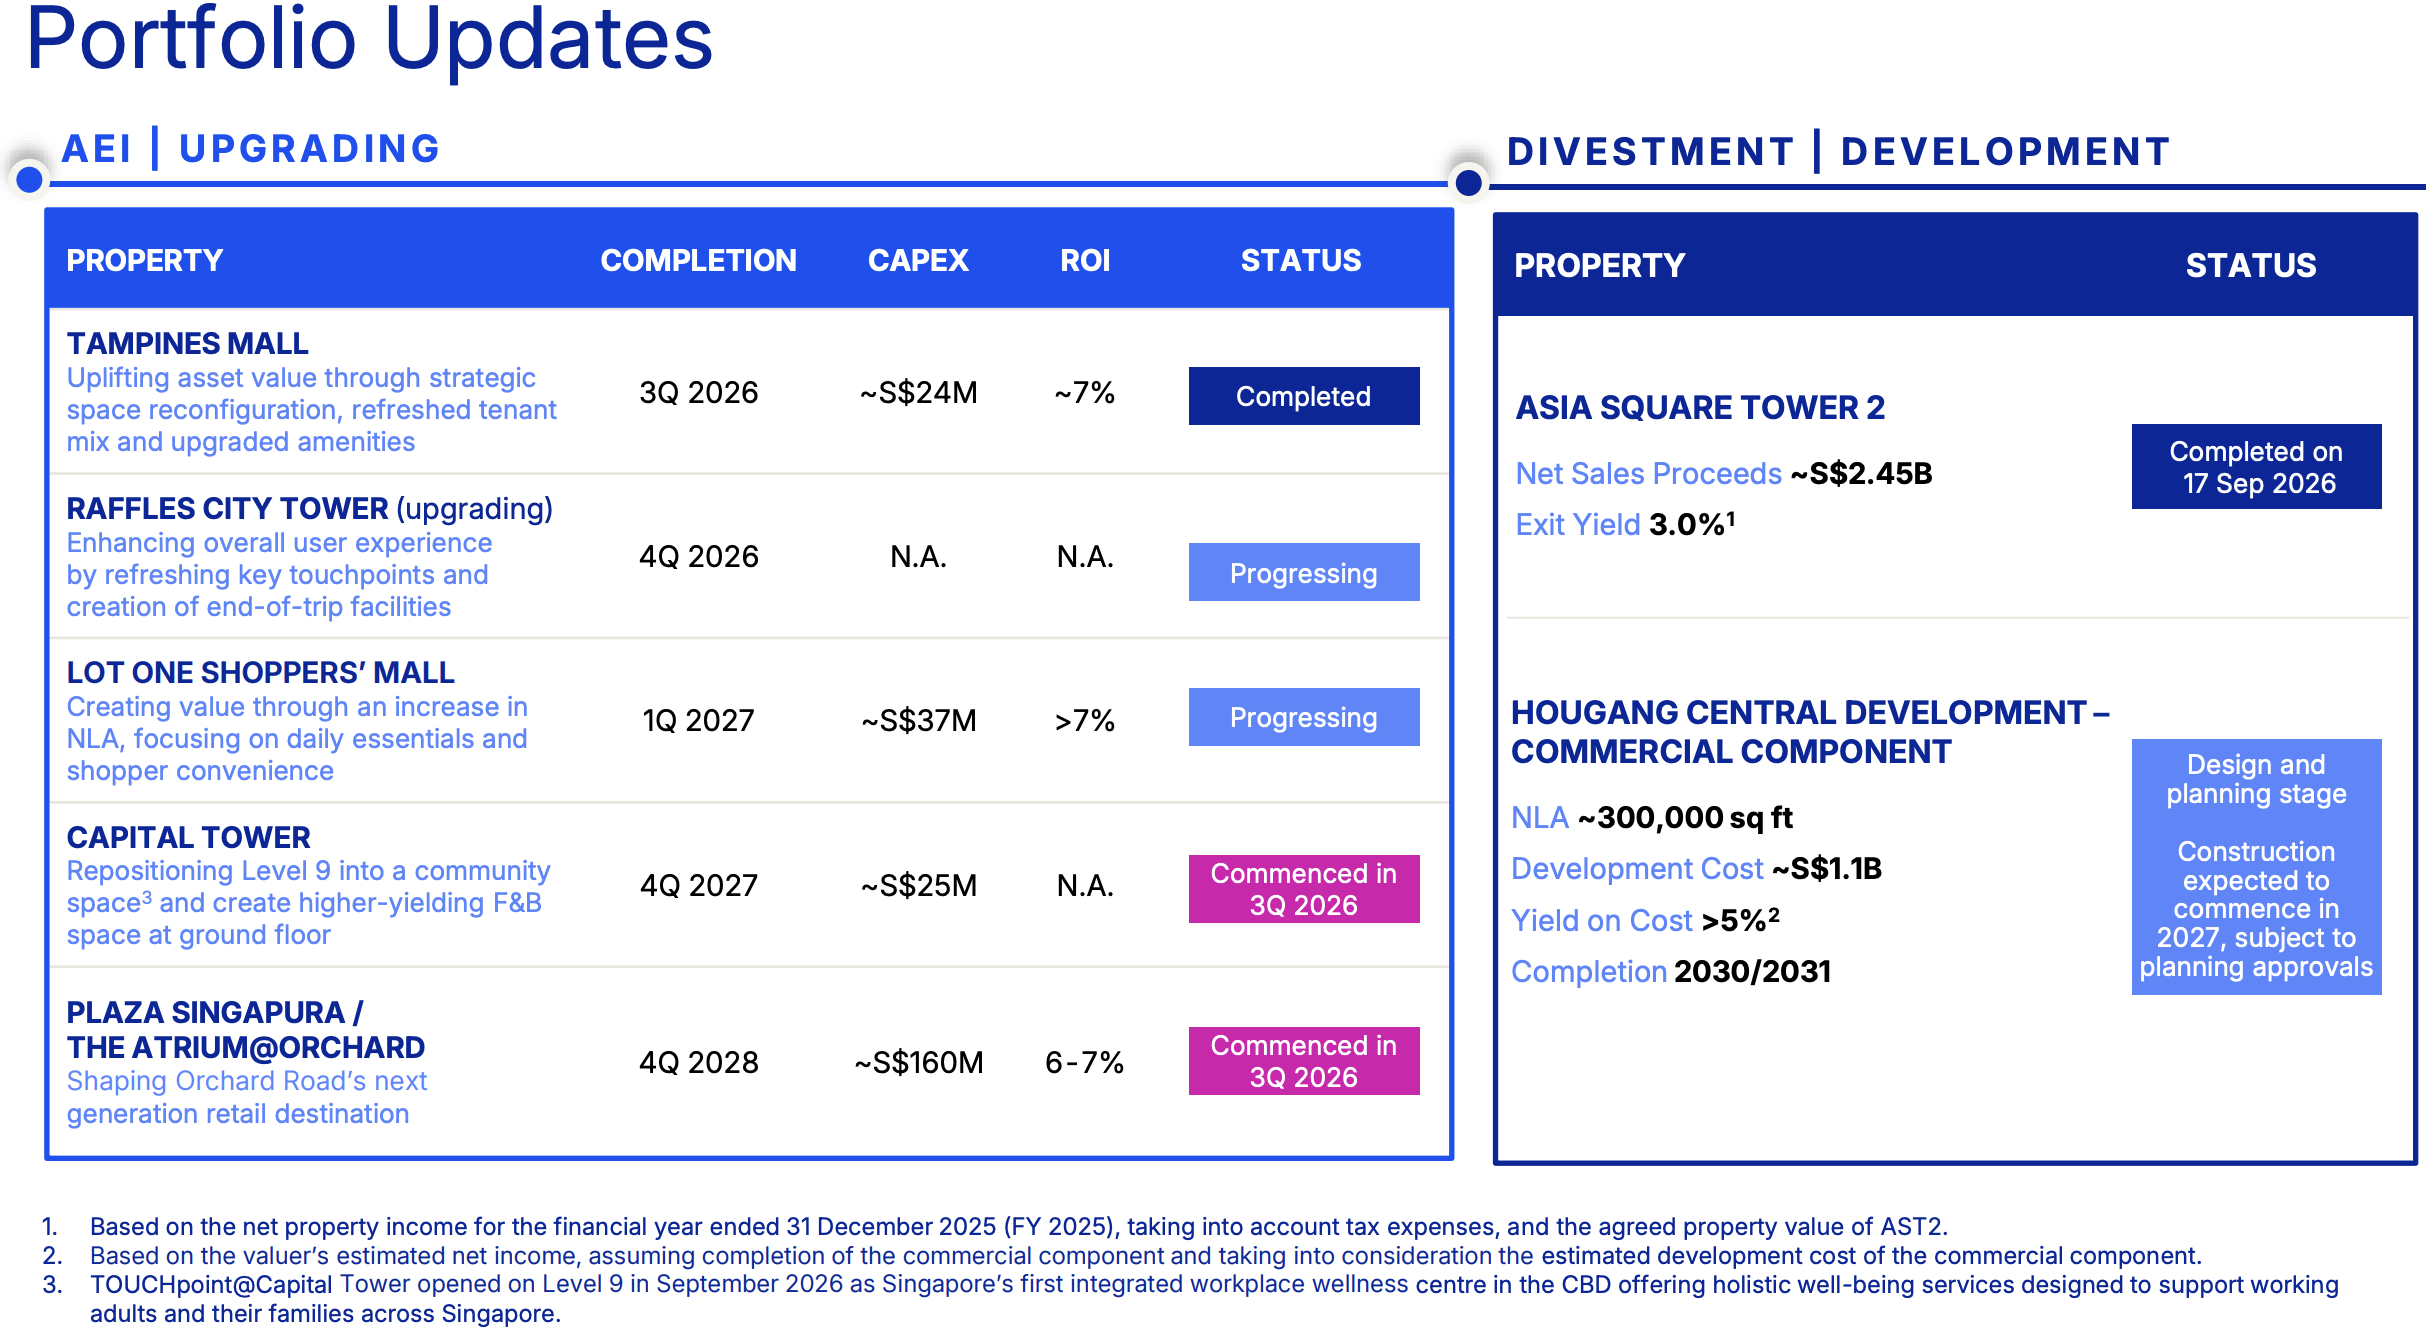
CICT completed the divestment of Asia Square Tower 2 on 17 September 2026, with net sale proceeds of around S$2.45 billion at an exit yield of 3.0%.
The Tampines Mall asset enhancement initiative was completed in 3Q 2026. The S$24 million project is expected to deliver a return on investment of around 7%, with about 97% of the AEI space committed or in advanced negotiation.
Works at Plaza Singapura and The Atrium@Orchard commenced in 3Q 2026. The S$160 million project is targeted for completion in 4Q 2028, with an expected return on investment of 6% to 7%.
Other AEIs in progress include Raffles City Tower (4Q 2026), Lot One Shoppers’ Mall (1Q 2027) and Capital Tower (4Q 2027).
Development of the commercial component at Hougang Central also commenced in 3Q 2026. The project has an estimated development cost of about S$1.1 billion, a yield on cost above 5%, and is expected to complete in 2030 or 2031.
Beansprout’s quick take on CICT earnings
CapitaLand Integrated Commercial Trust delivered a solid 3Q 2026 business update.
NPI rose 13.8% year-on-year, with Paragon’s first quarter of contribution adding to the earlier boost from CapitaSpring and Gallileo.
Operating metrics also improved from the previous quarter. Portfolio occupancy rose to 96.1%, led by a one-percentage-point increase in office occupancy, and rental reversions strengthened to 4.6% for retail and 7.1% for office.
The key area to monitor is the balance sheet. Aggregate leverage rose to 39.7% after the Paragon acquisition, though funding costs continued to ease, with the average cost of debt falling to 2.8%.
With the Asia Square Tower 2 divestment now completed, how CICT deploys the roughly S$2.45 billion in proceeds, whether to pare down debt or recycle into higher-yielding opportunities, will be an important driver of DPU growth from here.
Looking ahead, a full half-year of Paragon contribution and the completed Tampines Mall AEI should support CICT’s 2H 2026 DPU, partly offset by the loss of income from Asia Square Tower 2.
The ramp-up of Paragon’s income contribution should also help CapitaLand Integrated Commercial Trust’s DPU profile in 2H2026 and beyond.
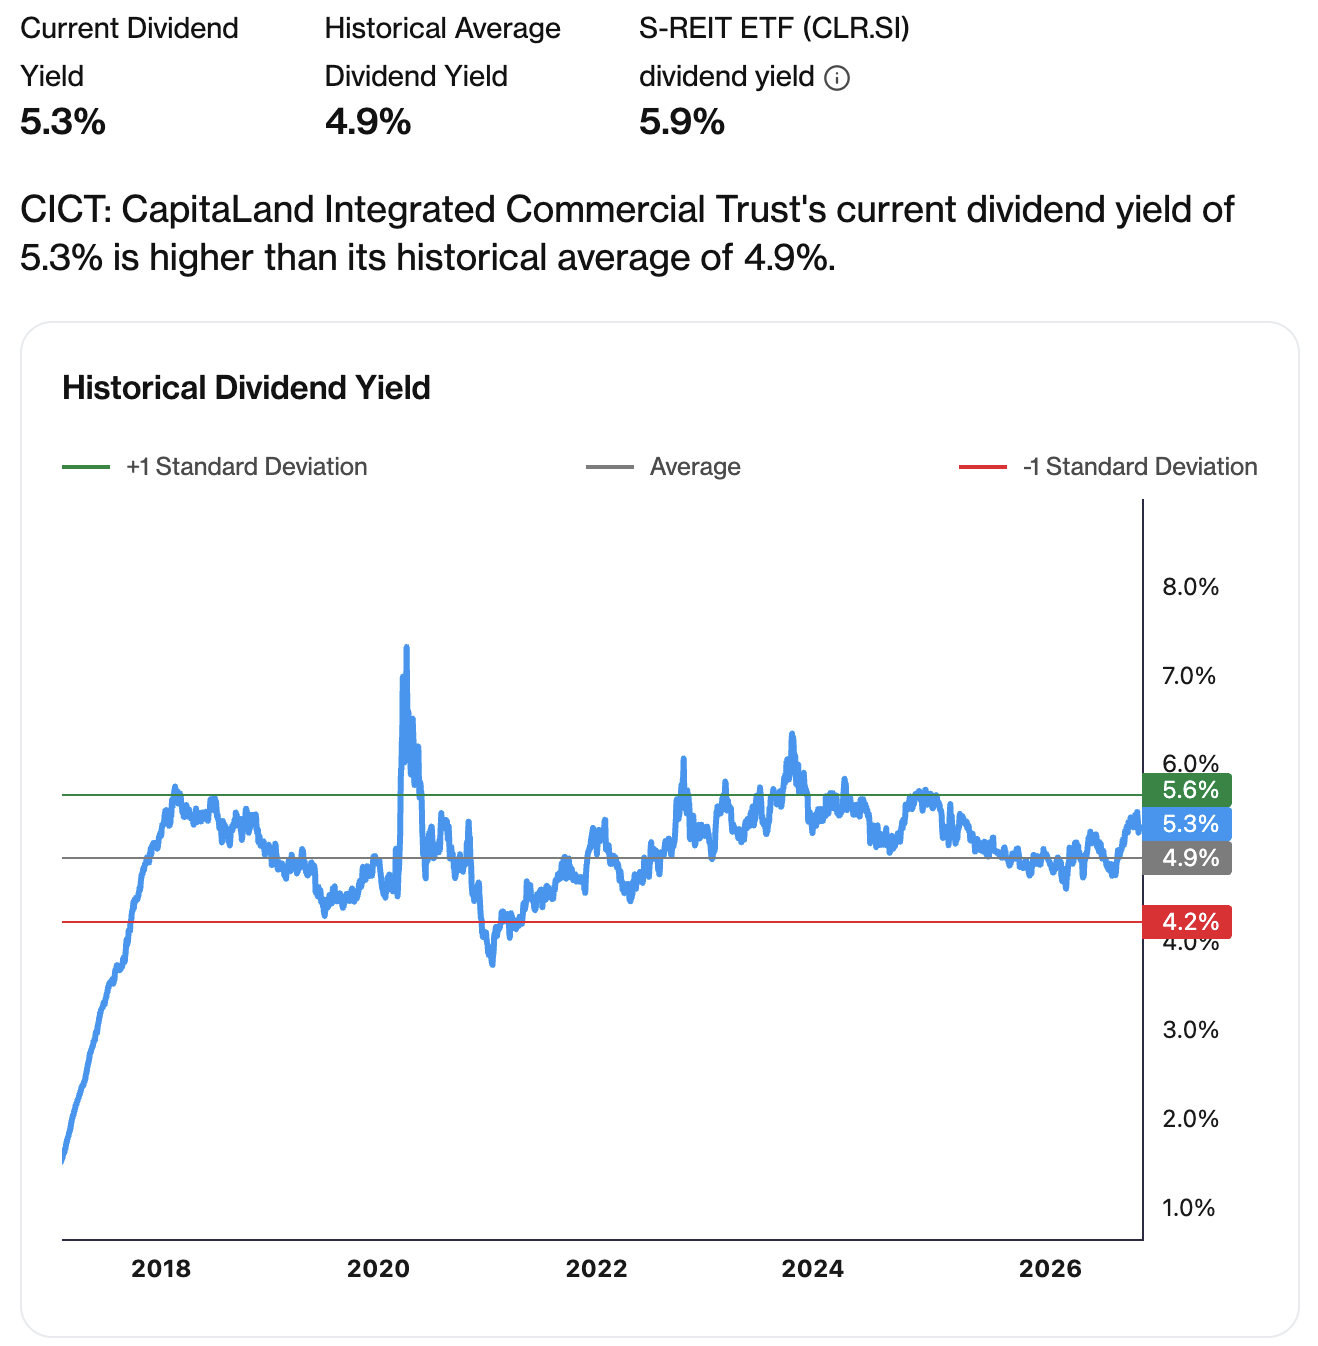
CapitaLand Integrated Commercial Trust is currently trading at 5.3% dividend yield which is higher than its historical average of 4.9%.
Related links:
Check out Beansprout's guide to the best stock trading platforms in Singapore with the latest promotions to invest in CICT.
Enjoyed this insight? Follow Beansprout on Telegram, Youtube, Facebook and Instagram, and add Beansprout as your preferred source on Google so you never miss an update.
Read also
Gain financial insights in minutes
Subscribe to our free weekly newsletter for more insights to grow your wealth
Most Popular

Comments
0 comments