
Can we keep the lifestyle we enjoy today when we retire? This couple decided to find out
CPF & Retirement
Powered by
By Beansprout • 20 Oct 2026
Why trust Beansprout? We’ve been awarded Best Investment Website at the SIAS Investors’ Choice Awards 2025
A newly married couple in their 30s uses the CPF Retirement Payout Planner to see whether the lifestyle they enjoy today can fit alongside their retirement plans.
This post was created in partnership with CPF Board. All views and opinions expressed in this article are Beansprout's objective and professional opinions.
My husband and I got married earlier this year. Between the wedding and renovating our home, our attention has been on these more immediate milestones.
Now that those milestones are almost behind us, we’ve decided to sit down and look at our finances as a couple.
We are both in our mid-30s, and already separate our money for different purposes including emergency savings, travel, investments, and longer-term goals.
Our CPF savings have also continued growing through our regular mandatory contributions.
So for a while, I felt we were doing well with our financial planning.
But then I realised there was something we had never really thought about: What were we doing all of this for? What kind of retirement were we saving towards?
We had never compared what retirement looked like to each of us, or worked out how much income we might want each month.
For me, CPF had also mostly been something I associated with paying for our home and supporting healthcare needs.
I knew it would eventually provide retirement income, but I had never connected the CPF savings I saw in my account with the kind of life I might want decades from now.
That made me curious and a little uneasy about whether we were actually on track, or had simply assumed that we were.
That was what prompted me to try the CPF Retirement Payout Planner.
What would we actually want our retirement to look like?
Before thinking about a retirement number, my husband and I started with a more basic question: Which parts of the life we enjoy today would we still want when we retire?
We would still like to travel, eat out occasionally, and spend on experiences that matter to us. I would also like the flexibility to continue doing work I enjoy, without necessarily having to depend on it for my living expenses.
But “comfortable” meant different things once we started getting into the details.
This was where the retirement payout guide within the planner was useful.
Instead of asking me to come up with a number immediately, it got me to think through different parts of everyday life, including household expenses, healthcare, meals, leisure, and transport.
Some choices were relatively easy.
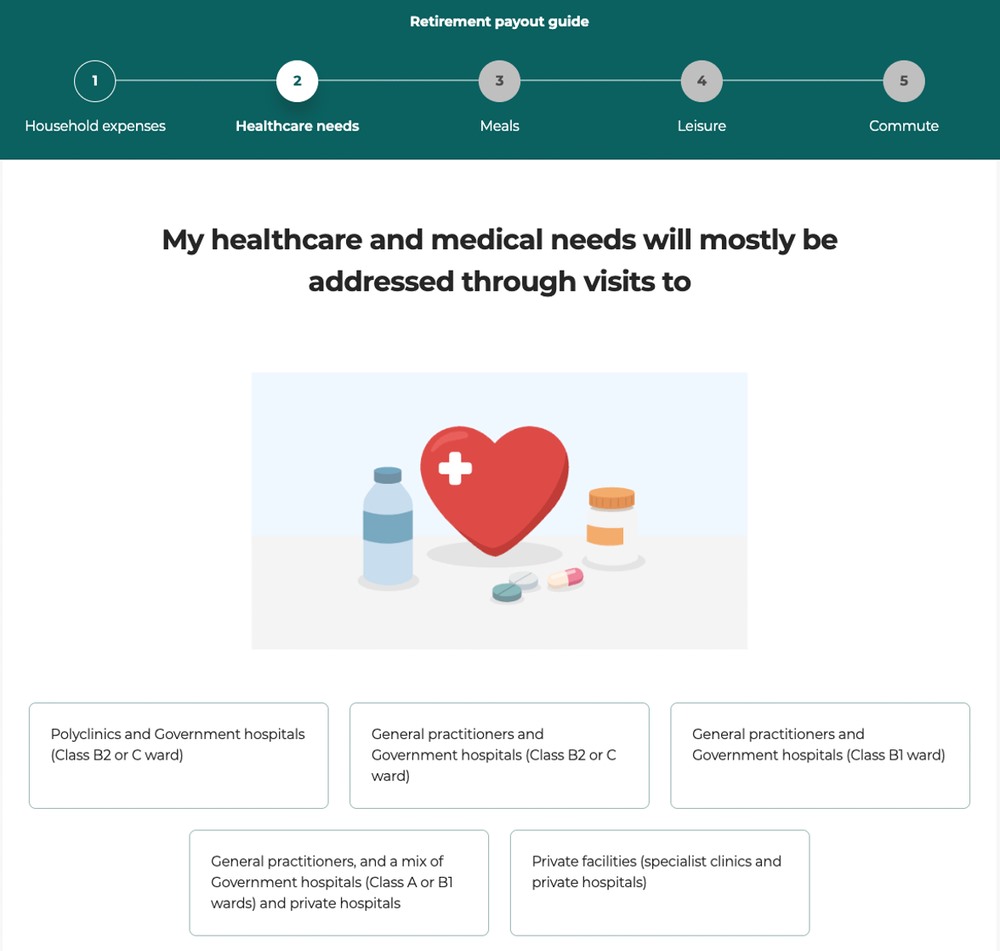
For healthcare, I pictured myself relying mainly on polyclinics and government hospitals. For meals, I could see myself continuing to cook at home while still eating at hawker centres, food courts and cafes occasionally.
Other questions made me think harder.
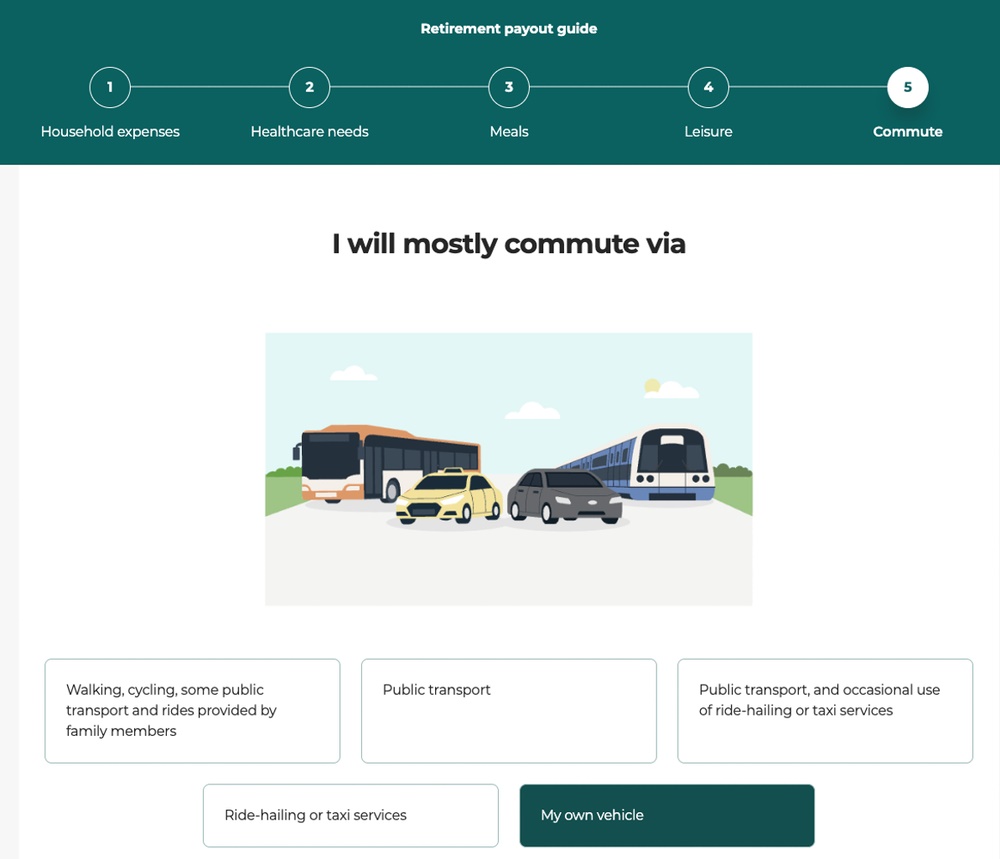
I was surprised that something as ordinary as transport surfaced a difference between us.
My husband would be perfectly comfortable relying on public transport in retirement, while I could still imagine myself driving.
It sounds like a small thing, but it made me realise that even between the two of us, a “comfortable retirement” did not necessarily mean the same thing.
Going through these choices made retirement feel much less abstract.
We were no longer just saying that we wanted to “travel” or “eat out”. I had to think about what those choices might actually look like day-to-day.
Based on what I selected, the guide estimated that my retirement choices could require around S$2,870 to S$3,070 a month in today’s dollars.
These figures are projections based on my current information and the planner’s assumptions, so they may change as my circumstances and CPF balances change.
I used the midpoint of the two figures, S$2,970 a month, as my retirement income goal.
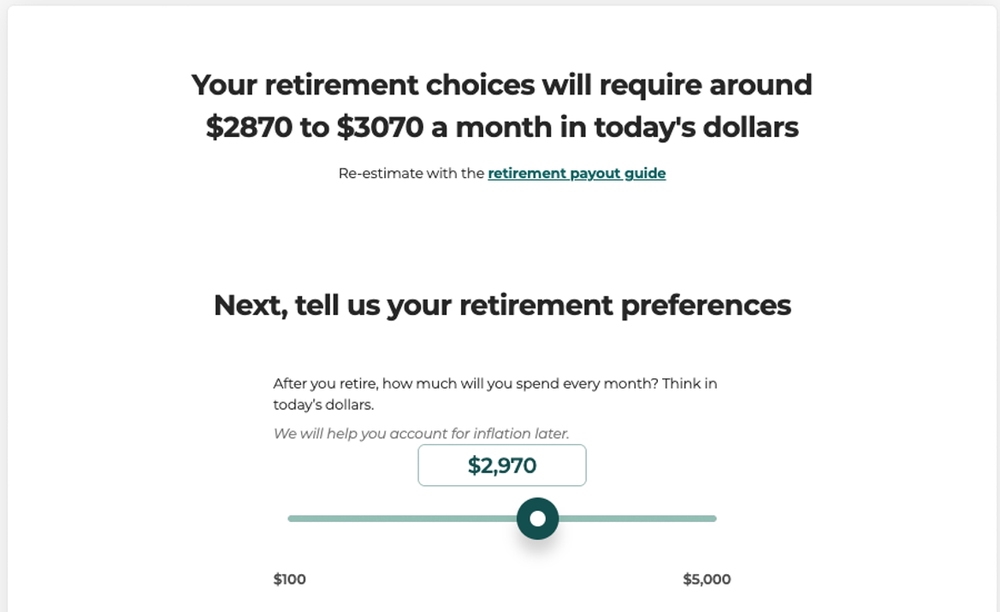
With 2% inflation factored in, maintaining the equivalent of that lifestyle could require around S$5,490 a month by the time I’m 65.
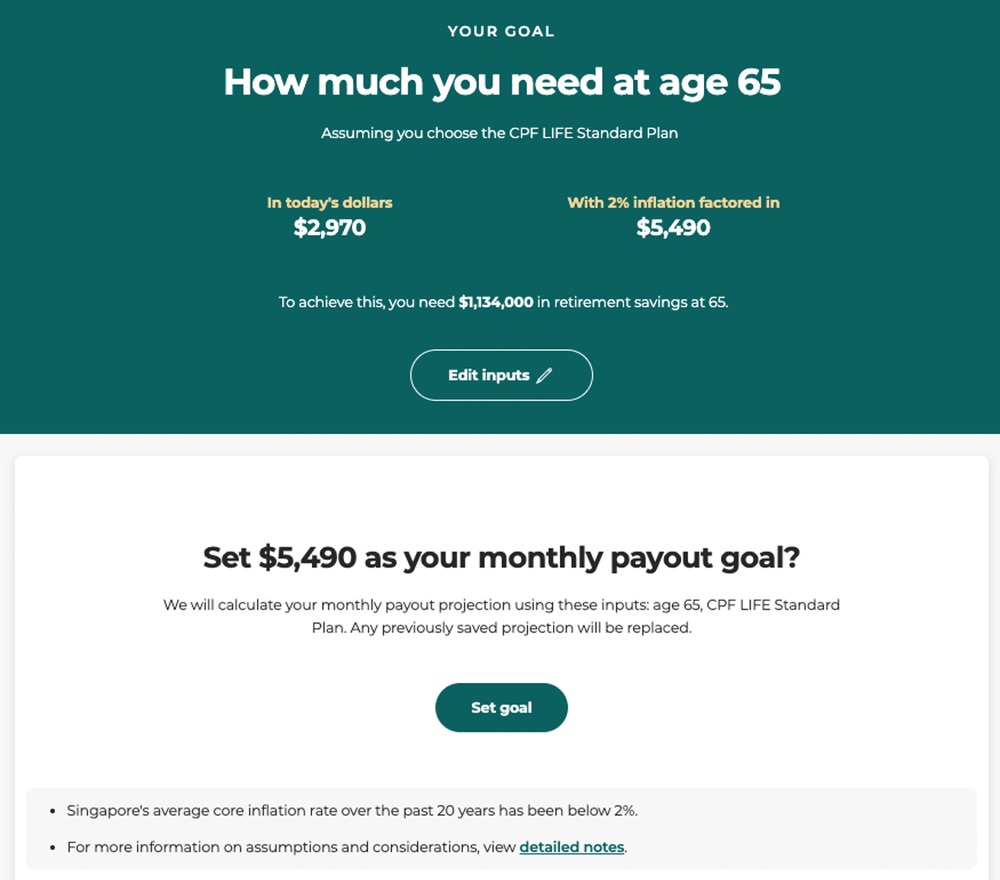
Seeing S$5,490 on the screen made me pause.
I didn’t expect the figure to be high, since the lifestyle I had just described did not feel particularly extravagant. It made me realise just how much more I need monthly to maintain something broadly similar decades from now.
For the first time, the effect of inflation on my retirement did not feel theoretical.
Seeing what my CPF could actually provide
Once I had a target, the next question was obvious: How much of it might my current CPF savings provide?
This was probably the part of the exercise that changed how I thought about CPF the most.
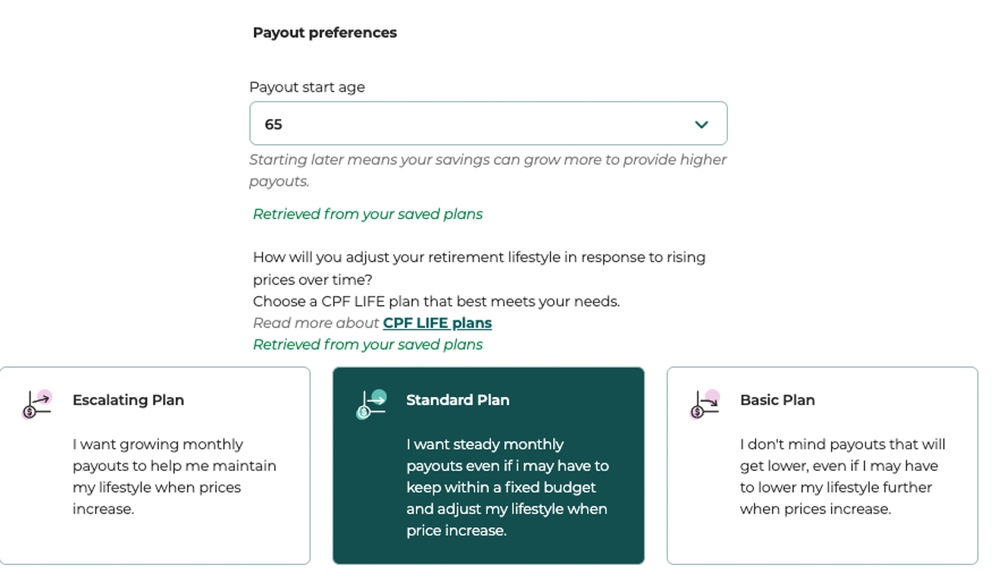
After factoring in my current income into the planner, I had to think about how willing I would be to adjust my lifestyle as prices rise during retirement.
After going through the options and discussing it with my husband, I selected the CPF LIFE Standard Plan.
CPF LIFE provides monthly payouts for as long as you live, and I felt the Standard Plan suited me because I preferred the idea of receiving steady monthly payouts, even if I might need to adjust my lifestyle as prices rise over time.
Once I had entered the relevant information, I could see my retirement goal alongside my projected CPF payout.
My projected CPF payout was around S$3,110 a month compared with my retirement payout goal of S$5,490, leaving a projected shortfall of about S$2,380.
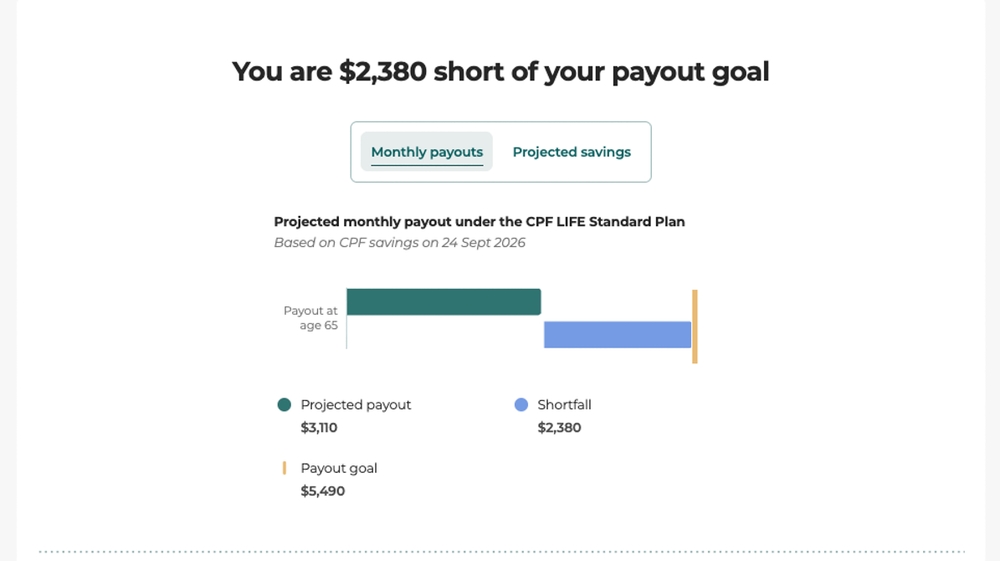
Seeing a projected shortfall of S$2,380 a month was uncomfortable at first. But there was also something reassuring about finally having a number to work with.
Instead of looking at my CPF balance and wondering vaguely whether it was “enough”, I could see what those savings might actually translate into each month and what I still needed to plan for.
Seeing the gap helped me think about what I could do next
What I found useful was being able to test different actions rather than simply being told to “save more for retirement”.
I could compare regular monthly top-ups with a larger one-off amount and see how each might affect my projected payout.
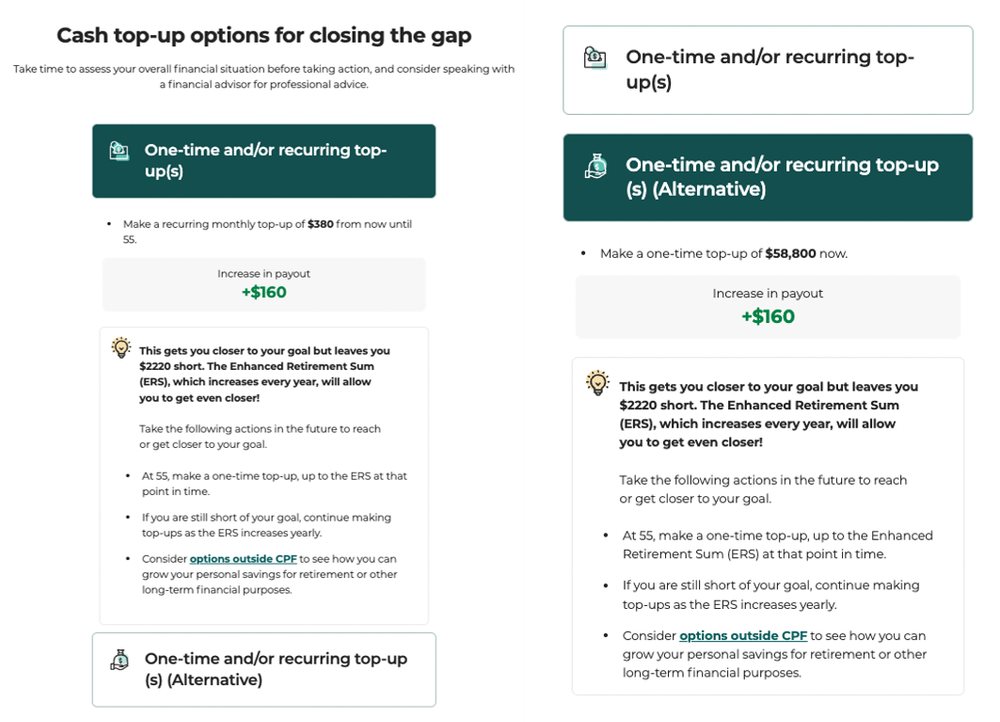
But I did not come away thinking I should immediately redirect a large amount of money into my CPF.
Cash top-ups and CPF transfers made for retirement are irreversible, and after our wedding and renovation, rebuilding our cash savings still matters to us. We also want to continue setting aside money for travel and investments.
For me, one realistic option could be to work towards making cash top-ups of up to S$8,000 a year when our finances allow.
Eligible cash top-ups to my own CPF retirement savings can qualify for up to S$8,000 of tax relief in a calendar year, subject to the prevailing conditions and tax-relief limits.
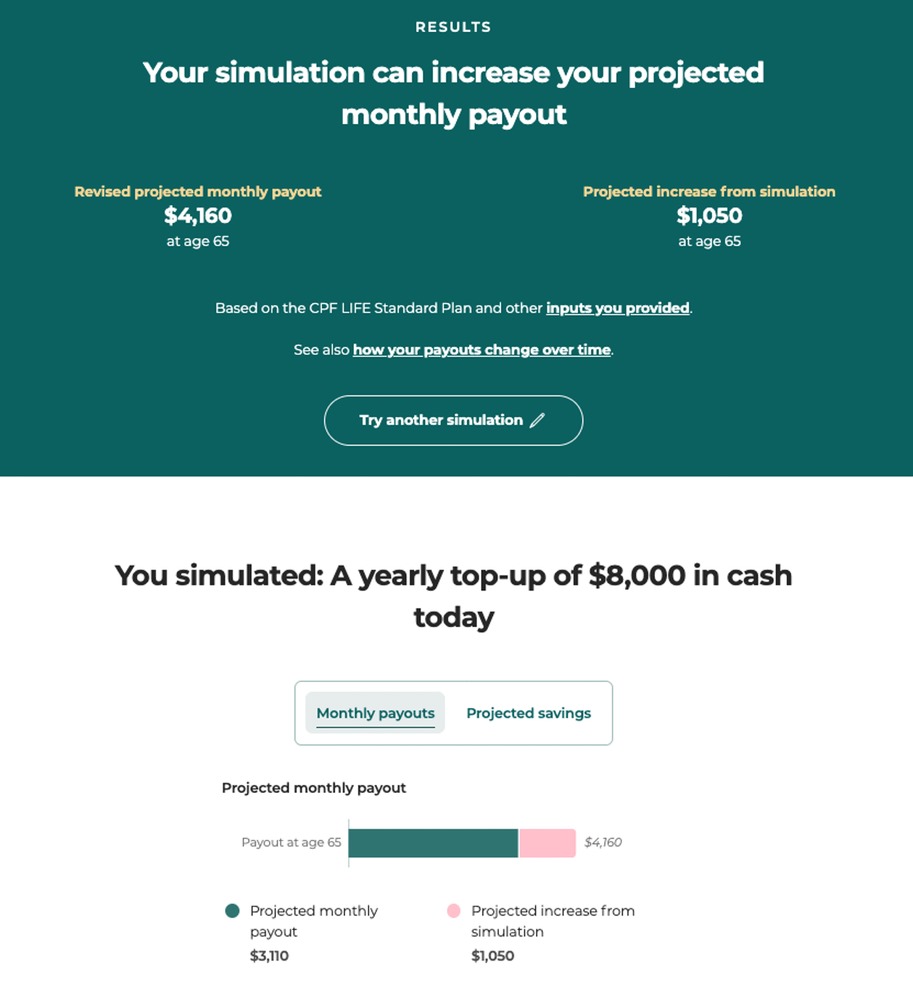
Since an annual top-up felt more achievable, I simulated making an S$8,000 cash top-up each year.
Seeing the projected payout rise from S$3,110 to S$4,160 made the shortfall feel less daunting. It showed me that actions taken over time could materially change the picture and make the projected gap feel more manageable.
Before this exercise, I had assumed that if I wanted more retirement income, I would mainly need to build a larger investment portfolio, which also means taking on investment risk.
Now, I see the two as complementary. My CPF savings can provide a stable foundation for my retirement income through risk-free CPF interest rates, while I can consider investments for additional growth, recognising the market risks involved.
Retirement planning does not have to mean putting life on hold
Before using the planner, retirement was one of those things I knew we should plan for, but it was easy to push aside because it still felt decades away.
I also assumed that getting more serious about retirement would mean giving up more of what we enjoy today.
After using the Retirement Payout Planner, I came away with a different view, which is to be more deliberate about how we balance our current priorities with our longer-term plans.
I also don’t see the S$5,490 payout goal as something fixed forever, but as something we can revisit as our circumstances and priorities change.
For me, the biggest change is that retirement no longer feels like a vague concern for “future us”.
We have a starting point now, and that makes it much easier to decide what steps make sense along the way.
Want to see what your own CPF retirement payouts could look like?
If you’re wondering how your CPF savings today can support the retirement you want, the Retirement Payout Planner helps you explore this in bite-sized steps. You can always revisit your numbers when your circumstances change.
You can also visit CPF Board’s Ready for Life Festival from 30 October to 22 November 2026, featuring interactive roadshows and talks with financial planning tips.
Read also
Gain financial insights in minutes
Subscribe to our free weekly newsletter for more insights to grow your wealth
Most Popular

Comments
0 comments