
United Hampshire US REIT: Stronger 1H26 on acquisitions and rental growth
REITs
By Goh Lay Peng • 05 Sep 2026
Global Wealth Technology Pte. Ltd. is regulated by the Monetary Authority of Singapore (MAS) as a licensed Financial Adviser.

Make Beansprout your preferred source on Google
Add us on Google to see more of our insights in your search results
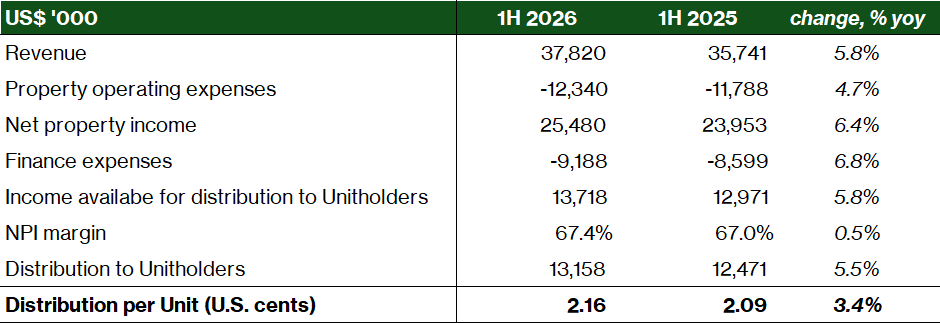
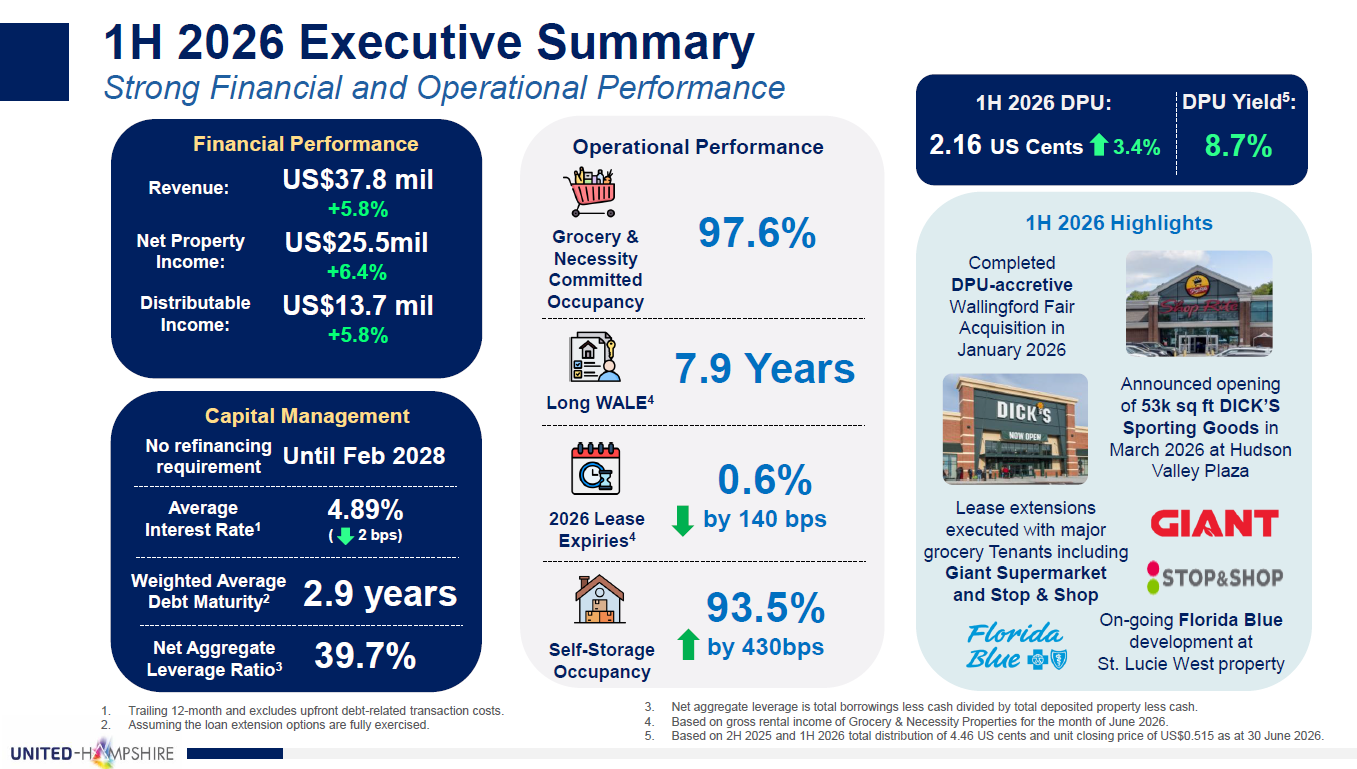
United Hampshire US REIT (UHREIT) reported a stronger 1H26, with revenue rising 5.8% year-on-year to US$37.8 million across a broad base. Net property income (NPI) increased 6.4% year-on-year to US$25.5 million. Distributable income grew 5.8% to US$13.7 million, while DPU increased 3.4% year-on-year to 2.16 US cents.
Revenue growth supported by acquisitions and leasing momentum
 |
Source: United Hampshire US REIT 1H26 results presentation |
United Hampshire US REIT (UHREIT) reported a stronger 1H26, with revenue rising 5.8% year-on-year to US$37.8 million across a broad base. Net property income (NPI) increased 6.4% year-on-year to US$25.5 million.
Management attributed the improvement to new leases, built-in rental escalations and contributions from Dover Marketplace and Wallingford Fair, acquired in August 2025 and January 2026 respectively. NPI margin improved to 67.4% in 1H26, from 67.0% in 1H25.
Finance expenses increased by 6.8% year-on-year to US$9.2 million, mainly due to additional borrowings undertaken to finance the acquisition of Wallingford Fair. This was partially offset by lower interest rates on floating-rate loans.
Distributable income grew 5.8% to US$13.7 million, while DPU increased 3.4% year-on-year to 2.16 US cents. The 1H26 distribution includes 1.00 US cent of capital distribution, accounting for about 46% of the total 2.16 US cents DPU.
 |
Source: United Hampshire US REIT 1H26 results presentation |
Healthy balance sheet
Figure 3: Balance sheet highlights |
|
Source: United Hampshire US REIT 1H26 results presentation |
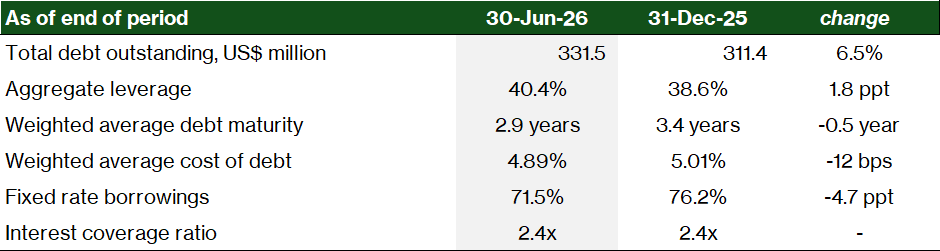
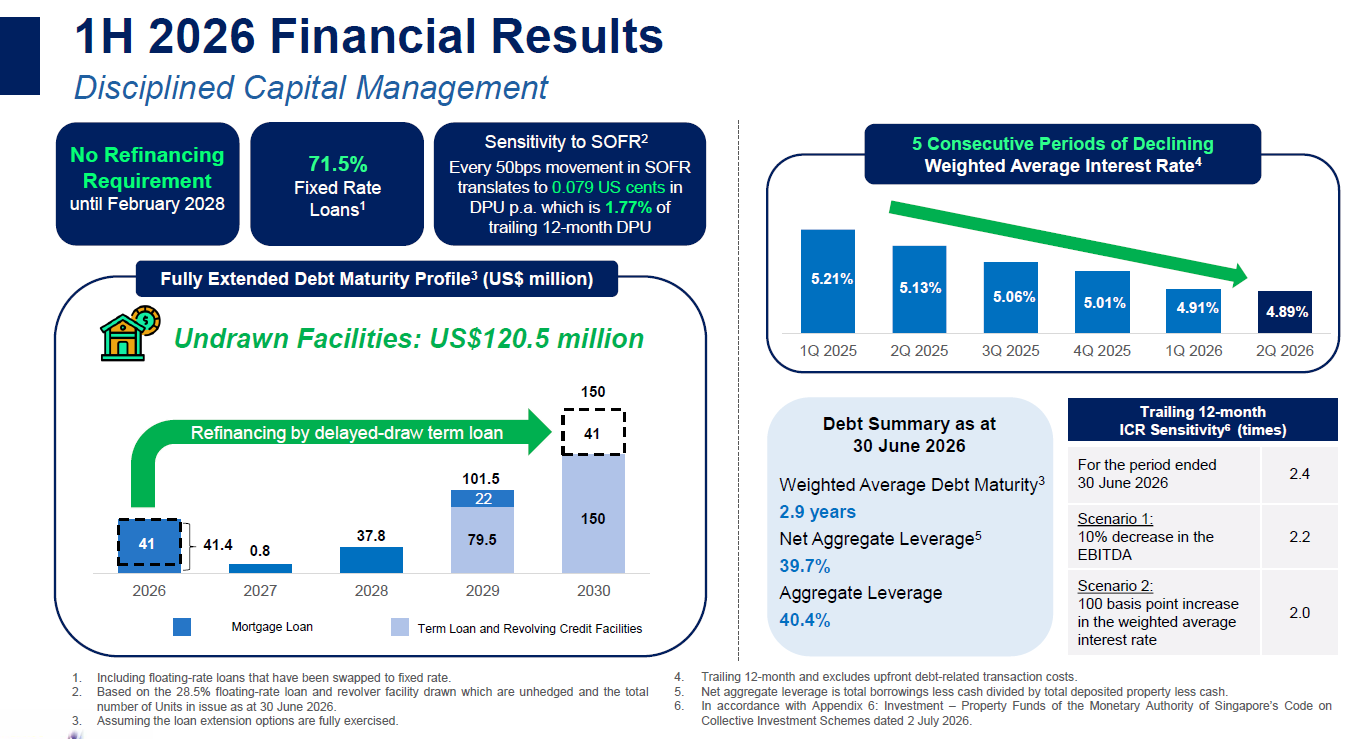
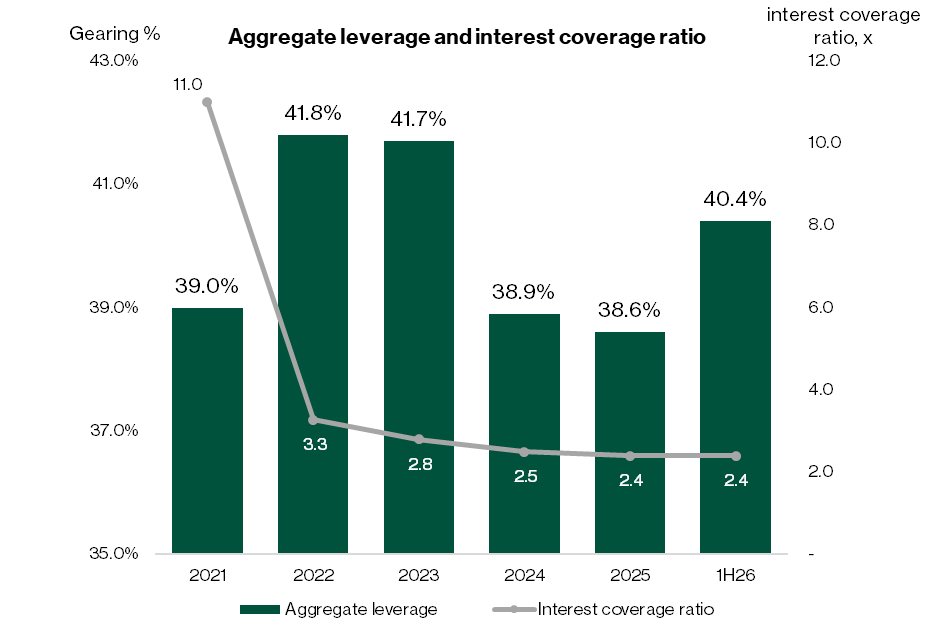
UHREIT’s aggregate leverage stood at 40.4% as at 30 June 2026, slightly higher than 38.6% as at 31 December 2025.
Weighted average debt maturity was 2.9 years, with no refinancing requirements until February 2028.
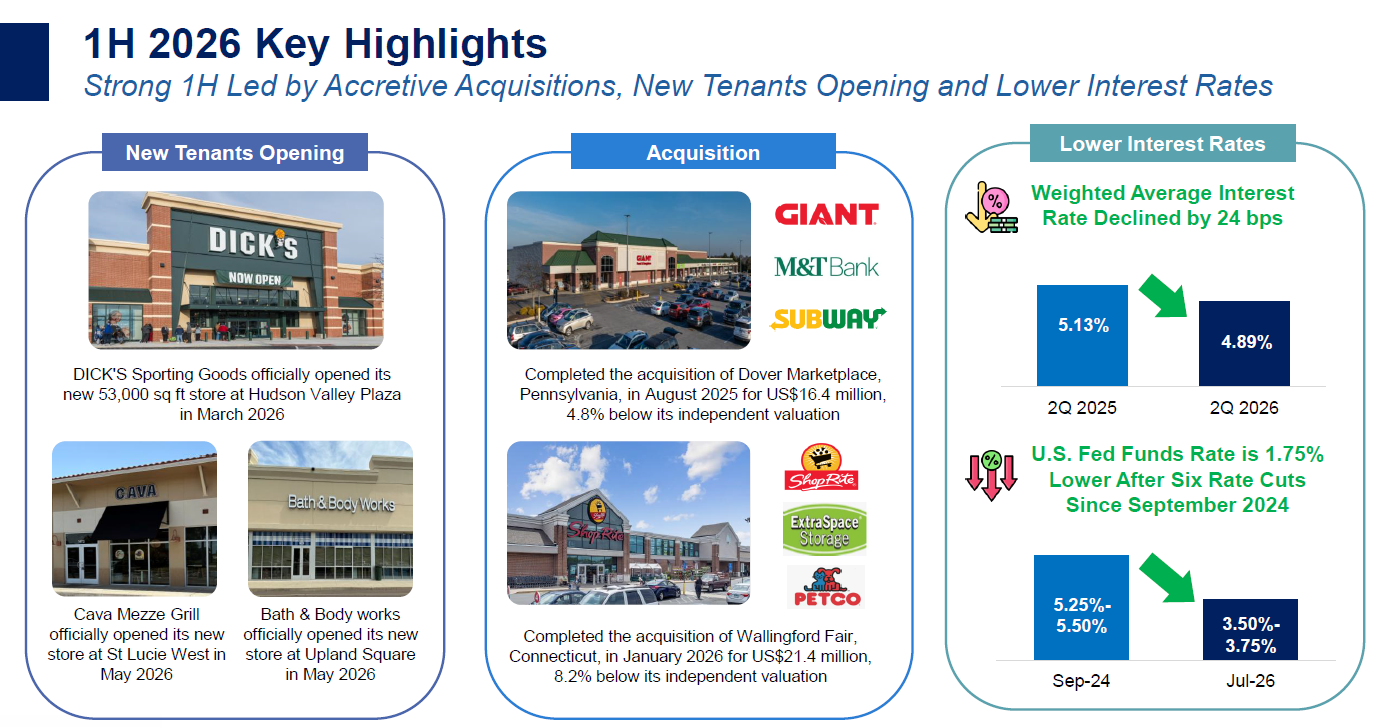
The weighted average interest rate declined for the fifth consecutive reporting period to 4.89%, while trailing twelve-month interest coverage remained at a healthy 2.4x.
The balance sheet provides some protection against near-term refinancing risk, although gearing is relatively close to the 45% threshold used in our Income Pot framework.
Management also highlighted that 71.5% of borrowings were fixed-rate, while every 50 basis point movement in SOFR is estimated to affect annual DPU by 0.079 US cents, equivalent to 1.77% of trailing twelve-month DPU.
 |
Source: United Hampshire US REIT 1H26 results presentation |
 |
Source: United Hampshire US REIT 1H26 results presentation |
DPU growth 3.4% year-on-year
Distributable income grew 5.8% year-on-year in 1H26 to US$13.7 million.
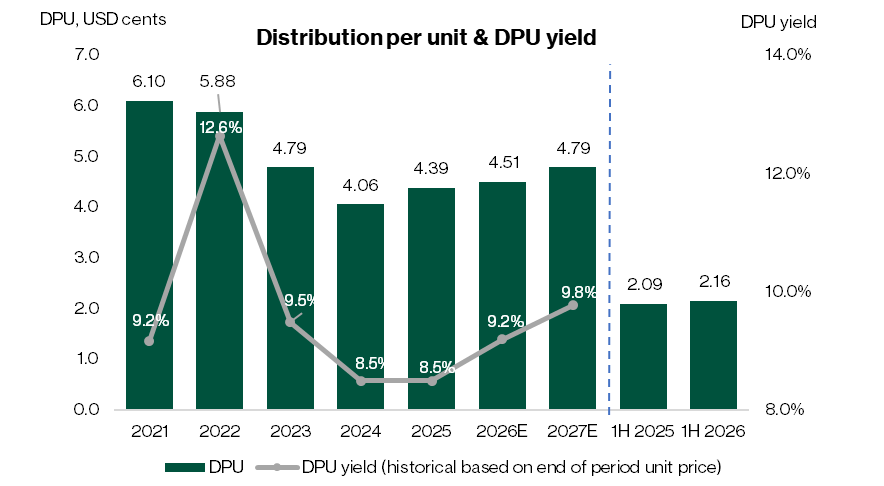
1H26 distribution per unit grew 3.4% year-on-year to 2.16 US cents, comprising 1.16 US cents of tax-exempt income and 1.00 US cent of capital distribution.
Based on the 3 September 2026 closing price of US$0.49, our estimates for FY26E DPU of 4.51 US cents implies a distribution yield of 9.2%.
The yield remains attractive relative to the 10-year U.S. Treasury yield of 4.8% on 2 Sep 2026, giving UHREIT a spread of 4.4 percentage points.
 |
Source: United Hampshire US REIT 1H26 results presentation |
Resilient portfolio with limited near-term lease risk
 |
Source: United Hampshire US REIT 1H26 results presentation |
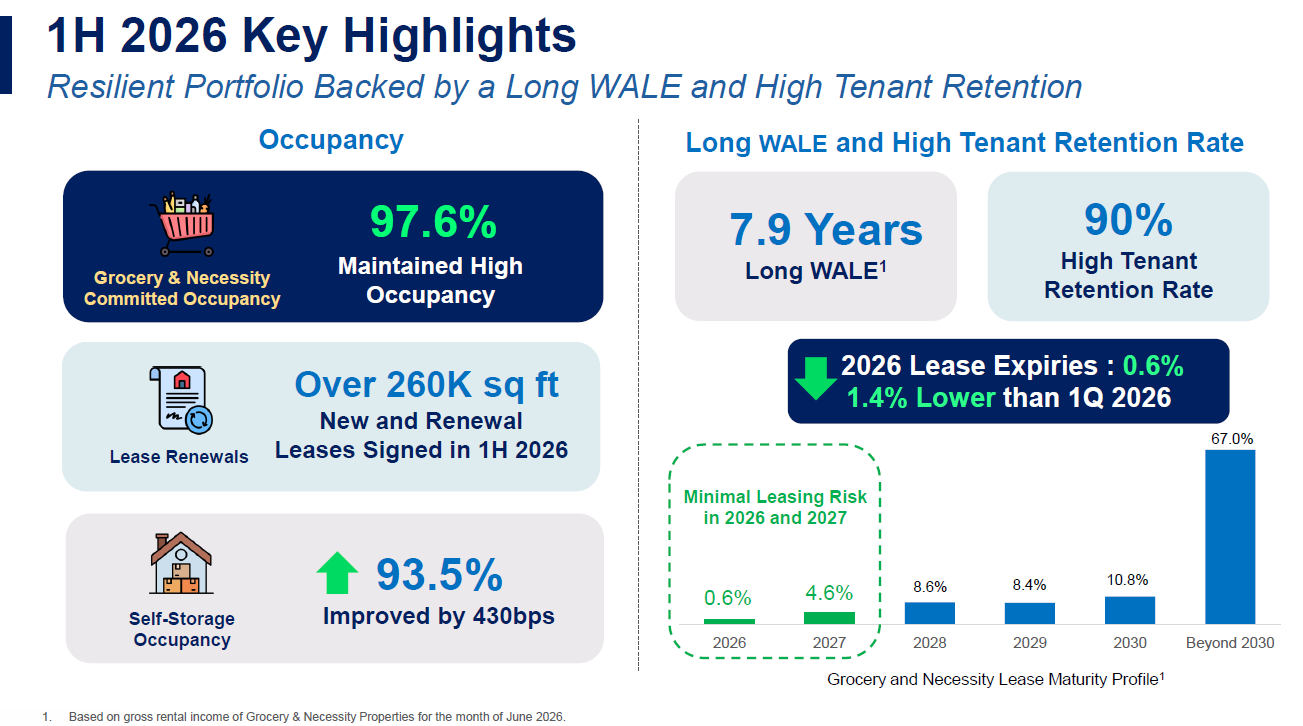
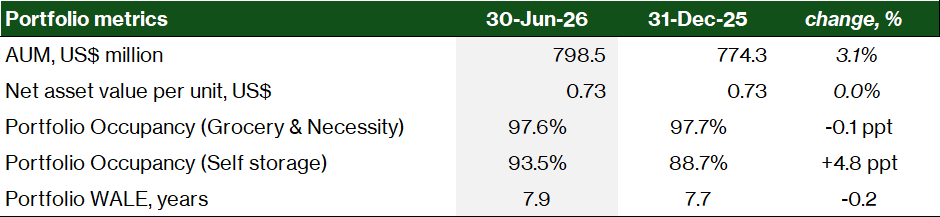
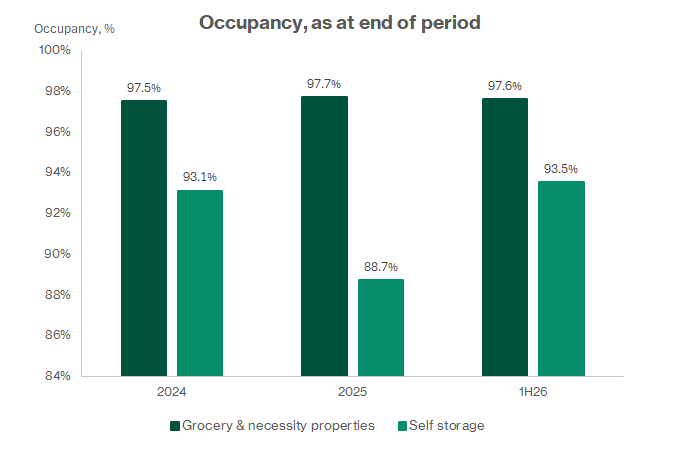
UHREIT’s Grocery & Necessity portfolio continues to provide good income visibility. Committed occupancy stood at 97.6%, with a 7.9-year WALE (weighted average lease expiry).
Only 0.6% and 4.6% of leases expire in 2026 and 2027, respectively. The long lease expiry profile and 90% tenant retention rate reduce near-term leasing risk.
The portfolio also secured more than 260,000 sq ft of new and renewal leases in 1H26, including leases with Giant Supermarket, Stop & Shop Supermarket, Wendy’s and Bath & Body Works.
|
Source: United Hampshire US REIT 1H26 results presentation |
|
Source: United Hampshire US REIT 1H26 results presentation |
Recent acquisitions are also contributing positively. Wallingford Fair was acquired for US$21.4 million in January 2026, 8.2% below valuation. While Dover Marketplace was acquired in August 2025 for US$16.4 million, 4.8% below valuation. The acquisitions have supported revenue and NPI growth, although the additional borrowings have also increased finance costs.
 |
Source: United Hampshire US REIT 1H26 results presentation |
Recent developments
Proposed divestment of BJ’s Quincy
On 18 Aug 2026, UHREIT announced the divestment of BJ’s Quincy for US$34.0 million to 200 Crown, LLC. The purchaser is an unrelated third party. The sale price represents a premium of 4.9% above valuation.
The estimated net proceeds are US$33.3 million. The liquidity further improves UHREIT’s financial flexibility and strengthens its capital structure. If the proceeds are used for debt repayment, UHREIT’s pro forma aggregate leverage as at 31 Dec 2026 will improve to 35.9%, from 38.6%.
BJ's Quincy is a single-storey free-standing building leased to BJ’s Wholesale Club. The 84,360 sq ft property is freehold.
The divestment is part of its broader portfolio optimisation and capital recycling strategy, with proceeds potentially redeployed into growth opportunities such as new acquisitions, asset enhancement initiatives and future development opportunities. The divestment is expected to complete on 15 Sep 2026.
Dick’s Sporting Goods reported disappointing Q2 earnings and cut guidance
On 25 Aug 2026, Dick’s Sporting Goods reported Q2 earnings that missed expectations. It also lowered its overall sales outlook for the year by 1% to a range between US$21.9 billion and US$22.2 billion.
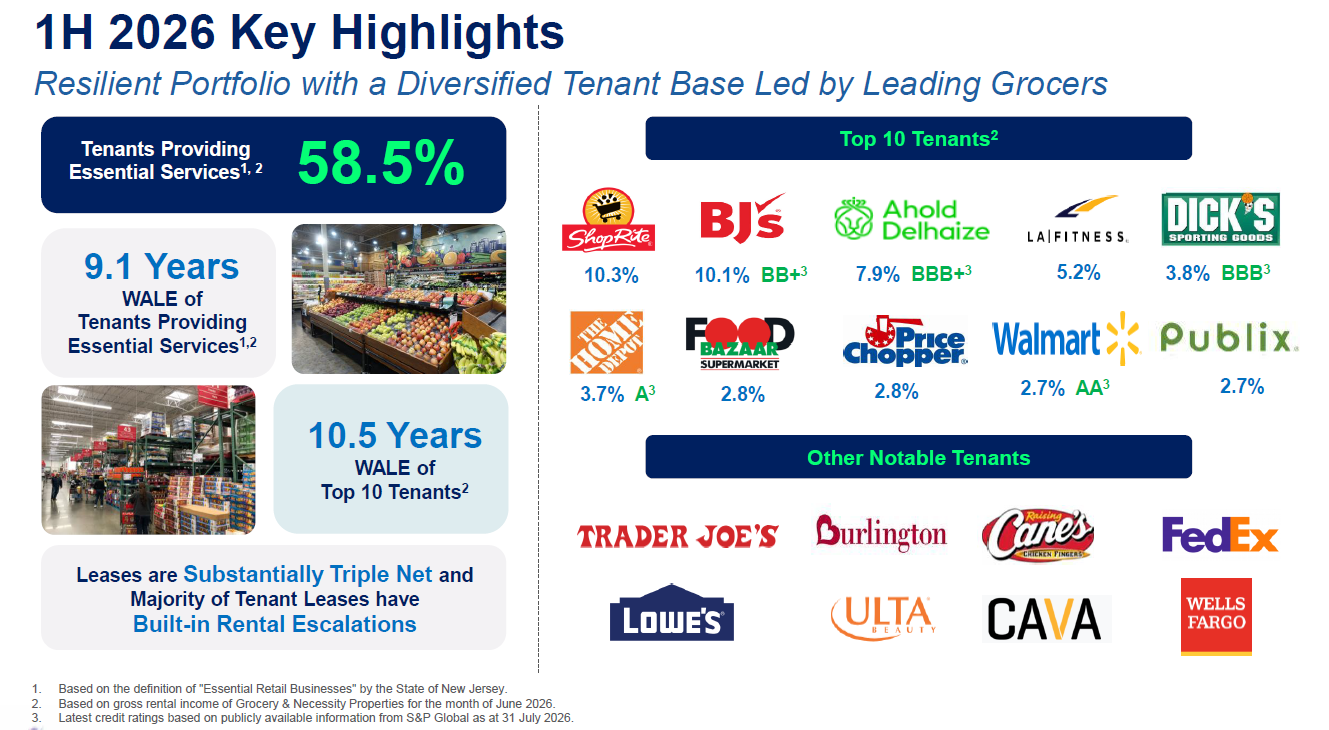
Dick’s Sporting Goods is UHREIT’s fifth-largest tenant and accounts for 3.8% of gross rental income of Grocery & Necessity. We do not expect a significant impact on UHREIT given the relatively modest downward revision and the REIT’s well-diversified tenant base. UHREIT has a well-diversified tenant base with top 10 tenants accounting for 52% of gross rental income.
That said, we will monitor the situation closely.
 |
Source: United Hampshire US REIT 1H26 results presentation |
Maintain BUY and target price of US$0.62
We maintain BUY on United Hampshire US REIT with a target price of US$0.62, based on the Dividend Discount Model (DDM) with a cost of equity of 10% and a terminal growth rate of 2.0%.
Our COE of 10% reflects the REIT’s U.S. dollar-denominated income base, the relatively small market capitalisation and associated liquidity premium, and the current S-REIT sector discount environment.
Currently, it is trading at US$0.49, implying FY26E distribution yield of 9.2%. This is attractive relative to the peer average FY26E distribution yield of 8.3%.
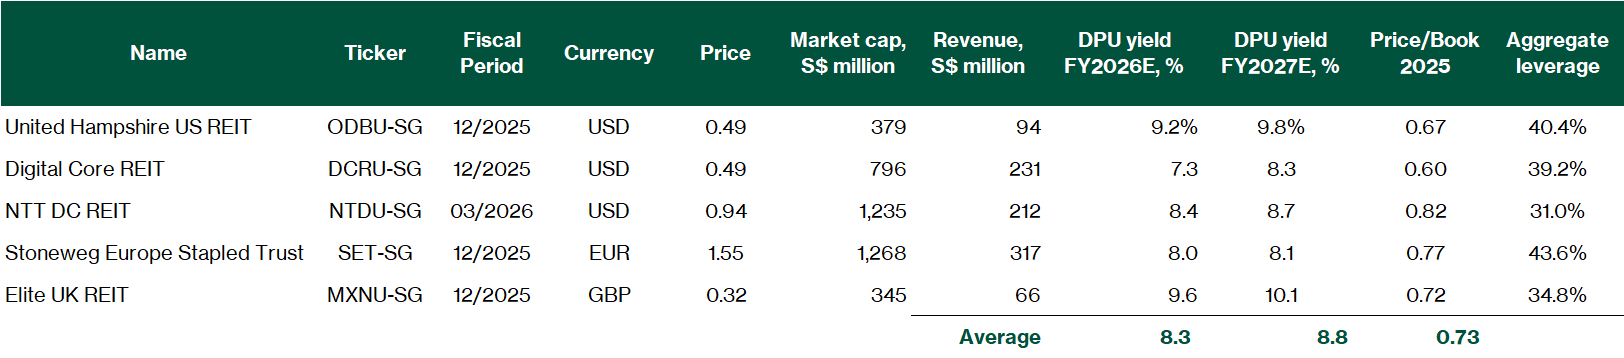 |
Source: FactSet, Beansprout research, prices as of 2 September 2026 |
United Hampshire US REIT on Beansprout’s REIT Income Pot framework
We apply Beansprout’s REIT screening framework: DPU growth, gearing, and yield versus risk-free alternatives - to assess whether United Hampshire US REIT (“UHREIT”) is suitable for an income-focused portfolio.
| Check | United Hampshire US REIT |
| DPU growth – able to generate stable earnings | ✅ Pass — 1H26 DPU 2.16 cents, +3.4% year-on-year |
| Aggregate leverage < 45% | ✅ Pass — 40.4% as of 30 June 2026 |
| Dividend yield > 5% | ✅ Pass — Based on our projection, FY26E DPU of 4.51 cents, UHREIT offers a distribution yield of 9.2% (3 Sep closing price US$0.49) |
| Overall | 3/3 checks |
| Source: Beansprout | |
Check #1: DPU grew steadily
1H26 DPU of 2.16 cents was 3.4% higher year-on-year, with gross revenue up 5.8% and NPI +6.4% year-on-year.
Check #2: Gearing ratio at an acceptable level
Aggregate leverage stood at 40.4% as at 30 June 2026, remaining below Beansprout’s preferred 45% threshold.
Interest coverage ratio of 2.4x and a well-balanced debt profile further support balance sheet resilience. It has no refinancing requirements until February 2028. UHREIT has S$120.5 million of undrawn facilities.
Check #3: Distribution yield remains attractive
We estimate FY26E DPU at 4.51 cents (1H FY26 2.16 cents). The closing price of US$0.49 on 3 Sep 2026 implies a distribution yield of 9.2%.
Currently, the Singapore Savings Bond is offering about 2.1%, while the 6-month T-bill is offering around 1.6%.
UHREIT is trading at a spread of 7.1 to 7.6 percentage points over risk-free rates. This is above Beansprout’s preferred minimum spread of about 3 percentage points, compensating investors for its US dollar exposure in assets and income.
UHREIT passes the checks for the Income Pot framework.
Investors should monitor asset acquisitions, the aggregate leverage ratio and revenue growth trends. While the REIT’s distributable income increased 5.8%, investors should distinguish between recurring income and capital distributions when assessing the quality of the headline yield.
Key risks
Key risks include concentrated exposure to anchor tenants, low trading liquidity and economic cyclicality.
Concentrated exposure to anchor tenants
As at 31 March 2026, the top 10 tenants accounted for 52% of gross rental income. The largest single tenant, BJ’s Wholesale Club Holdings, represents approximately 10.1% of portfolio gross rental income. Any material deterioration in BJ’s financial health, closure of stores, or failure to renew leases could have an adverse impact on United Hampshire US REIT’s income. However, BJ’s Wholesale Club is an established, publicly listed company (NASDAQ: BJ) with a market capitalisation of US$11.3 billion. We think this mitigates near-term risk to portfolio income.
Currency risk
United Hampshire US REIT’s income and NAV are denominated in US dollar. Singapore-based investors are therefore exposed to SGD/USD fluctuations, which could affect the SGD value of distributions. Management partially mitigates this by offering distributions payable in USD, SGD (at the prevailing exchange rate), or via the Distribution Reinvestment Plan. The DRP take-up rate has historically ranged from 6% to 32%, with an average of approximately 20%.
Interest rate risk
While the current environment is characterised by declining interest rates, an unexpected reversal — driven by persistent inflation or exogenous shocks — could compress UHREIT’s distributable income. With 21.5% of borrowings on floating-rate SOFR, each 100 basis point increase in rates reduces annual distributable income by approximately US$0.7–0.8 million, equivalent to roughly 0.1–0.13 US cents per unit on current unit count.
Macro-driven consumer spending softness
Grocery-anchored strip centres are not entirely immune to macroeconomic deterioration. A sustained consumer spending downturn — whether driven by tariff-related price increases, employment deterioration, or global financial shocks — could affect tenant sales and, ultimately, the ability of inline tenants to absorb built-in rent escalations upon renewal. UHREIT’s exposure to this risk is partially mitigated by the essential, non-discretionary nature of its anchor tenants, but the tail risk exists.
Trading liquidity
UHREIT’s market capitalisation of approximately US$300 million (S$381 million) and three-month average daily turnover of approximately US$0.20 million place it at the smaller end of the SGX REIT universe. This may limit institutional ownership and result in a structural liquidity discount relative to larger-capitalisation peers. Investors should factor liquidity considerations into position sizing.
Related links:
- United Hampshire US REIT share price and share price target
- United Hampshire US REIT dividend history and forecast
Download the full report here.
Check out Beansprout guide to the best stock trading platforms in Singapore with the latest promotions to invest in United Hamsphire US REIT.
Join the Beansprout Telegram group for the latest insights on Singapore stocks, REITs, bonds and ETFs.
Important Disclosures
Analyst Certification and Disclosures
The analyst(s) named in this report certifies that (i) all views expressed in this report accurately reflect the personal views of the analyst(s) with regard to any and all of the subject securities and companies mentioned in this report and (ii) no part of the compensation of the analyst(s) was, is, or will be, directly or indirectly, related to the specific views expressed by that analyst herein. The analyst(s) named in this report (or their associates) does not have a financial interest in the corporation(s) mentioned in this report.
An associate is defined as (i) the spouse, or any minor child (natural or adopted) or minor step-child, of the analyst; (ii) the trustee of a trust of which the analyst, his spouse, minor child (natural or adopted) or minor step-child, is a beneficiary or discretionary object; or (iii) another person accustomed or obliged to act in accordance with the directions or instructions of the analyst.
Company Disclosure
Global Wealth Technology Pte Ltd (“Beansprout”) does not have any financial interest in the corporation(s) mentioned in this report.
Disclaimer
This report is provided by Beansprout for the use of intended recipients only and may not be reproduced, in whole or in part, or delivered or transmitted to any other person without our prior written consent. By accepting this report, the recipient agrees to be bound by the terms and limitations set out herein.
You acknowledge that this document is provided for general information purposes only. Nothing in this document shall be construed as a recommendation to purchase, sell, or hold any security or other investment, or to pursue any investment style or strategy. Nothing in this document shall be construed as advice that purports to be tailored to your needs or the needs of any person or company receiving the advice. The information in this document is intended for general circulation only and does not constitute investment advice. Nothing in this document is published with regard to the specific investment objectives, financial situation and particular needs of any person who may receive the information.
Nothing in this document shall be construed as, or form part of, any offer for sale or subscription of or solicitation or invitation of any offer to buy or subscribe for any securities. The data and information made available in this document are of a general nature and do not purport, and shall not in any way be deemed, to constitute an offer or provision of any professional or expert advice, including without limitation any financial, investment, legal, accounting or tax advice, and shall not be relied upon by you in that regard. You should at all times consult a qualified expert or professional adviser to obtain advice and independent verification of the information and data contained herein before acting on it. Any financial or investment information in this document are intended to be for your general information only. You should not rely upon such information in making any particular investment or other decision which should only be made after consulting with a fully qualified financial adviser. Such information do not nor are they intended to constitute any form of financial or investment advice, opinion or recommendation about any investment product, or any inducement or invitation relating to any of the products listed or referred to. Any arrangement made between you and a third party named on or linked to from these pages is at your sole risk and responsibility.
You acknowledge that Beansprout is under no obligation to exercise editorial control over, and to review, edit or amend any data, information, materials or contents of any content in this document. You agree that all statements, offers, information, opinions, materials, content in this document should be used, accepted and relied upon only with care and discretion and at your own risk, and Beansprout shall not be responsible for any loss, damage or liability incurred by you arising from such use or reliance.
This document (including all information and materials contained in this document) is provided “as is”. Although the material in this document is based upon information that Beansprout considers reliable and endeavours to keep current, Beansprout does not assure that this material is accurate, current or complete and is not providing any warranties or representations regarding the material contained in this document. All opinions contained herein constitute the views of the analyst(s) named in this report, they are subject to change without notice and are not intended to provide the sole basis of any evaluation of the subject securities and companies mentioned in this report. Any reference to past performance should not be taken as an indication of future performance. To the fullest extent permissible pursuant to applicable law, Beansprout disclaims all warranties and/or representations of any kind with regard to this document, including but not limited to any implied warranties of merchantability, non-infringement of third-party rights, or fitness for a particular purpose.
Beansprout does not warrant, either expressly or impliedly, the accuracy or completeness of the information, text, graphics, links or other items contained in this document. Neither Beansprout nor any of its affiliates, directors, employees or other representatives will be liable for any damages, losses or liabilities of any kind arising out of or in connection with the use of this document. To the best of Beansprout’s knowledge, this document does not contain and is not based on any non-public, material information. The information in this document is not intended for distribution to, or use by, any person or entity in any jurisdiction where such distribution or use would be contrary to law or regulation, or which would subject Beansprout to any registration requirement within such jurisdiction or country. Beansprout is not licensed or regulated by any authority in any jurisdiction or country to provide the information in this document.
As a condition of your use of this document, you agree to indemnify, defend and hold harmless Beansprout and its affiliates, and their respective officers, directors, employees, members, managing members, managers, agents, representatives, successors and assigns from and against any and all actions, causes of action, claims, charges, cost, demands, expenses and damages (including attorneys’ fees and expenses), losses and liabilities or other expenses of any kind that arise directly or indirectly out of or from, arising out of or in connection with violation of these terms, use of this document, violation of the rights of any third party, acts, omissions or negligence of third parties, their directors, employees or agents. To the extent permitted by law, Beansprout shall not be liable to you, any other person, or organization, for any direct, indirect, special, punitive, exemplary, incidental or consequential damages, whether in contract, tort (including negligence), or otherwise, arising in any way from, or in connection with, the use of this document and/or its content. This includes, without limitation, liability for any act or omission in reliance on the information in this document. Beansprout expressly disclaims and excludes all warranties, conditions, representations and terms not expressly set out in this User Agreement, whether express, implied or statutory, with regard to this document and its content, including any implied warranties or representations about the accuracy or completeness of this document and the content, suitability and general availability, or whether it is free from error.
If these terms or any part of them is understood to be illegal, invalid or otherwise unenforceable under the laws of any state or country in which these terms are intended to be effective, then to the extent that they are illegal, invalid or unenforceable, they shall in that state or country be treated as severed and deleted from these terms and the remaining terms shall survive and remain fully intact and in effect and will continue to be binding and enforceable in that state or country.
These terms, as well as any claims arising from or related thereto, are governed by the laws of Singapore without reference to the principles of conflicts of laws thereof. You agree to submit to the personal and exclusive jurisdiction of the courts of Singapore with respect to all disputes arising out of or related to this Agreement. Beansprout and you each hereby irrevocably consent to the jurisdiction of such courts, and each Party hereby waives any claim or defence that such forum is not convenient or proper.
Read also
Gain financial insights in minutes
Subscribe to our free weekly newsletter for more insights to grow your wealth
Most Popular

Comments
0 comments