
EGP Energy Corporation Limited : Singapore’s power grid specialist with a strong orderbook
Stocks
By Goh Lay Peng • 07 Oct 2026
Global Wealth Technology Pte. Ltd. is regulated by the Monetary Authority of Singapore (MAS) as a licensed Financial Adviser.

Make Beansprout your preferred source on Google
Add us on Google to see more of our insights in your search results
EGP Energy Corporation Limited (“EGP”) is Singapore's #1 EPC management services for T&D projects, maintenance and servicing of T&D assets. EGP held an estimated 37.5% share of Singapore’s EHV/HV switchgear market and 24.9% share of the EHV/HV switchgear and transformer market in 2025.
Powering Singapore’s grid upgrade cycle
About EGP Energy Corporation Limited
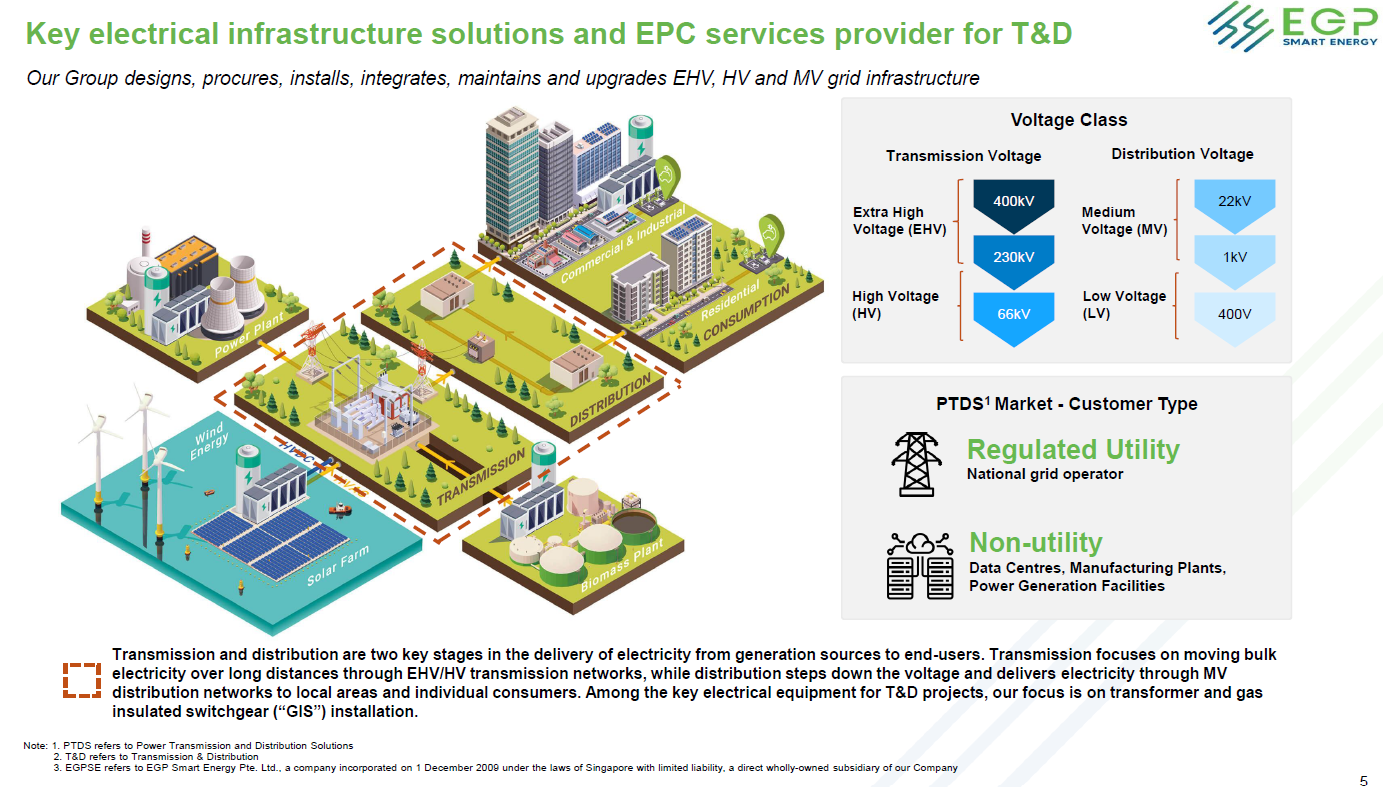
Established in Singapore in 1992, EGP Energy (“EGP”) electrical infrastructure solutions and service provider focused on transmission and distribution projects.
On 29 July 2026, EGP was listed on Mainboard of SGX-ST at the IPO price of S$0.51 per share. EGP raised S$27.4 million in net proceeds. Upon listing, the total number of shares outstanding increased to 225.45 million.
Its activities cover the full project lifecycle, including project design, equipment supply, installation, positioning, testing and commissioning, project management, and maintenance and servicing.
Management and shareholders
EGP is led by Founder and CEO Frankie Fan having more than 30 years of industry experience. Mr Frankie Fan is also the Executive Chairman of EGP.
Founder and CEO Frankie Fan Post listing, founder and CEO Frankie Fan is expected to have a deemed interest of 39.4% in EGP. Mr Ng Tian Soo, another controlling shareholder, will have 26.5% in shareholding.
Business Model
EGP defines the business in two key segments. The revenue mix has remained relatively balanced historically. T&D accounted for 54.0% of FY25 revenue, with M&S contributing 46.0%.
T&D projects – 54% of FY25 revenue
T&D projects are primarily project-based contracts covering the engineering, procurement, installation, testing and commissioning of electrical infrastructure.
The projects are generally fixed-price contracts, with revenue recognised over time based on progress towards satisfying performance obligations.
Projects typically span three to five years, meaning revenue recognition can extend across multiple financial years.
Maintenance & services – 46% of FY25 revenue
This includes inspection, testing and diagnostics, cleaning, servicing, condition monitoring, troubleshooting, equipment replacement and emergency repairs. It also includes cable docking services and management fee income.
M&S generated a 60.0% gross margin in FY25 versus 17.2% for T&D. In 1H26, the difference widened further, with M&S generating an implied gross margin of around 68%, compared with around 16% for T&D.
Autonomous quadruped robot (AMR) solutions
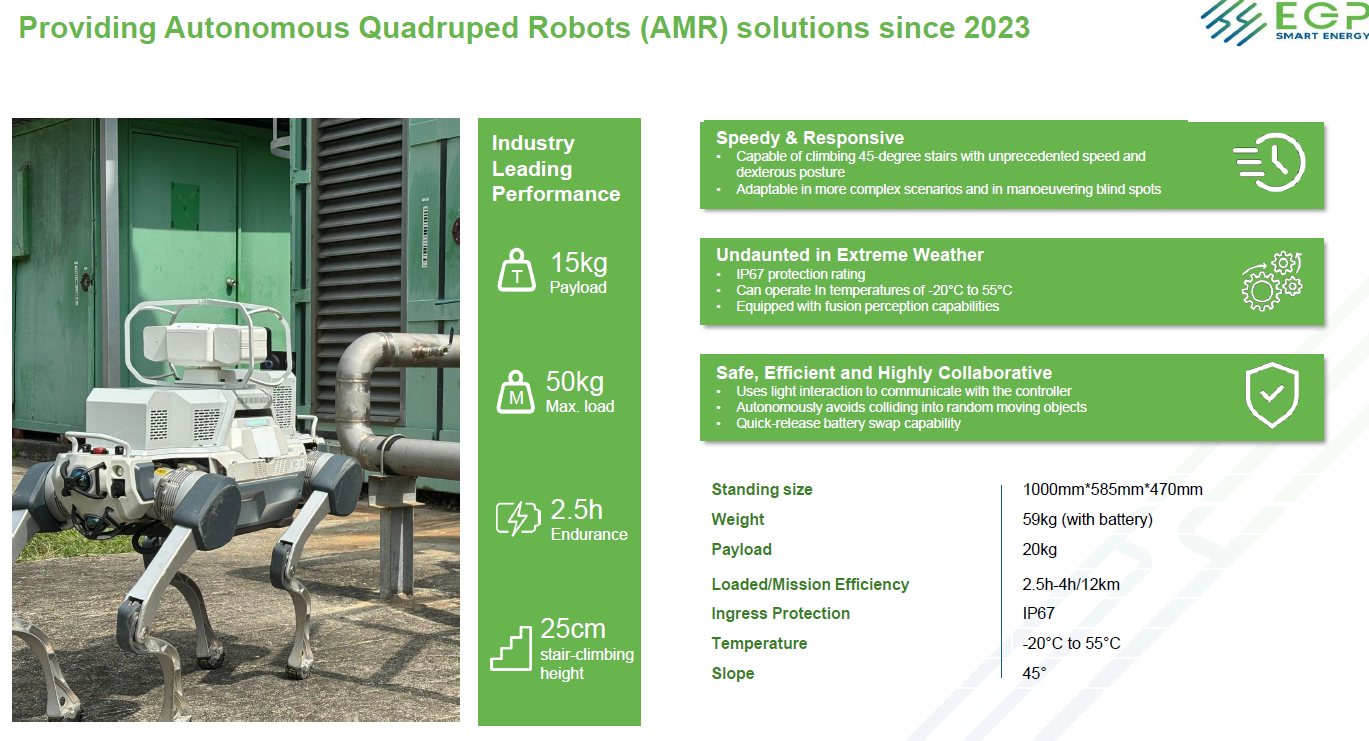
Since 2023, EGP has offered autonomous quadruped robot (AMR) solutions for infrastructure inspection and maintenance. EGP uses AMR in difficult or inaccessible environments, particularly underground infrastructure.
Furthermore, these solutions reduce reliance on manual labour, improve inspection efficiency and reducing safety risks associated with challenging environments.
EGP sources key components, protection and control systems, and AMR solutions from multiple OEMs across countries including China, Germany, the UK, France, Switzerland, Japan and South Korea.
Its diversified supplier base provides flexibility in sourcing, cost control and resilience against supply disruptions.
Asset-light model supports scalability and capital efficiency
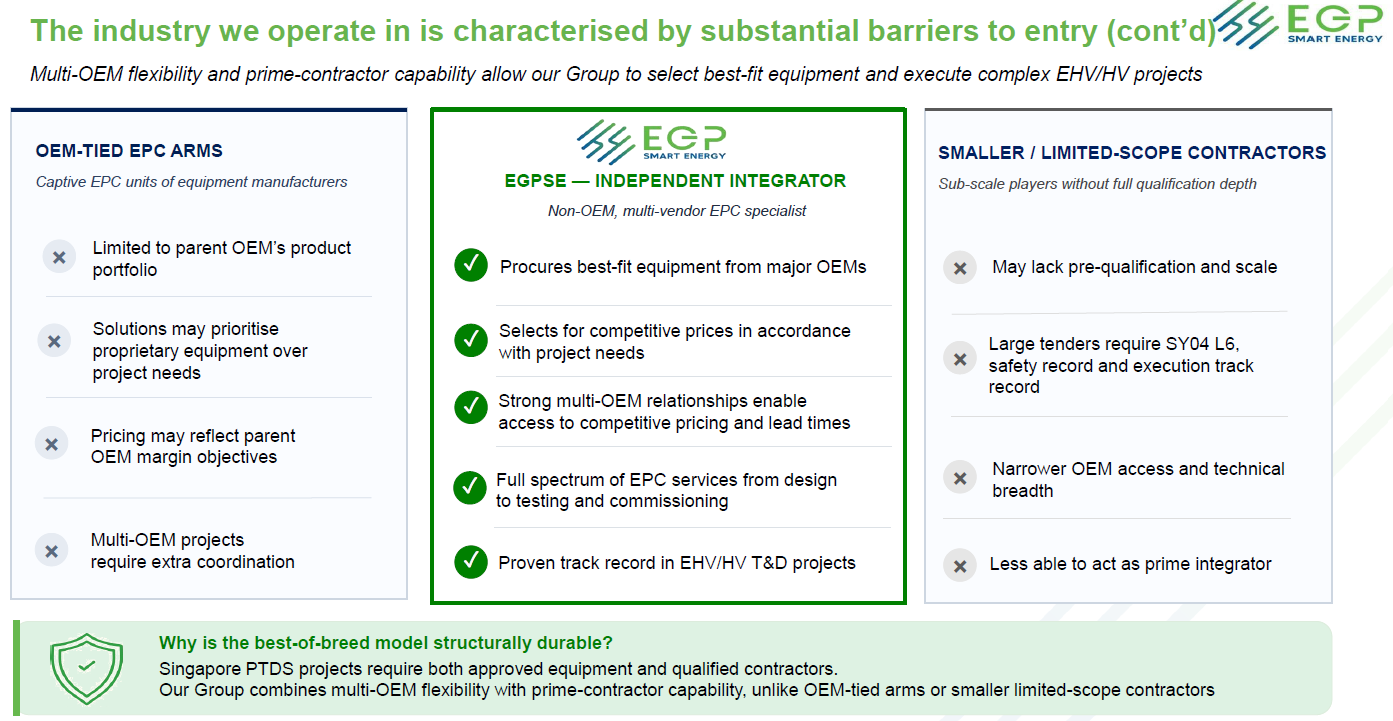
EGP operates an asset-light, project-management model, subcontracting most labor while retaining qualified project managers.
EGP’s asset-light system integrator model enables it to scale project execution without significant manufacturing investment or inventory requirements.
Its multi-OEM relationships provide flexibility to source competitively priced equipment, while its engineering and prime-contractor capabilities allow it to capture value across the project lifecycle.
This combination supports scalability while reducing exposure to equipment manufacturing risks.
Strong position in Singapore's regulated T&D market
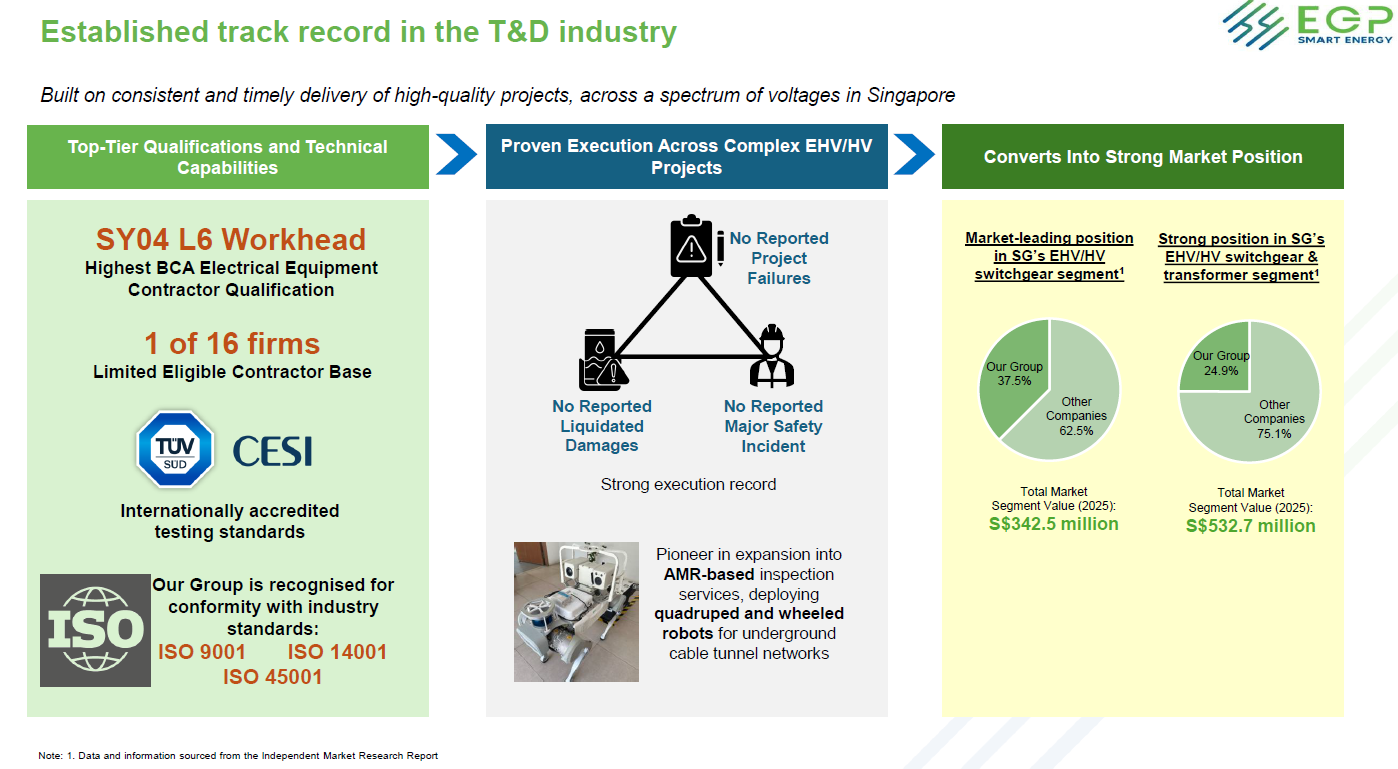
EGP has a strong competitive position in Singapore, with approximately 37.5% market share in the EHV and HV switchgear segment and 24.9% across EHV/HV switchgear and transformer segments.
EGP Energy operates in a market with significant technical and regulatory barriers.
The T&D market in Singapore is highly regulated and concentrated. SP Group is the monopoly owner of the regulated T&D assets. The T&D segment is characterised by substantial barriers to entry to protect the reliability, safety, and technical integrity of the national power grid.
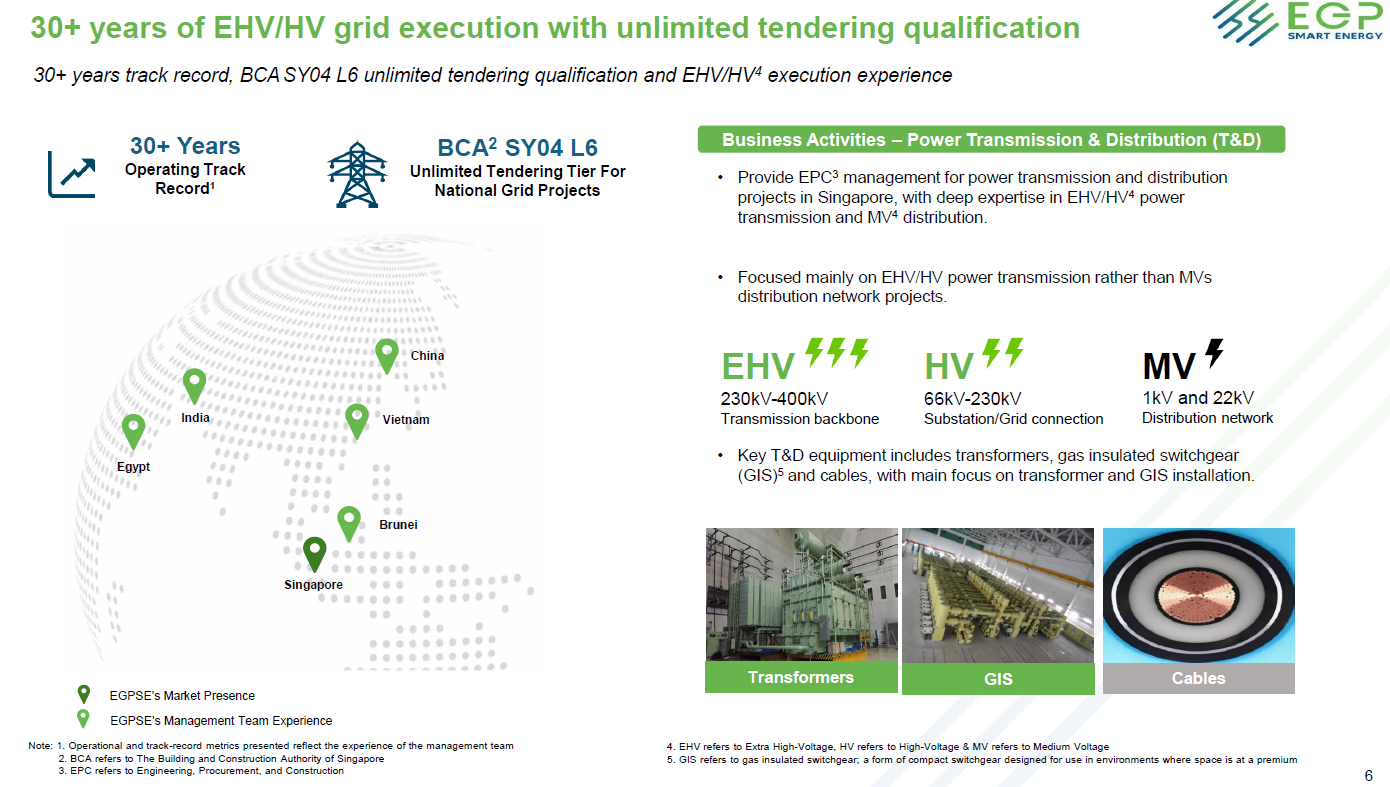
EGP holds the L6 SY04 workhead, which carries an unlimited tendering category. As at May 2026, only 16 firms held the L6 SY04 qualification.
The company also has more than 30 years of project experience and has worked on T&D projects spanning 400kV to 66kV.
EGP is the only local contractor capable of delivering 230 kV and above solutions. Its track record includes a 400kV substation project in Singapore.
The company's competitive positioning is therefore based on more than simply installation capacity. Its ability to integrate equipment from multiple OEMs provides greater flexibility in project execution.
It needs to maintain the relevant contractor qualifications, meet stringent technical and safety requirements, use approved equipment and demonstrate a track record of successfully delivering complex projects.
These factors can make customer relationships and project execution experience important competitive advantages.
Customer profile
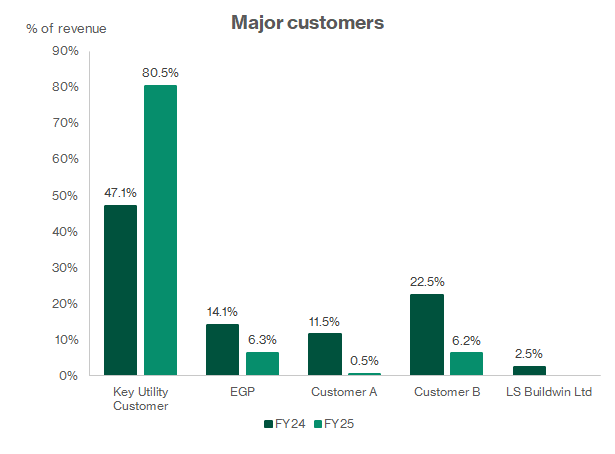
EGP's exposure to the Key Utility Customer has increased to 80.5% in FY25. The Top 3 customers account for 93% of revenue in FY25. This concentration reflects the nature of the Singapore T&D industry.
The weights will start to diversify when EGP gradually expand into the ASEAN region.
Long-duration order book provides earnings visibility till 2031
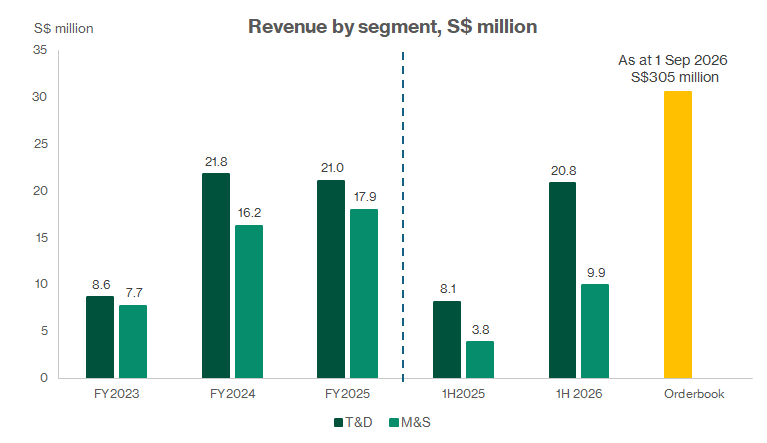
On 1 September, it announced another T&D contract worth S$6.2m, taking the order book to approximately S$305.1m as at that date. At S$305m, the order book is equivalent to approximately 7.8x FY25 revenue.
The orderbook provides earnings visibility with contacts scheduled for progressive completion through 2031. We would watch EGP’s execution in converting the existing order book into revenue and cash flow while maintaining project margins.
Strategy
Expand maintenance and intelligent technology capabilities
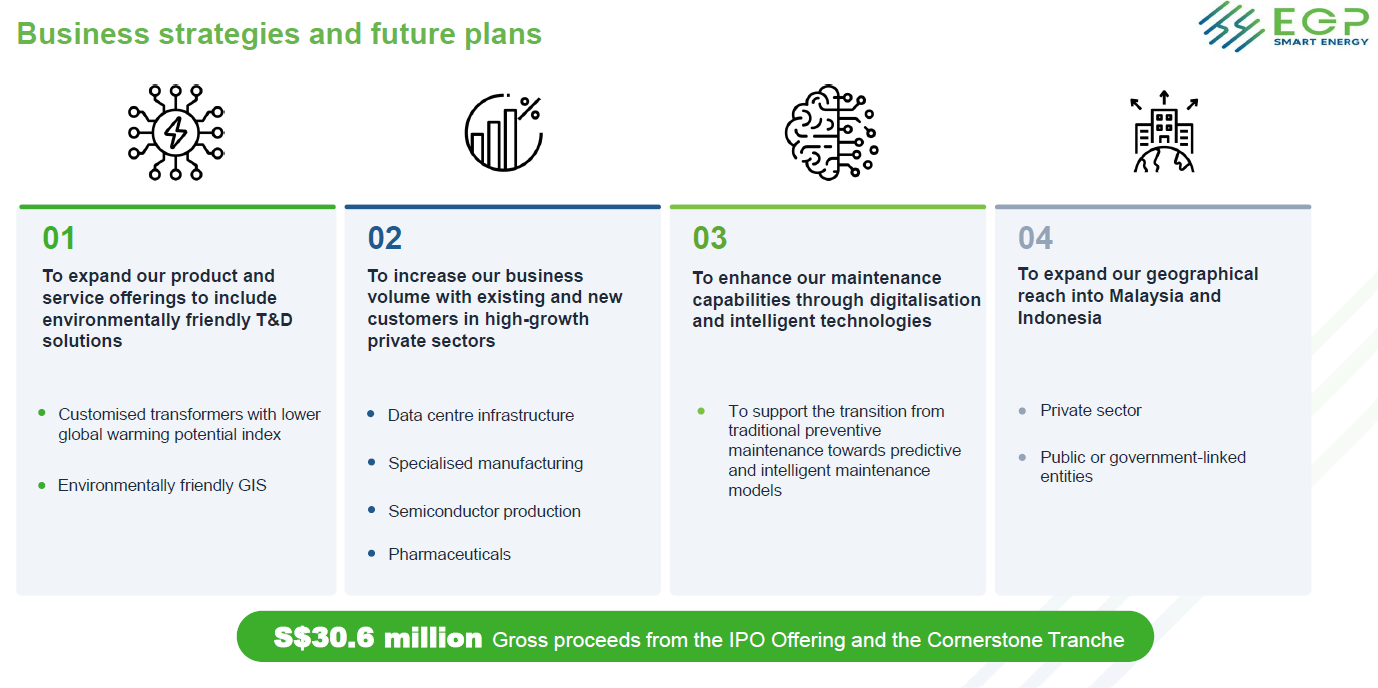
EGP Energy intends to use approximately S$15.0m of gross IPO proceeds to expand product offerings and its customer base, while enhancing maintenance services, digitalisation and intelligent technologies.
This is strategically relevant given the ageing of Singapore's grid infrastructure and the increasing need for inspection, diagnostics and asset maintenance.
Expansion into new markets
The Group intends to expand its geographical footprint into Malaysia and Indonesia, with approximately S$8.0m of gross proceeds earmarked for this purpose.
EGP has begun executing on its overseas expansion strategy.
In September, it entered into a joint venture with Kum Fatt Engineering, a subsidiary of Malaysia-listed UUE Holdings Berhad. EGP Energy will hold 60% of the JV, which will target EHV power grid infrastructure projects in Malaysia, including transformers, switchgear and cables up to 500kV.
The move provides EGP with a local partner and platform to pursue Malaysia's grid investment cycle. EGP’s near-term focus is on Malaysia data centre (DC) projects. The tender sizes of these DC projects have grown 3 to 5 times versus 2022-2023 levels.
For now, however, we would not include a material earnings contribution from Malaysia in our base-case forecasts. The JV is strategically interesting, but the financial contribution remains uncertain at this stage.
Target private-sector growth
Beyond Singapore's traditional utility market, EGP Energy plans to increase its business volume with high-growth private-sector industries including data centres; specialised manufacturing; semiconductors; and pharmaceuticals.
These facilities have significant electricity requirements and typically require dedicated T&D infrastructure connecting the facility to the grid.
Industry outlook
The industry's growth outlook is supported by several structural drivers.
Singapore's grid investment cycle supports demand
Singapore's highest transmission voltage is 400 kV, followed by 230 kV and 66 kV; distribution voltages are 22 kV, 1 kV, and 400 V, with all power cables running underground rather than overhead.
Singapore's electricity demand is projected to grow at a CAGR of 2.8% to 4.7% between 2025 and 2030, driven by advanced manufacturing, data centres and transport electrification.
At the same time, parts of Singapore's existing grid infrastructure are approaching their design life, creating demand for asset renewal and replacement.
The Future Grid Capabilities Roadmap is expected to drive new substations, transformer replacement and smart monitoring systems.
Data centres and semiconductors add to the demand pool
The growth in electricity-intensive industries is particularly relevant for EGP Energy.
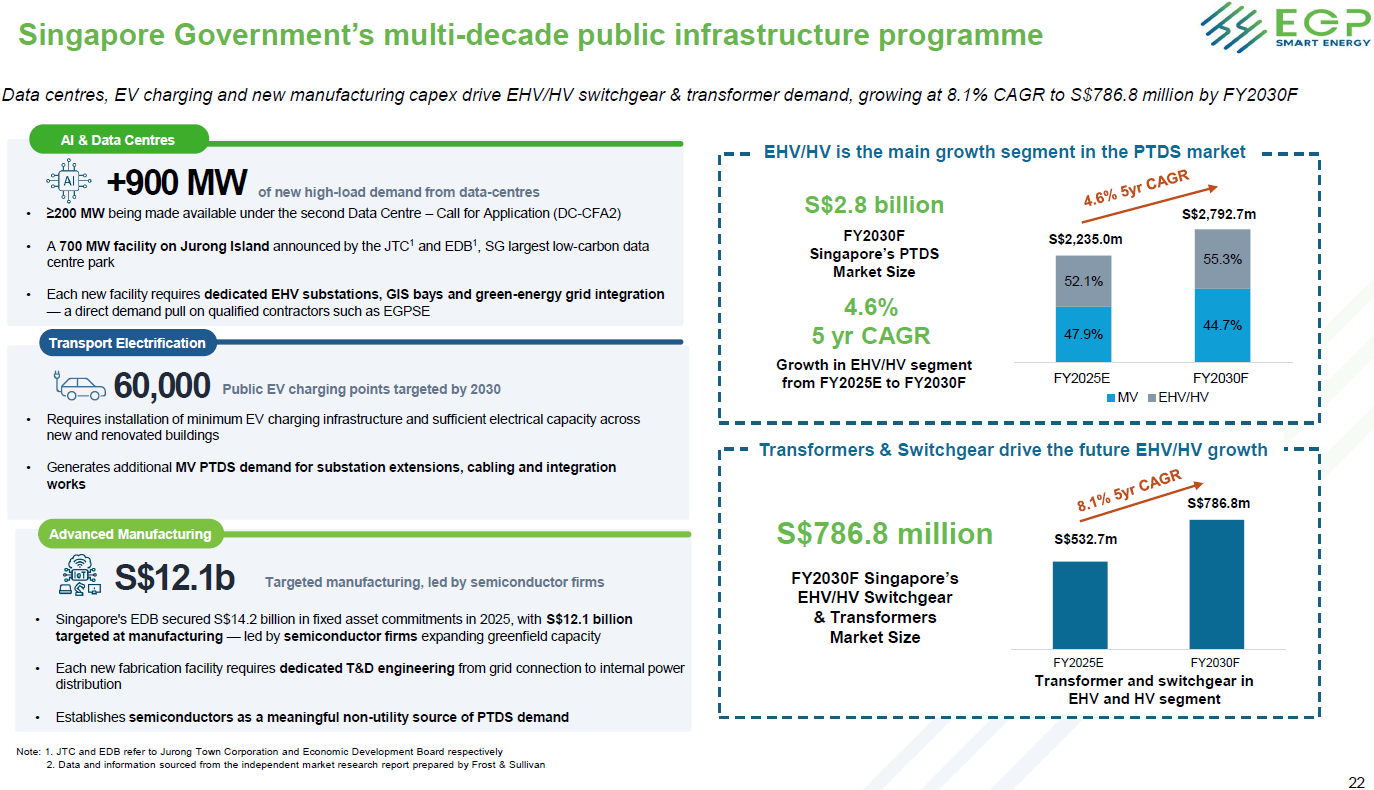
The prospectus highlights up to 900MW of additional high-load demand from data centres and cloud computing facilities.
Singapore also secured S$14.2bn of fixed asset investment commitments in 2025, with S$12.1bn targeted at manufacturing. Semiconductor projects account for a significant portion of this investment.
New facilities require T&D infrastructure from the grid connection point through to internal power distribution.
The implication is that EGP Energy does not need electricity consumption growth to translate one-for-one into its revenue. New capacity additions, grid reinforcement and private-sector connections can generate project opportunities even when underlying electricity demand grows at a more moderate rate.
Market size to grow at 8.1% CAGR during the period 2025 – 2030
Frost & Sullivan estimates Singapore's PTDS market at S$2.79bn by 2030, representing a 4.6% CAGR from 2025. This provides a sustained demand runway for EGP’s EHV/HV switchgear and transformer business
The higher-value EHV/HV switchgear and transformer market is expected to grow faster, reaching S$786.8m by 2030, representing an 8.1% CAGR.
This is relevant because EGP Energy's capabilities are concentrated in these higher-voltage applications.
The equipment mix is also expected to shift towards switchgears and transformers as Singapore invests in new 400kV and 230kV substations, replaces ageing transformers and develops infrastructure for cross-border electricity imports.
EHV and HV switchgear and transformers (excluding cables) represent a distinct and significant sub-segment, characterised by high unit values, stringent technical and regulatory requirements. This EHV and HV switchgear and transformer market was S$532.7 million in 2025. Frost & Sullivan forecast this segment to reach S$786.8 million by 2030, at a CAGR of 8.1%.
Key strengths
Established track record
EGP Energy has operated in Singapore's T&D market for more than 30 years, with a track record of projects dating back to 1998.
Its experience provides a reference base when competing for technically complex and regulated infrastructure projects.
High contractor qualification
The Group holds the L6 SY04 workhead, allowing unlimited tendering within the relevant T&D category.
The qualification is important because the Singapore T&D market has stringent prequalification requirements. Only 16 firms held the BCA L6 SY04 qualification as of May 2026, giving EGP Energy access to large-scale transmission projects with unlimited tendering limits.
Multi-OEM integration capability
EGP Energy can integrate equipment from multiple original equipment manufacturers, allowing it to act as a single project-management interface rather than relying on a single equipment supplier.
This is particularly relevant for complex substations involving GIS, transformers, cables, protection systems and control systems.
Long-standing customer relationships
The Group has worked with its Key Utility Customer since 1998 and has continued to secure projects from the customer.
The relationship provides recurring access to a substantial pipeline of T&D projects, although it simultaneously creates significant customer-concentration risk.
Strong demand visibility and improving cash conversion
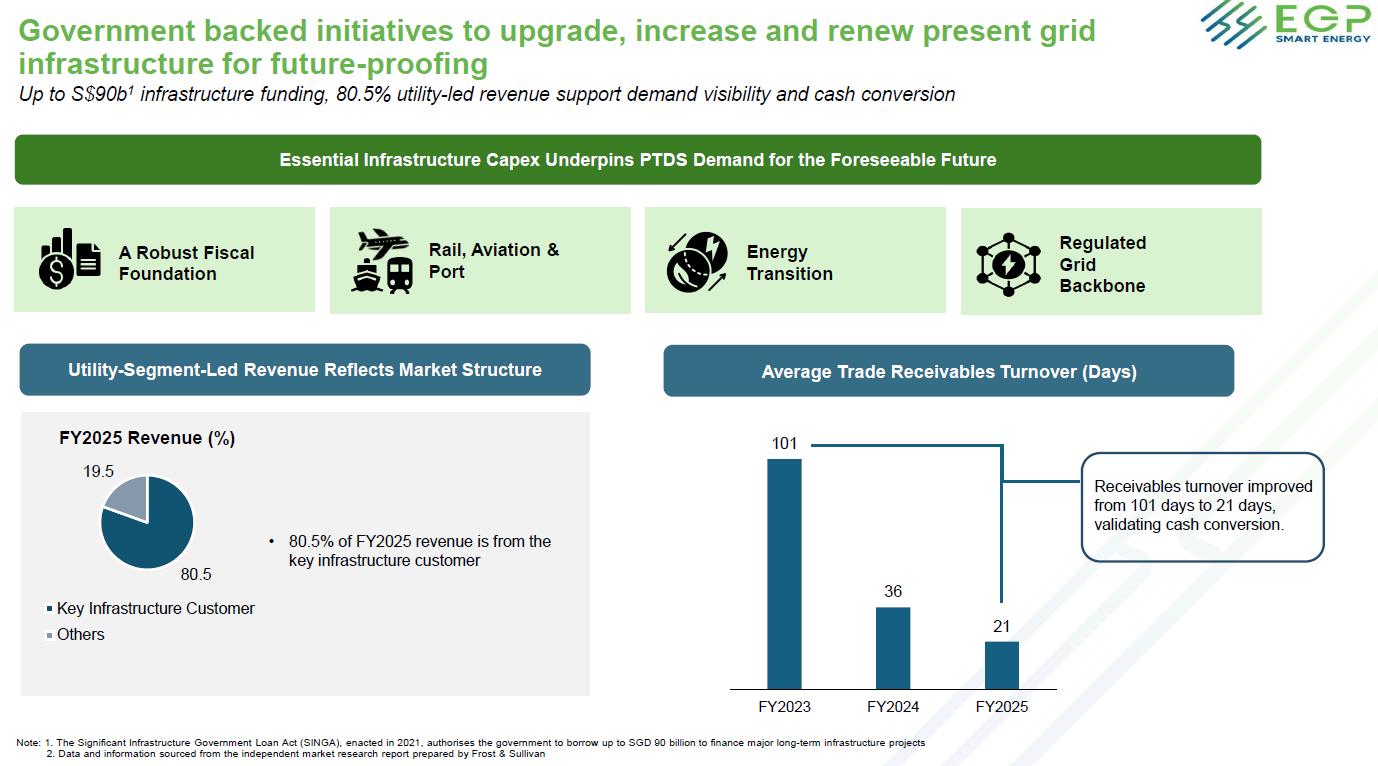
Government-backed infrastructure spending provides long-term demand visibility, with up to S$90bn of infrastructure funding supporting PTDS demand.
EGP’s strong exposure to key infrastructure customers, which contributed 80.5% of FY2025 revenue, provides further visibility.
Meanwhile, average receivables turnover improved significantly from 101 days in FY2023 to 21 days in FY2025, demonstrating stronger working capital management and cash conversion.
Financial performance
Revenue and profitability
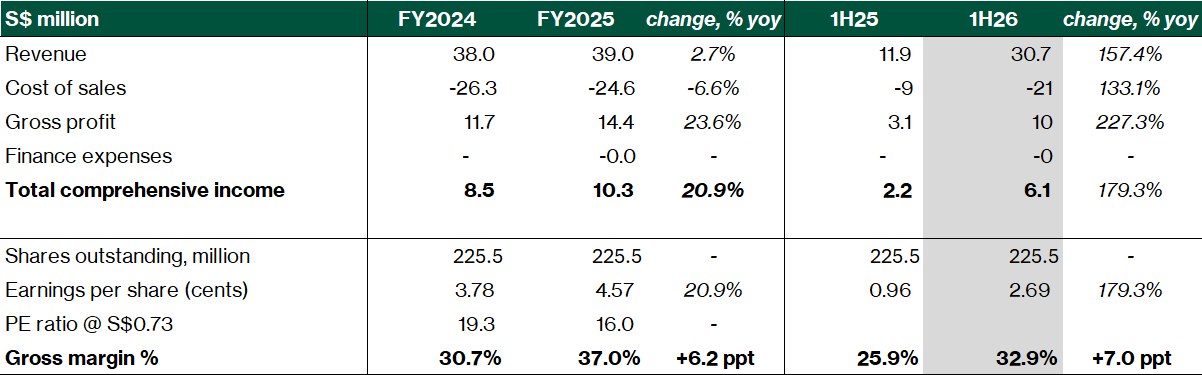
EGP reported FY2025 revenue of S$39.0 million, representing a 2.7% year-on-year increase from FY2024. The higher revenue was mainly attributed to increase in revenue from M&S projects.
FY2025 cost of sales fell 6.6% year-on-year to S$24.6 million, led by decrease in procurement of equipment.
Gross margin improved to 37% in FY2025, up 6.2 percentage point..
1H26 was a strong period for EGP Energy.
Revenue increased 157.4% YoY to S$30.7m, driven by higher contributions from both T&D and M&S projects.
T&D revenue increased 156.3% to S$20.8m, while M&S revenue increased 159.8% to S$9.9m.
Gross profit increased 227.3% to S$10.1m and gross margin expanded from 25.9% to 32.9%.
Management attributed the margin improvement partly to a roughly S$2m increase in ad-hoc services, which generally command higher margins.
Net profit attributable to shareholders increased 179.7% to S$6.1m.
Importantly, 1H26 included S$0.9m of listing expenses. Excluding the non-recurring IPO-related expenses, adjusted net profit was approximately S$7.0m, with an adjusted net margin of 23.0%.
Capital management
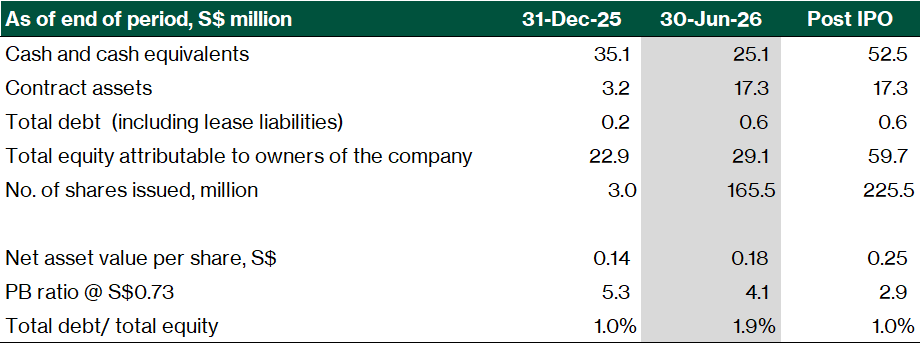
As of 31 December 2025, EGP held S$29.9 million in cash and bank balances. EGP does not have any external debt or outstanding bank loans.
The group's equity base of S$22.9 million as at 31 December 2025, increased to S$59.7 million post-IPO.
Post IPO, including the net IPO proceeds of S$27.4 million, EGP held Cash and fixed deposits S$47.4 million.
Cash flow adequacy
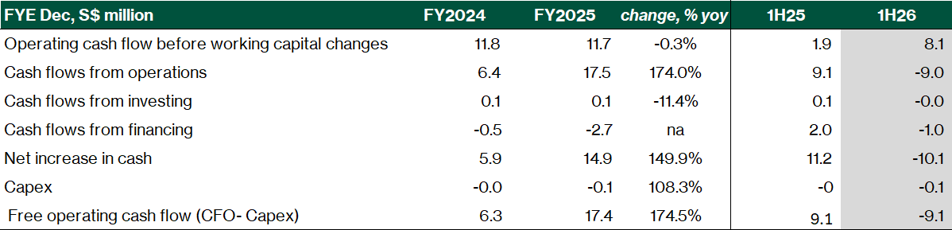
EGP generated strong operating cash flow in FY2025, at S$17.5 million, increased by 174.0% year-on-year.
EGP generated positive free operating cash flow in FY2025, at S$17.4 million, an increase of 174.5% year-on-year.
For 1H26, EGP recorded negative S$9.0 million in operating cash flows. This was due to the higher working capital requirement absorbed by the higher level of project activities with approximately S$14.0 million build-up in contract assets on projects billed after period end.
Otherwise, operating cash flows before working capital changes was S$8.1 million in 1H26, significantly higher than S$1.9 million recorded in 1H25.
The main area we would monitor is working capital.
Despite the strong earnings performance, EGP Energy generated negative S$9.0m operating cash flow in 1H26, versus positive S$9.1m in 1H25.
The key reason was the S$14.0m increase in contract assets as revenue recognised exceeded progress billings at the period end. Management expects these amounts to be billed and collected in 2H26.
This is not necessarily a sign of deteriorating underlying economics. In a project-based business, revenue recognition can precede billing milestones.
But it does mean that cash conversion should be an important KPI for investors.
If contract assets convert into receivables and then cash as expected, the 1H26 working-capital drag should reverse. If project execution continues to consume working capital as the order book expands, however, reported earnings could continue to run ahead of cash flow.
Valuation
EGP trades at a lower valuation multiple compared with its Malaysian electrical infrastructure peers, while offering a broadly comparable profitability profile.
At 13.2x FY26E PE, EGP is valued at a discount to the 15.0x average of MN Holdings and Chee Holdings. This compares with EGP Energy’s 20.0% EBITDA margin, versus the Malaysian peer average of 23.2%.
The valuation discount therefore appears reasonable given EGP’s smaller scale and relatively shorter listed track record, although its strong market position in Singapore’s high-voltage switchgear and transformer market provides some differentiation.
The comparison with the Indian peers is less meaningful on a direct valuation basis. GE Vernova T&D India, Hitachi Energy India and Siemens Energy India trade at an average 75.9x FY26E PE, substantially above EGP Energy's 13.2x.
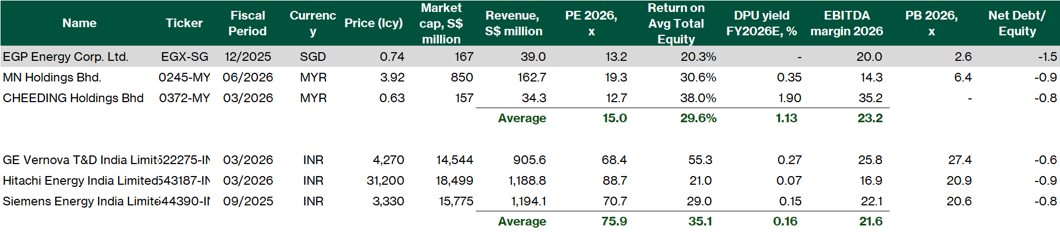
While these companies have exposure to similar power transmission and distribution themes, they are significantly larger businesses with much higher market capitalisations and greater scale. Their premium valuations also reflect stronger growth expectations and exposure to the broader electrification and grid investment cycle. We therefore view the Malaysian peer group as the more relevant valuation benchmark for EGP Energy.
Within the Malaysian peer group, MN Holdings is the closest listed comparable, given its focus on power infrastructure, substations and underground utilities. MN Holdings has also benefited significantly from Malaysia's data-centre driven demand for power infrastructure, with its FY26 revenue rising 61% and net profit increasing 93%.
EGP has a somewhat different business mix, with greater exposure to EHV/HV switchgear, transformers and electrical equipment, alongside engineering and maintenance services.
This gives EGP a more equipment-oriented exposure to the power T&D value chain, rather than being primarily an infrastructure contractor.
EGP’s dividend policy, targeting a payout ratio of up to 40%, will be finalised by year-end.
Key risks
Key risks include customer concentration, related-party arrangements, project execution, working capital and margin volatility.
Customer concentration
The Key Utility Customer accounted for 80.5% of FY25 revenue, up from 47.1% in FY24.
Approximately S$239m of the company's S$282.1m order book, equivalent to 85%, at the prospectus date was also associated with this customer.
The concentration is partly a reflection of EGP Energy's position in Singapore's regulated electricity T&D market, where the national grid has a dominant utility operator.
Nevertheless, any reduction in tender awards, project delays or changes in procurement terms could materially affect earnings.
Related-party / legacy EGP arrangements
Certain historical T&D subcontracting arrangements involve EGP, which is associated with the Group's controlling shareholders.
While the prospectus states that the arrangements are expected to cease post-listing except for existing arrangements and specified future arrangements, investors should monitor the transition and potential conflicts of interest.
Project execution and margin risk
Revenue is recognised over time based on project progress. Project costs, procurement prices, subcontractor costs and project delays can therefore affect both revenue recognition and margins.
This is particularly relevant because T&D projects tend to be larger but lower-margin than M&S projects.
Working capital
The 1H26 negative operating cash flow demonstrates the potential mismatch between accounting revenue and cash collection.
Contract assets rose by around S$14m in 1H26. We would want to see this unwind into billings and cash collection in 2H26.
Margin normalisation
The 32.9% gross margin in 1H26 was helped by higher-margin ad-hoc services. If the revenue mix shifts towards large T&D projects, group margins could decline.
Overseas expansion
Malaysia provides a new avenue for growth, but overseas expansion introduces new execution, regulatory and customer risks. We would watch for greater visibility on contract wins.
Download the full report here.
Check out Beansprout guide to the best stock trading platforms in Singapore with the latest promotions to invest in JustCo Holdings Limited.
Join the Beansprout Telegram group for the latest insights on Singapore stocks, REITs, bonds and ETFs.
Important Disclosures
Analyst Certification and Disclosures
The analyst(s) named in this report certifies that (i) all views expressed in this report accurately reflect the personal views of the analyst(s) with regard to any and all of the subject securities and companies mentioned in this report and (ii) no part of the compensation of the analyst(s) was, is, or will be, directly or indirectly, related to the specific views expressed by that analyst herein. The analyst(s) named in this report (or their associates) does not have a financial interest in the corporation(s) mentioned in this report.
An associate is defined as (i) the spouse, or any minor child (natural or adopted) or minor step-child, of the analyst; (ii) the trustee of a trust of which the analyst, his spouse, minor child (natural or adopted) or minor step-child, is a beneficiary or discretionary object; or (iii) another person accustomed or obliged to act in accordance with the directions or instructions of the analyst.
Company Disclosure
Global Wealth Technology Pte Ltd (“Beansprout”) does not have any financial interest in the corporation(s) mentioned in this report.
Disclaimer
This report is provided by Beansprout for the use of intended recipients only and may not be reproduced, in whole or in part, or delivered or transmitted to any other person without our prior written consent. By accepting this report, the recipient agrees to be bound by the terms and limitations set out herein.
You acknowledge that this document is provided for general information purposes only. Nothing in this document shall be construed as a recommendation to purchase, sell, or hold any security or other investment, or to pursue any investment style or strategy. Nothing in this document shall be construed as advice that purports to be tailored to your needs or the needs of any person or company receiving the advice. The information in this document is intended for general circulation only and does not constitute investment advice. Nothing in this document is published with regard to the specific investment objectives, financial situation and particular needs of any person who may receive the information.
Nothing in this document shall be construed as, or form part of, any offer for sale or subscription of or solicitation or invitation of any offer to buy or subscribe for any securities. The data and information made available in this document are of a general nature and do not purport, and shall not in any way be deemed, to constitute an offer or provision of any professional or expert advice, including without limitation any financial, investment, legal, accounting or tax advice, and shall not be relied upon by you in that regard. You should at all times consult a qualified expert or professional adviser to obtain advice and independent verification of the information and data contained herein before acting on it. Any financial or investment information in this document are intended to be for your general information only. You should not rely upon such information in making any particular investment or other decision which should only be made after consulting with a fully qualified financial adviser. Such information do not nor are they intended to constitute any form of financial or investment advice, opinion or recommendation about any investment product, or any inducement or invitation relating to any of the products listed or referred to. Any arrangement made between you and a third party named on or linked to from these pages is at your sole risk and responsibility.
You acknowledge that Beansprout is under no obligation to exercise editorial control over, and to review, edit or amend any data, information, materials or contents of any content in this document. You agree that all statements, offers, information, opinions, materials, content in this document should be used, accepted and relied upon only with care and discretion and at your own risk, and Beansprout shall not be responsible for any loss, damage or liability incurred by you arising from such use or reliance.
This document (including all information and materials contained in this document) is provided “as is”. Although the material in this document is based upon information that Beansprout considers reliable and endeavours to keep current, Beansprout does not assure that this material is accurate, current or complete and is not providing any warranties or representations regarding the material contained in this document. All opinions contained herein constitute the views of the analyst(s) named in this report, they are subject to change without notice and are not intended to provide the sole basis of any evaluation of the subject securities and companies mentioned in this report. Any reference to past performance should not be taken as an indication of future performance. To the fullest extent permissible pursuant to applicable law, Beansprout disclaims all warranties and/or representations of any kind with regard to this document, including but not limited to any implied warranties of merchantability, non-infringement of third-party rights, or fitness for a particular purpose.
Beansprout does not warrant, either expressly or impliedly, the accuracy or completeness of the information, text, graphics, links or other items contained in this document. Neither Beansprout nor any of its affiliates, directors, employees or other representatives will be liable for any damages, losses or liabilities of any kind arising out of or in connection with the use of this document. To the best of Beansprout’s knowledge, this document does not contain and is not based on any non-public, material information. The information in this document is not intended for distribution to, or use by, any person or entity in any jurisdiction where such distribution or use would be contrary to law or regulation, or which would subject Beansprout to any registration requirement within such jurisdiction or country. Beansprout is not licensed or regulated by any authority in any jurisdiction or country to provide the information in this document.
As a condition of your use of this document, you agree to indemnify, defend and hold harmless Beansprout and its affiliates, and their respective officers, directors, employees, members, managing members, managers, agents, representatives, successors and assigns from and against any and all actions, causes of action, claims, charges, cost, demands, expenses and damages (including attorneys’ fees and expenses), losses and liabilities or other expenses of any kind that arise directly or indirectly out of or from, arising out of or in connection with violation of these terms, use of this document, violation of the rights of any third party, acts, omissions or negligence of third parties, their directors, employees or agents. To the extent permitted by law, Beansprout shall not be liable to you, any other person, or organization, for any direct, indirect, special, punitive, exemplary, incidental or consequential damages, whether in contract, tort (including negligence), or otherwise, arising in any way from, or in connection with, the use of this document and/or its content. This includes, without limitation, liability for any act or omission in reliance on the information in this document. Beansprout expressly disclaims and excludes all warranties, conditions, representations and terms not expressly set out in this User Agreement, whether express, implied or statutory, with regard to this document and its content, including any implied warranties or representations about the accuracy or completeness of this document and the content, suitability and general availability, or whether it is free from error.
If these terms or any part of them is understood to be illegal, invalid or otherwise unenforceable under the laws of any state or country in which these terms are intended to be effective, then to the extent that they are illegal, invalid or unenforceable, they shall in that state or country be treated as severed and deleted from these terms and the remaining terms shall survive and remain fully intact and in effect and will continue to be binding and enforceable in that state or country.
These terms, as well as any claims arising from or related thereto, are governed by the laws of Singapore without reference to the principles of conflicts of laws thereof. You agree to submit to the personal and exclusive jurisdiction of the courts of Singapore with respect to all disputes arising out of or related to this Agreement. Beansprout and you each hereby irrevocably consent to the jurisdiction of such courts, and each Party hereby waives any claim or defence that such forum is not convenient or proper.
Read also
Gain financial insights in minutes
Subscribe to our free weekly newsletter for more insights to grow your wealth
Most Popular

Comments
0 comments