
Centurion Accommodation REIT - 9M 2026 results ahead of IPO forecast
REITs
By Gerald Wong, CFA • 11 Nov 2026
Global Wealth Technology Pte. Ltd. is regulated by the Monetary Authority of Singapore (MAS) as a licensed Financial Adviser.

Make Beansprout your preferred source on Google
Add us on Google to see more of our insights in your search results
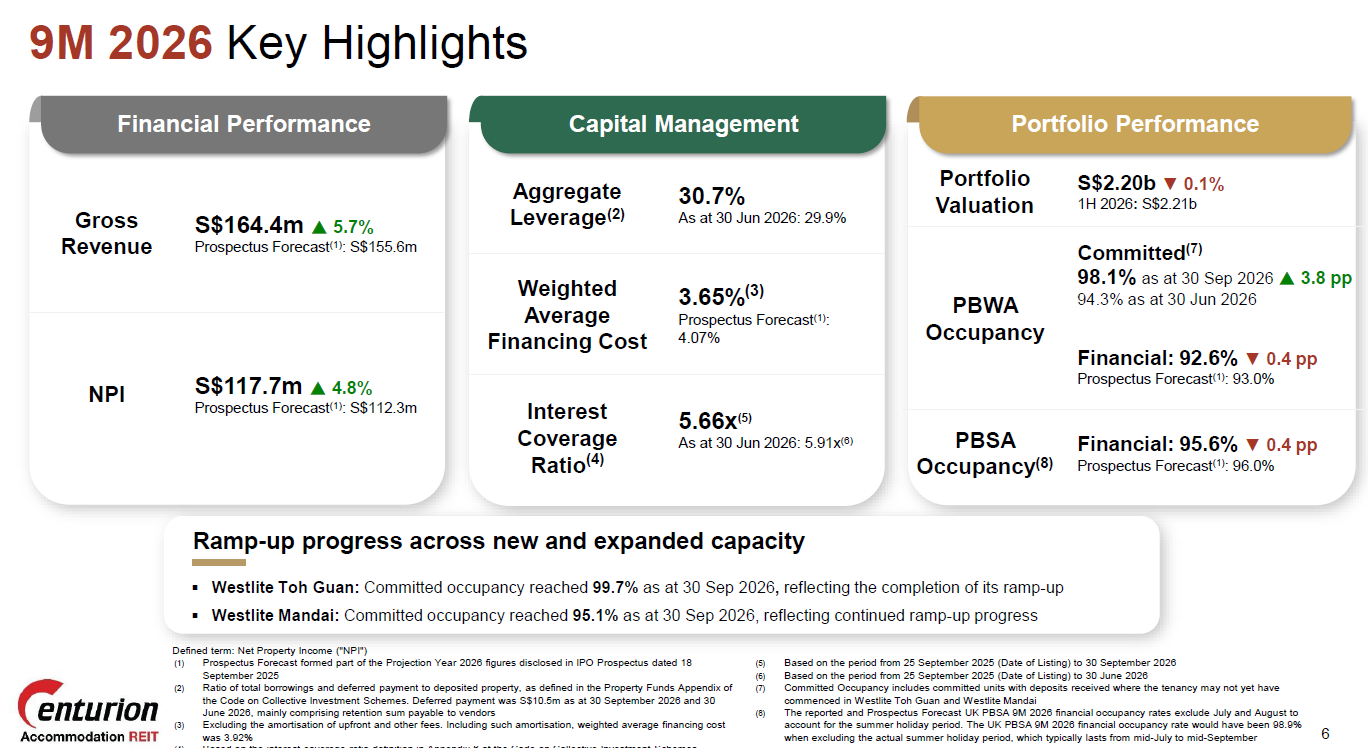
Centurion Accommodation REIT (CAREIT) reported gross revenue of S$164.4 million and NPI of S$117.7 million in 9M26, exceeded the prospectus forecast by 5.7% and 4.8%, respectively.
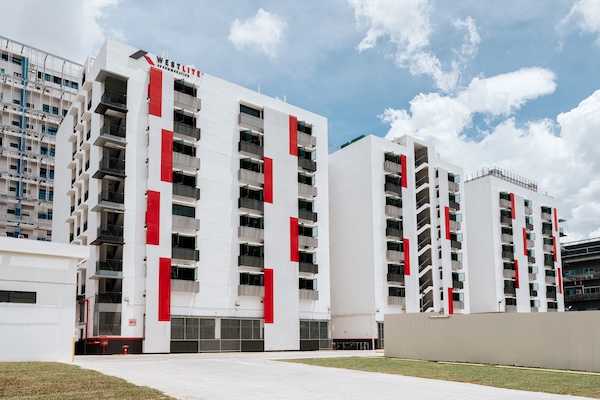
9M 2026 Revenue and NPI ahead of IPO Forecast
|
 |
Source: Centurion Accommodation REIT 9M26 business update |
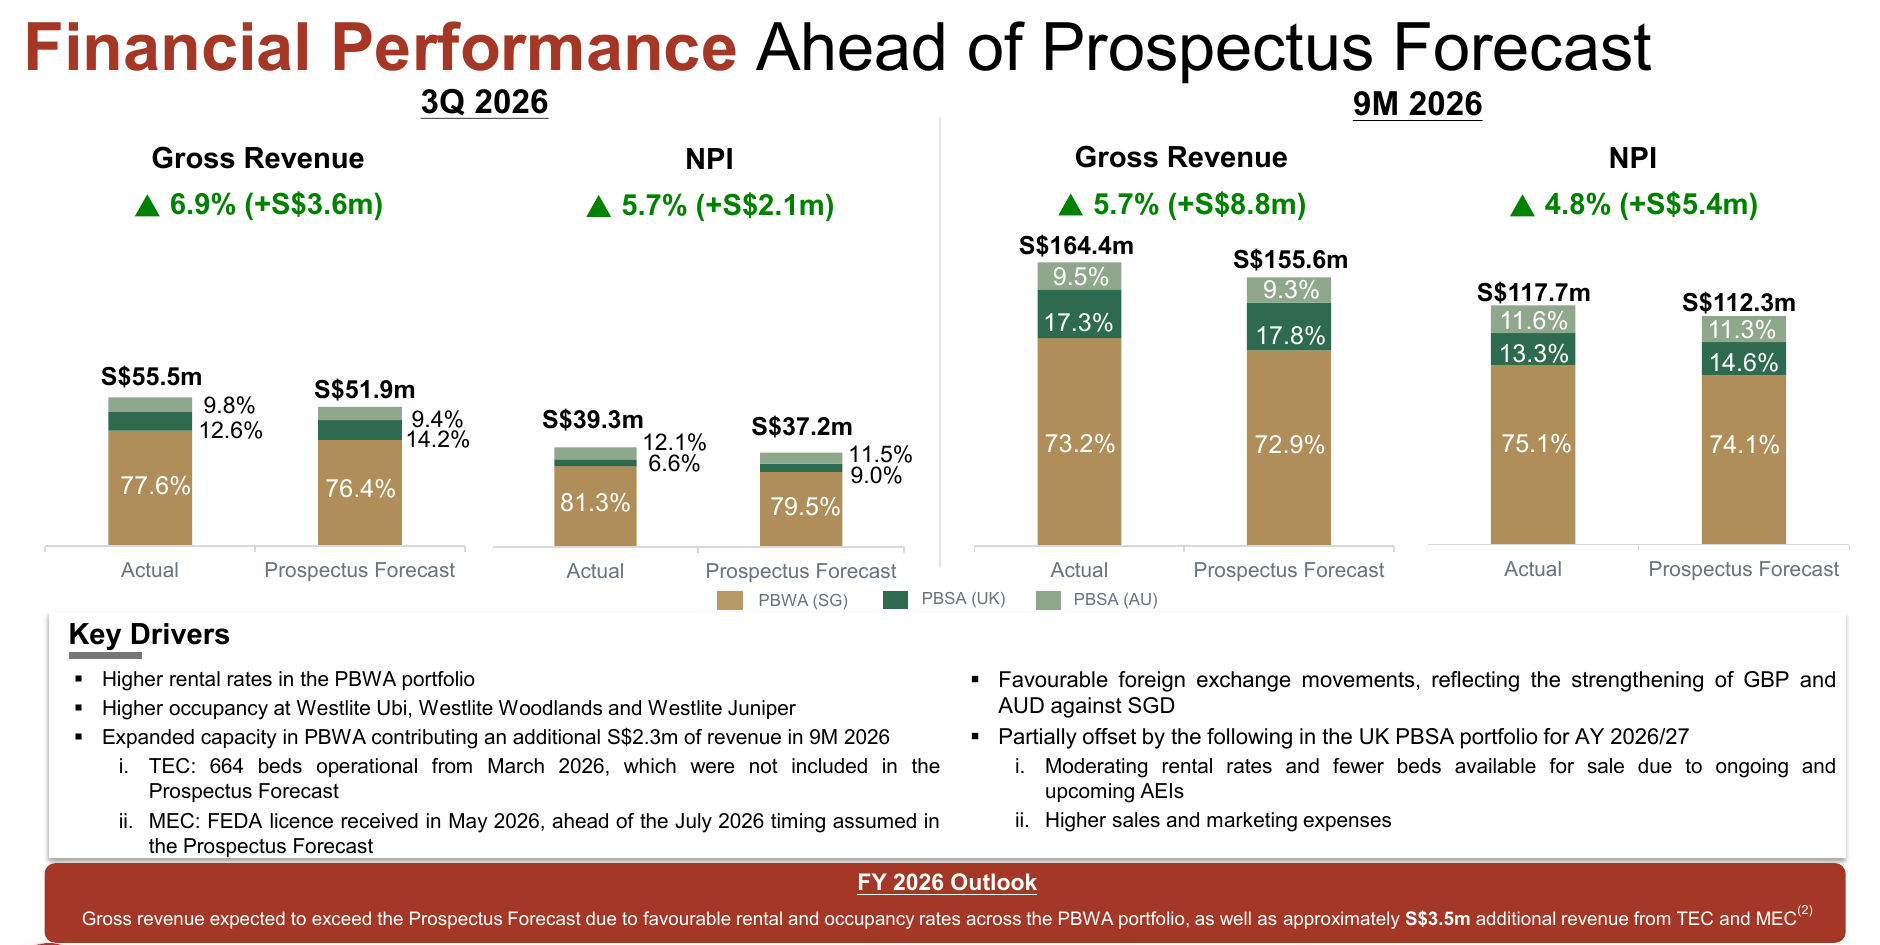
Centurion Accommodation REIT (CAREIT) reported gross revenue of S$55.5 million and net property income (NPI) of S$39.3 million in 3Q 2026, 6.9% and 5.7% above its IPO prospectus forecast, respectively.
For 9M 2026, gross revenue of S$164.4 million and NPI of S$117.7 million exceeded the prospectus forecast by 5.7% and 4.8%, respectively.
|
 |
Source: Centurion Accommodation REIT 9M26 business update |
The outperformance was mainly driven by higher rental rates across the Purpose-Built Worker Accommodation (PBWA) portfolio and higher occupancy at Westlite Ubi, Westlite Woodlands and Westlite Juniper.
The expanded capacity at Westlite Toh Guan and Westlite Mandai contributed an additional S$2.3 million of revenue in 9M 2026.
The 664 expanded capacity beds at Westlite Toh Guan, operational since March 2026, were not included in the prospectus forecast.
The licence for the expanded capacity at Westlite Mandai was received in May 2026, two months ahead of the July 2026 assumption.
The strengthening of the Australian dollar against the Singapore dollar also contributed to the outperformance. Year-to-date till 30 Sep 2026, the AUD appreciated 3.4% against SGD.
These were partly offset by the UK student accommodation portfolio, where rental rates moderated for academic year (AY) 2026/27. In addition, fewer beds were available for sale due to ongoing and upcoming asset enhancement works.
|
 |
Source: Centurion Accommodation REIT 9M26 business update |
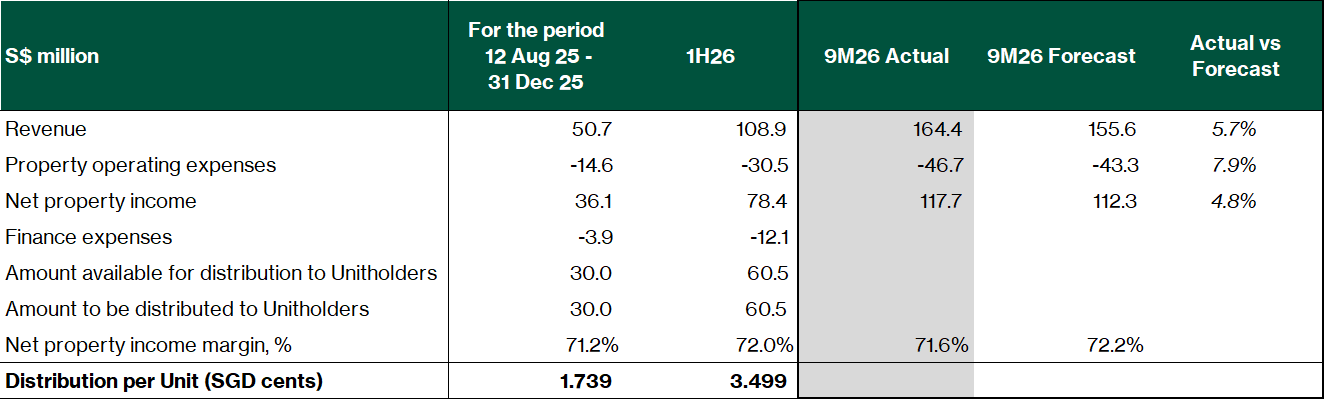
To recap, CAREIT’s 1H 2026 distribution per unit (DPU) of 3.499 cents was 9.6% above the prospectus forecast of 3.192 cents, helped by stronger NPI and lower finance costs.
Looking ahead, management expects FY2026 gross revenue to exceed the prospectus forecast.
The outperformance is supported by favourable PBWA rental and occupancy rates, as well as about S$3.5 million of additional revenue from the expanded capacity at Westlite Toh Guan and Westlite Mandai.
 |
Source: Centurion Accommodation REIT data |
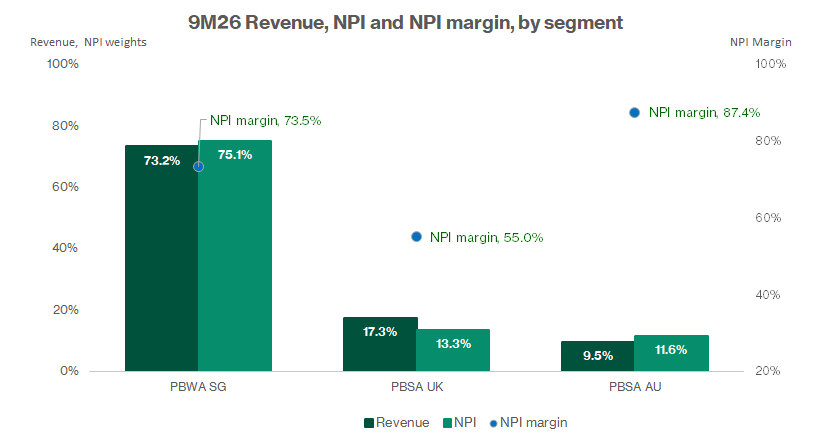
PBWA remained the key earnings driver, contributing 73.2% of 9M26 gross revenue and 75.1% of NPI.
In 3Q 2026, the PBWA portfolio generated S$43.0 million of revenue and S$31.9 million of NPI. The UK PBSA portfolio contributed S$7.0 million of revenue and S$2.6 million of NPI in 3Q 2026, reflecting the seasonally weaker summer quarter. The Australia PBSA portfolio contributed S$5.5 million of revenue and S$4.8 million of NPI.
Portfolio NPI margin was 70.8% in 3Q 2026 and 71.6% in 9M 2026, slightly below the 72.2% implied by the 9M 2026 prospectus forecast due to higher UK marketing expenses.
The PBWA portfolio benefits from electricity costs being contractually passed through to tenants, except for common areas.
In contrast, electricity costs at the UK and Adelaide PBSA assets are borne by CAREIT, although costs are managed through fixed-price contracts.
|
 |
Source: Centurion Accommodation REIT data |
PBWA ramp-up on track, committed occupancy rose to 98.1%
 |
Source : Centurion Accommodation REIT 9M26 business update |
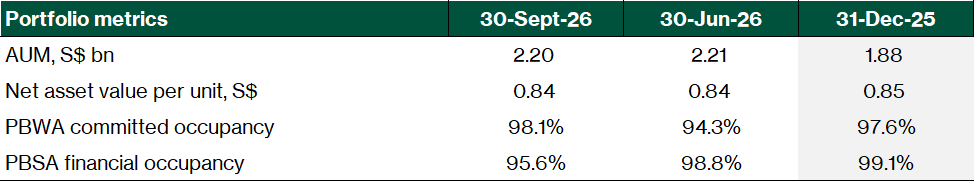
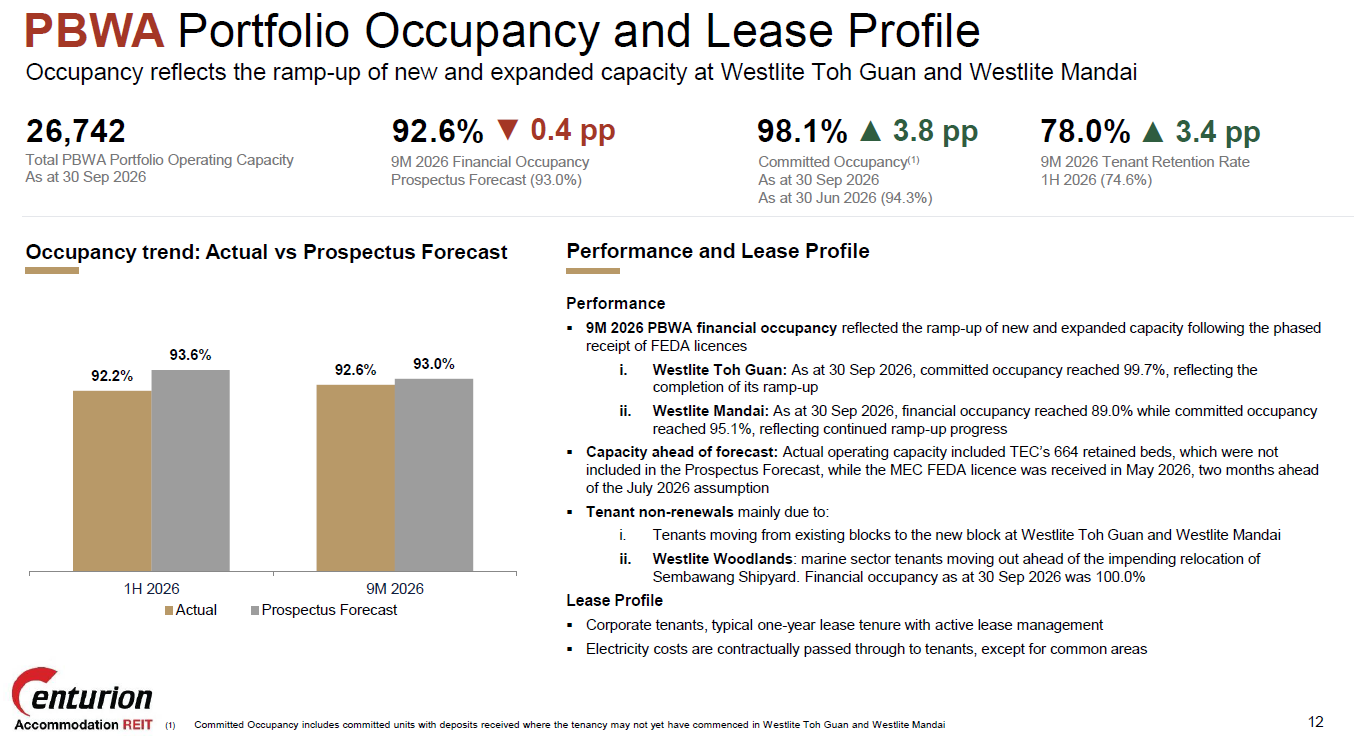
PBWA committed occupancy rose to 98.1% as at 30 September 2026, from 94.3% three months earlier, reflecting the ramp-up at Westlite Toh Guan and Westlite Mandai.
Financial occupancy was lower at 92.6%, as some tenants with committed units had yet to check in. We expect financial occupancy to improve as these tenants commence their leases.
Westlite Toh Guan reached committed occupancy of 99.7%, marking the completion of its ramp-up. Westlite Mandai reached committed occupancy of 95.1% and financial occupancy of 89.0%.
9M26 PBWA financial occupancy was 92.6%, slightly below the prospectus forecast of 93.0%, but higher than 92.2% in 1H 2026. With committed occupancy at 98.1%, we expect financial occupancy to catch up as tenants with committed units check in.
Tenant retention rate improved to 78.0% in 9M 2026, from 74.6% in 1H 2026. Non-renewals were mainly due to tenants moving from existing blocks to the new blocks at Westlite Toh Guan and Westlite Mandai. In addition, marine sector tenants were moving out of Westlite Woodlands ahead of the relocation of Sembawang Shipyard. Despite this, Westlite Woodlands’ financial occupancy was 100.0% as at 30 September 2026.
The PBWA tenant base is anchored by the construction sector (84%), supported by a strong pipeline of public and private projects such as Changi Airport Terminal 5 and the Marina Bay Sands expansion.
PBSA occupancy remained high, but UK rents moderated
|
 |
Source : Centurion Accommodation REIT 9M26 business update |
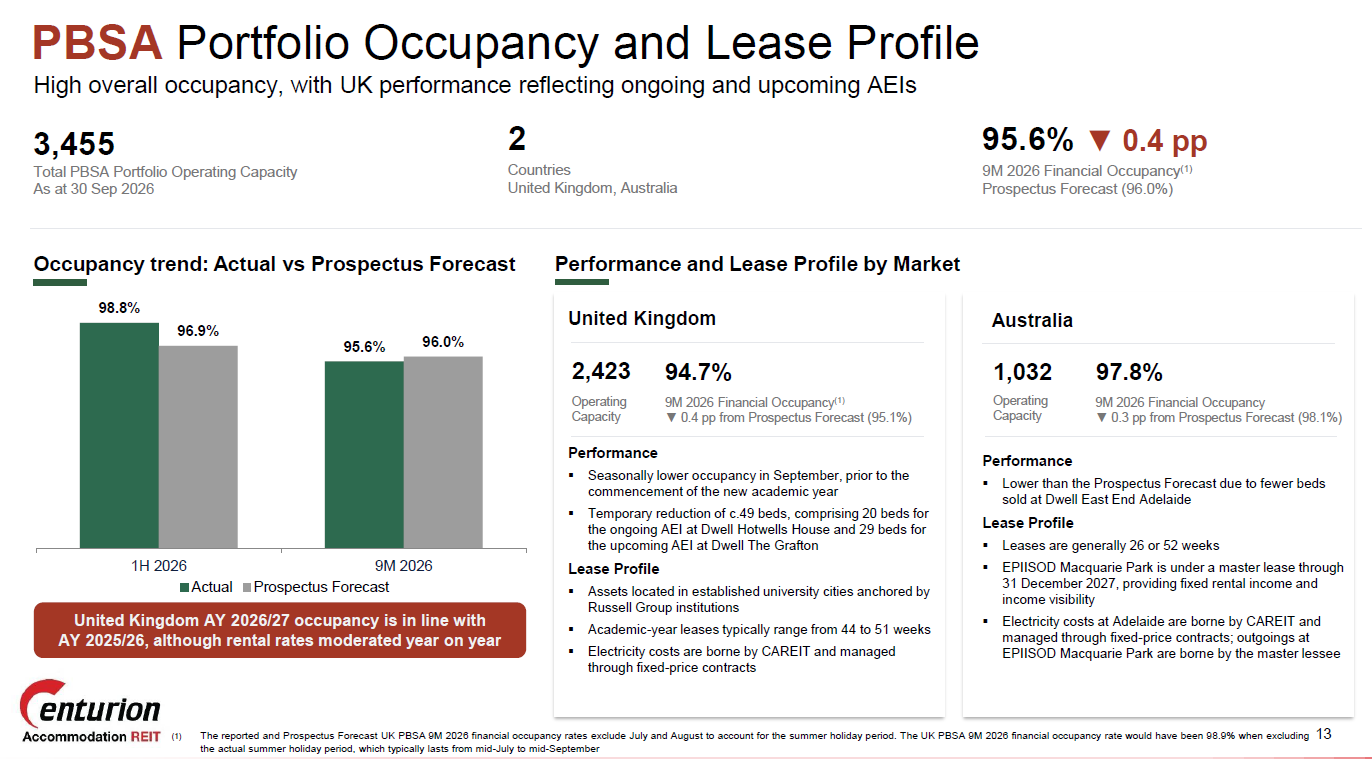
PBSA financial occupancy was 95.6% for 9M 2026, broadly in line with the prospectus forecast of 96.0%.
The UK portfolio recorded financial occupancy of 94.7% (forecast: 95.1%), while Australia recorded 97.8% (forecast: 98.1%).
In the UK, Academic Year (AY) 2026/27 occupancy was in line with AY 2025/26, but rental rates moderated year-on-year. This is consistent with the wider market, where UK PBSA rental growth slowed from 2.3% to 1.5% in AY 2026/27 amid affordability pressures.
Operating capacity was also temporarily reduced by about 49 beds for asset enhancement works at Dwell Hotwells House in Bristol and Dwell The Grafton in Manchester. Both are targeted for completion for AY 2027/28.
UK demand fundamentals remain supportive. Total applicants for AY 2026/27 rose 4.6% year-on-year to 695,740, led by UK 18-year-olds (+5.0%).
CAREIT’s eight UK assets are located in university cities anchored by Russell Group universities. About 70% of its UK residents are domestic students, which limits its exposure to tighter international student visa policies.
In Australia, financial occupancy was slightly below forecast due to fewer beds sold at Dwell East End Adelaide. The 732-bed EPIISOD Macquarie Park remains under a master lease with the vendor until 31 December 2027, providing fixed rental income of A$14.1 million for FY2026 and A$20.0 million for FY2027.
Prudent capital management with no debt maturing until 2028
|
|
Source: Centurion Accommodation REIT 9M26 business update |
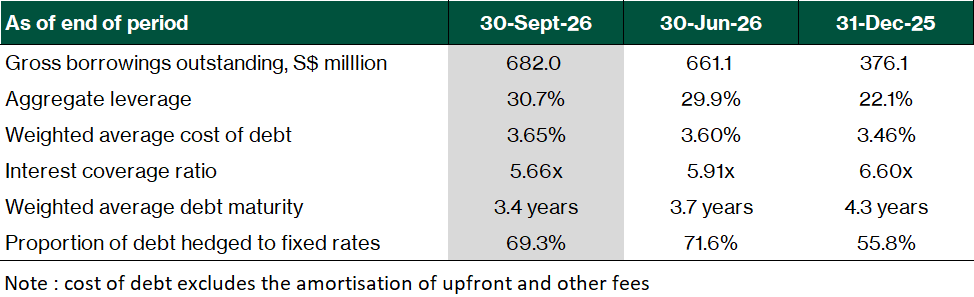
As at 30 September 2026, aggregate leverage edged up to 30.7% from 29.9% as at 30 June 2026, as gross borrowings rose to S$682.0 million from S$661.1 million.
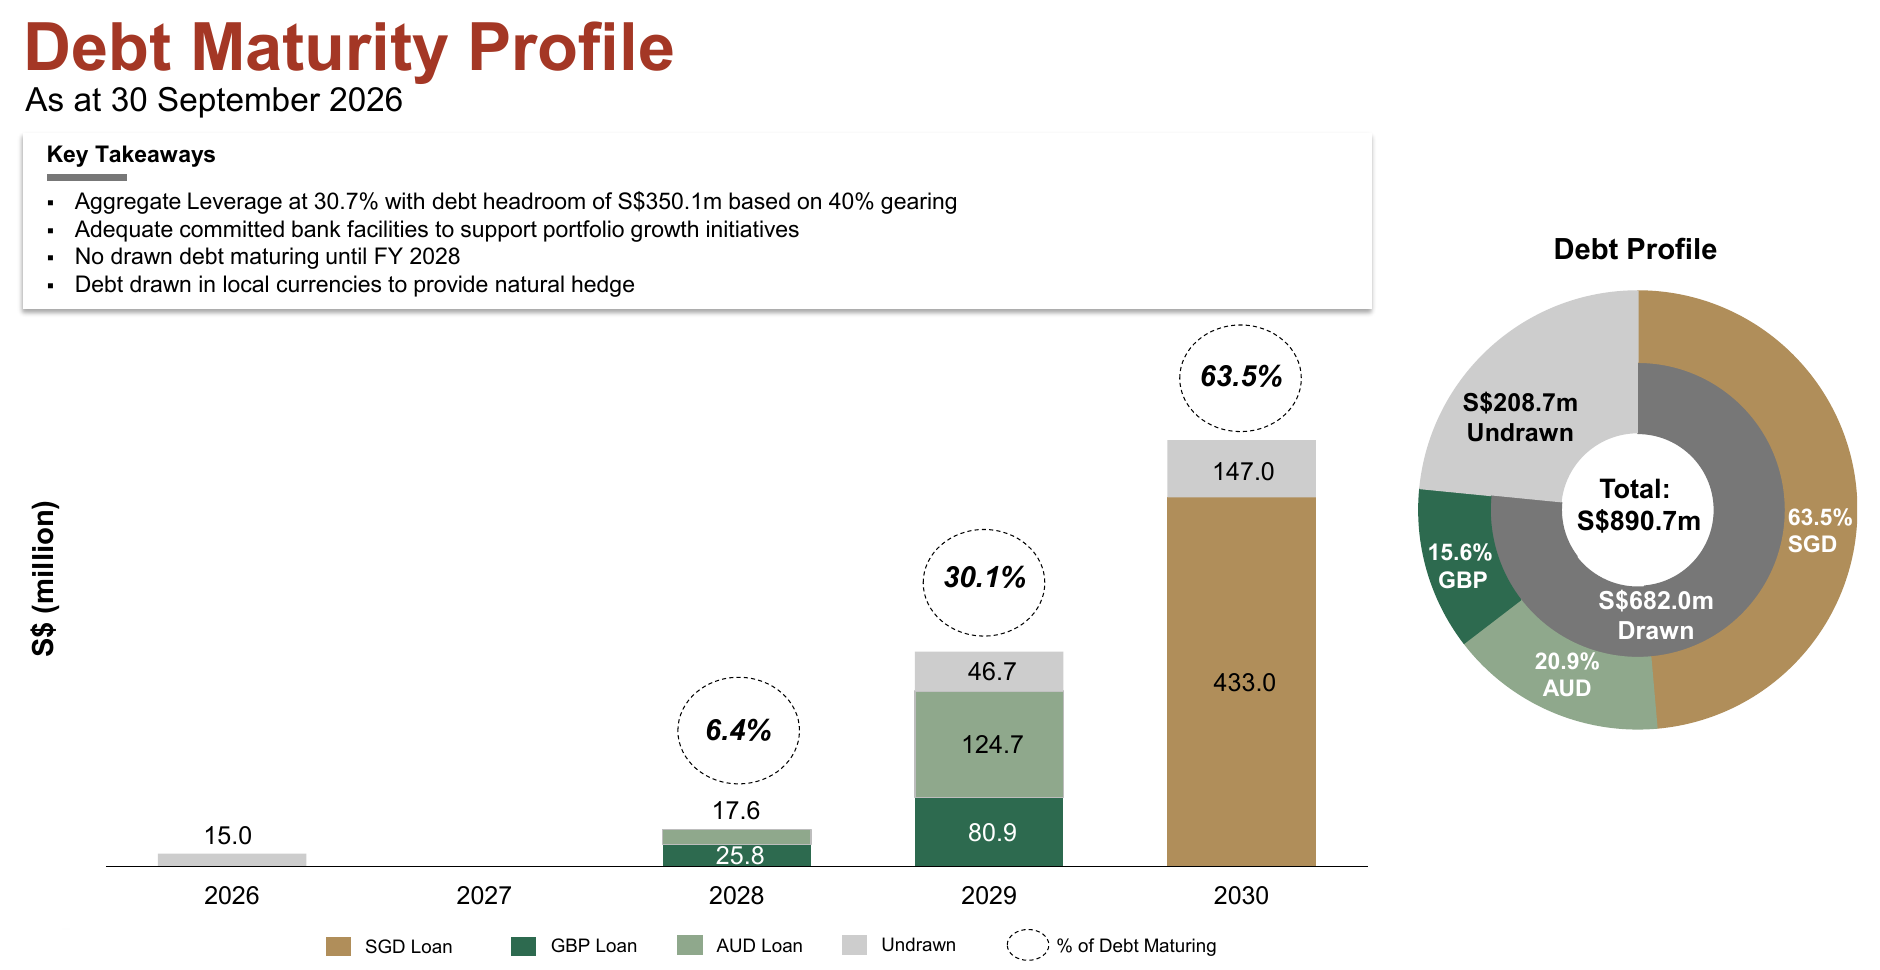
Debt headroom stood at S$350.1 million based on 40% gearing, providing flexibility to pursue growth initiatives.
Weighted average financing cost (excluding amortisation of upfront fees) was 3.65%, below the prospectus forecast of 4.07%, though slightly higher than 3.60% as at 30 June 2026.
About 69.3% of borrowings are hedged to fixed rates, down from 71.6%. Every 100 basis points change in base rates would impact distributable income by about S$2.6 million, or 0.15 cents in DPU per annum.
Interest coverage ratio was healthy at 5.66x, comfortably above the regulatory minimum of 1.5x. Even with a 100 basis points increase in interest rates, the interest coverage ratio would remain at 4.50x.
 |
Source: Centurion Accommodation REIT 9M26 business update |
Weighted average debt maturity shortened to 3.4 years from 3.7 years.
There is no drawn debt maturing until FY2028, with the bulk (63.5%) maturing in 2030.
Debt is drawn in local currencies (63.5% SGD, 20.9% AUD and 15.6% GBP) to provide a natural hedge.
About 93.4% of distributable income is derived from or hedged into Singapore dollars.
Organic growth pipeline to support long-term growth
 |
Source: Centurion Accommodation REIT 9M26 business update |
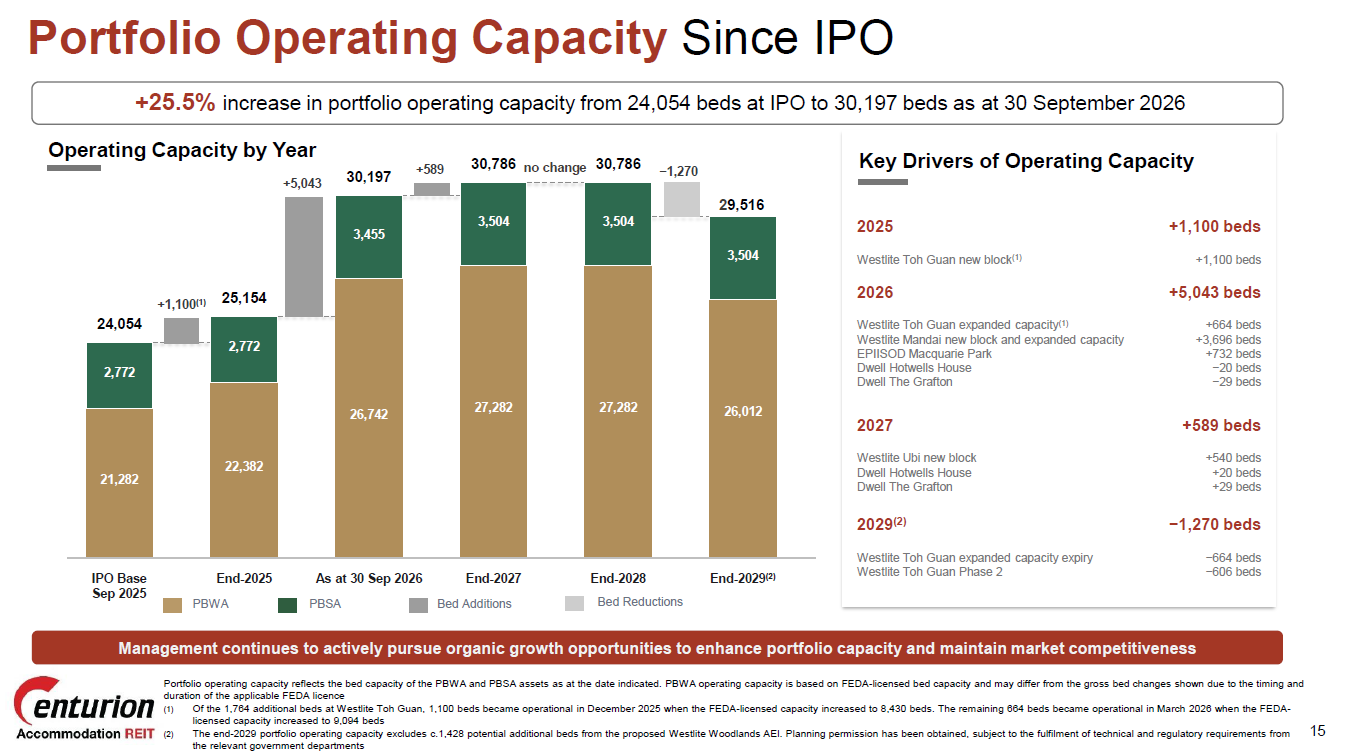
Portfolio operating capacity has increased by 25.5% since IPO, from 24,054 beds to 30,197 beds as at 30 September 2026. This was driven by the new blocks and expanded capacity at Westlite Toh Guan and Westlite Mandai, and the acquisition of EPIISOD Macquarie Park.
At Westlite Ubi, construction of a new six-storey block is progressing and is expected to be operational in 4Q 2027. This will add 540 beds and lift the property’s capacity to 2,190 beds. The existing 1,650-bed block will remain operational during the works.
Investors should note that the 664 expanded capacity beds and 606 beds at Westlite Toh Guan Phase 2 are expected to be removed by end-2029, reducing portfolio capacity by 1,270 beds.
The 1,980 expanded capacity beds at Westlite Mandai are retained until 31 December 2030.
 |
Source: Centurion Accommodation REIT 9M26 business update |
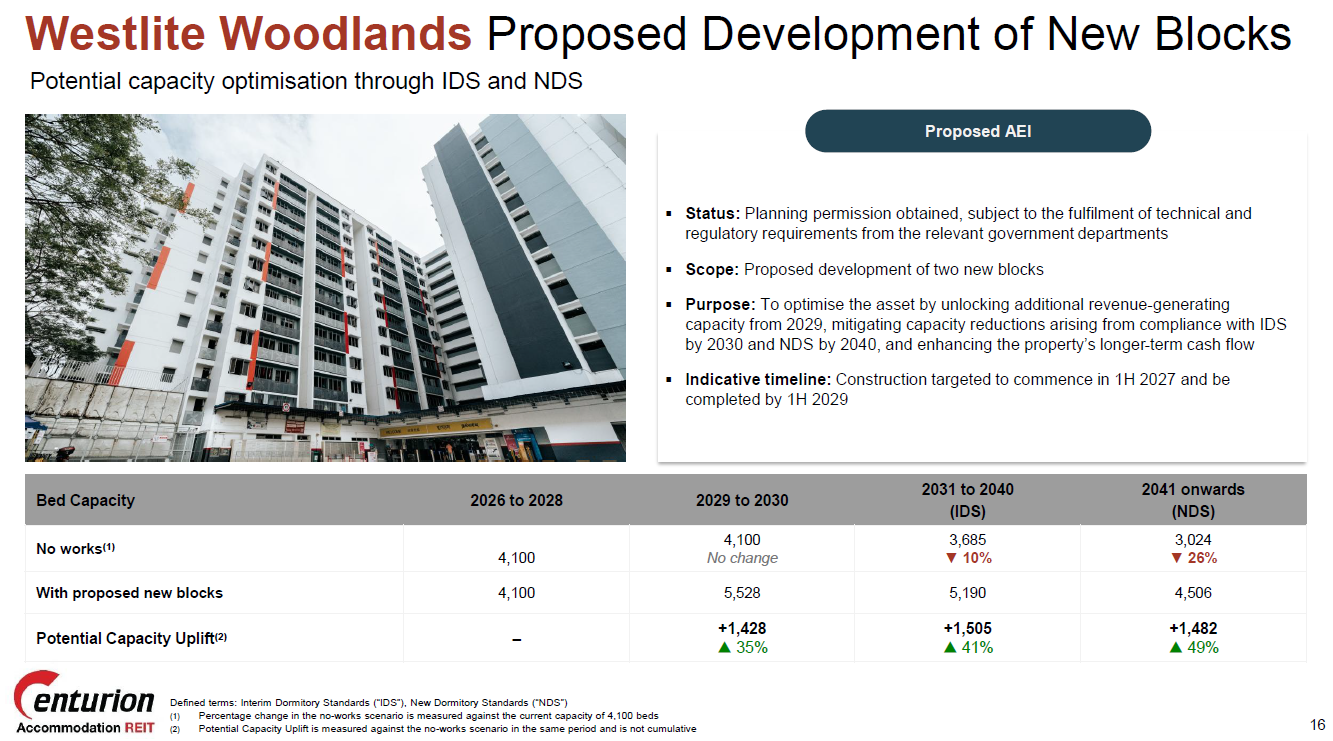
CAREIT has obtained planning permission to develop two new blocks at Westlite Woodlands as part of its proposed asset enhancement initiative. This is subject to technical and regulatory requirements.
Construction is targeted to start in 1H 2027 and complete by 1H 2029, lifting capacity from about 4,100 beds to 5,528 beds (+35%).
With the new blocks, capacity would be 5,190 beds for the period from 2031. For the period from 2041, the capacity would be 4,506 beds. The potential 1,428 additional beds are not included in management’s end-2029 capacity projection, offering upside.
Beyond organic growth, the Sponsor, Centurion Corporation, has granted CAREIT a right of first refusal over its assets that fall within CAREIT’s investment mandate.
The Sponsor’s pipeline comprises about 14,198 beds across nine PBWA and PBSA assets in Singapore, the UK and Australia, expected to be operational between 2027 and 2029.
Outlook remains healthy even with incoming supply of PBWA
 |
Source: Centurion Accommodation REIT 9M26 business update |
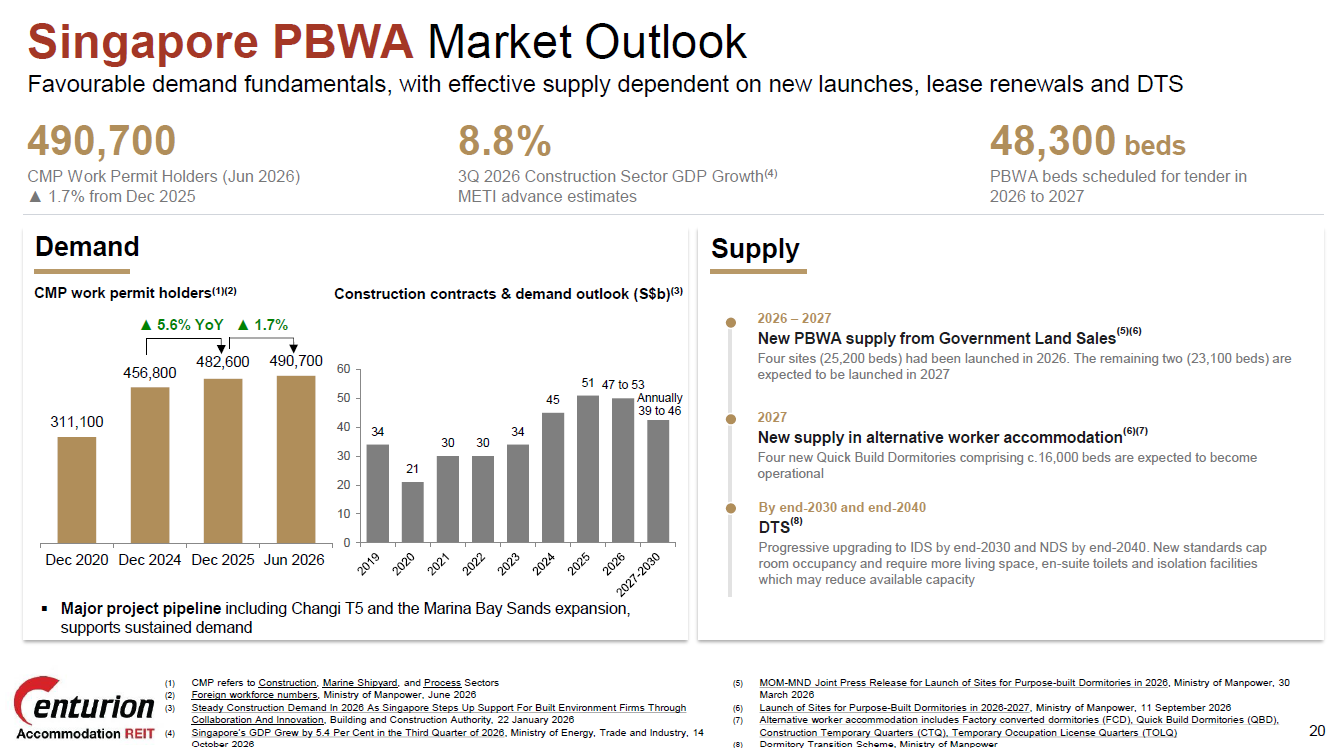
Demand for worker dormitories remains supported by Singapore’s construction activity. Work permit holders in the construction, marine shipyard and process sectors rose 1.7% from December 2025 to 490,700 in June 2026.
Construction sector GDP grew 8.8% year-on-year in 3Q 2026, based on advance estimates. Major projects such as Changi Airport Terminal 5 and the Marina Bay Sands expansion should support sustained demand.
On the supply side, the government plans to launch sites for about 48,300 PBWA beds over 2026 to 2027.
Four sites (25,200 beds) were launched in 2026, with the remaining two sites (23,100 beds) expected to be launched in 2027.
Four new Quick Build Dormitories with about 16,000 beds are also expected to become operational in 2027.
However, the Dormitory Transition Scheme is expected to reduce existing capacity as operators upgrade to the new standards by 2030 and 2040, which should partly offset new supply. We will monitor the impact of new supply on PBWA rental rates. We will monitor the impact of the incoming supply on PBWA rental rates and occupancy.
Neutral and target price at S$1.20
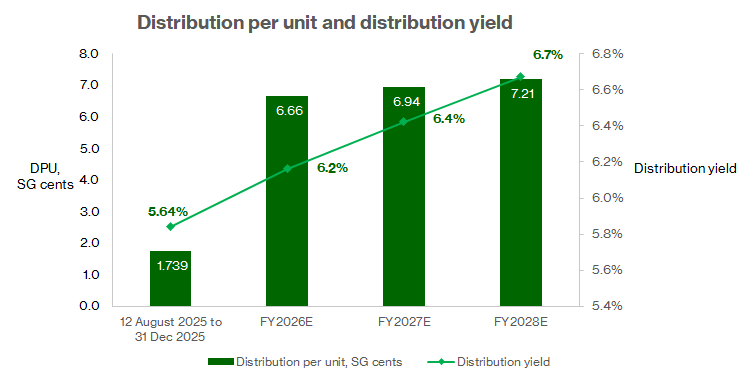
CAREIT is trading at S$1.08. Based on Prospectus Forecast, CAREIT offers a FY2026E distribution yield of 6.2% and FY27E distribution yield 6.4%.
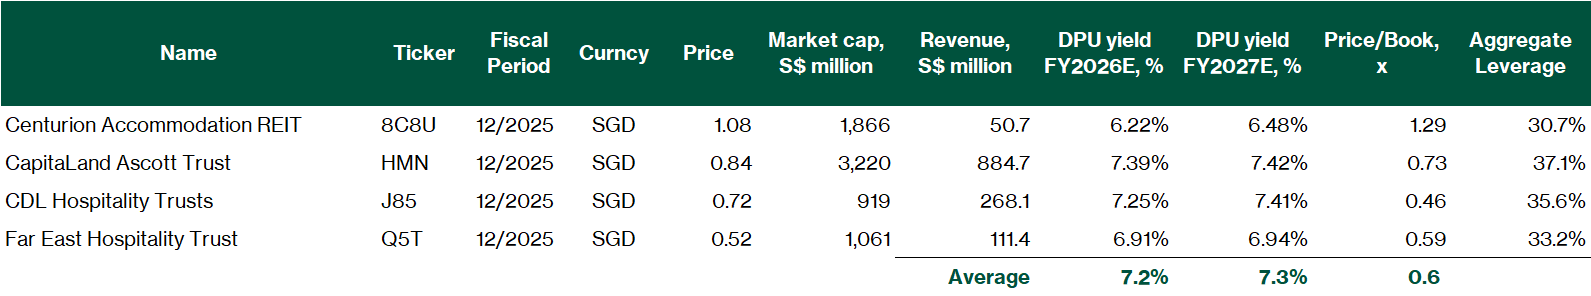
CAREIT’s FY26E projected yield is lower than the yield of other REITs and business trusts in the broader living sector, including Far East Hospitality Trust (6.91%), CapitaLand Ascott Trust (7.39%) and CDL Hospitality Trust (7.25%).
It is trading at a price-to-book ratio of 1.29x, based on net asset value (NAV) per unit of S$0.84 as at 30 June 2026. The premium to NAV reflects CAREIT’s DPU outperformance against its IPO forecast, its organic growth pipeline and the Sponsor’s pipeline of assets.
However, its relatively lower distribution yield and premium valuation provide less room for further re-rating. We maintain a Neutral rating with a target price of S$1.20, while monitoring the execution of its growth initiatives and the impact of new PBWA supply on rental rates.
 |
Source: Centurion Accommodation REIT data |
 |
Source: Factset, as at 11 Nov 2026 |
Key risks
Impact of New Dormitory Standards
New dormitory applications submitted after 18 September 2021 must comply with the New Dormitory Standards (NDS). Operators will still need to undertake retrofitting and adjustments to meet regulatory timelines.
Concentrated exposure to Westlite Toh Guan and Westlite Mandai
Two key assets, Westlite Toh Guan and Westlite Mandai are projected to represent 26.2% and 25.4% of the REIT's FY2027 NPI, respectively. Collectively, the two assets represent more than half of the NPI of the REIT, with future distributions subject to the leasing conditions of these assets and any associated asset-specific risks.
Leasehold interests in Singapore properties
Since the Singapore properties are held on leasehold terms, their lease periods will gradually decrease and ultimately expire. When these leases end, Centurion Accommodation REIT will be required to return the properties to the President of the Republic of Singapore, JTC, or private lessors. The REIT's net asset value (NAV) could decline in the future as the properties approach the tail end of their leases.
Related links:
- Centurion Accommodation REIT share price history and share price target
- Centurion Accommodation REIT dividend history and forecast
Learn more about Singapore REITs here.
Download the full report here.
Check out Beansprout's guide to the best stock trading platforms in Singapore with the latest promotions to invest in Centurion Accommodation REIT.
Follow us on Telegram, Youtube, Facebook and Instagram to get the latest financial insights.
Important Disclosures
Analyst Certification and Disclosures
The analyst(s) named in this report certifies that (i) all views expressed in this report accurately reflect the personal views of the analyst(s) with regard to any and all of the subject securities and companies mentioned in this report and (ii) no part of the compensation of the analyst(s) was, is, or will be, directly or indirectly, related to the specific views expressed by that analyst herein. The analyst(s) named in this report (or their associates) does not have a financial interest in the corporation(s) mentioned in this report.
An associate is defined as (i) the spouse, or any minor child (natural or adopted) or minor step-child, of the analyst; (ii) the trustee of a trust of which the analyst, his spouse, minor child (natural or adopted) or minor step-child, is a beneficiary or discretionary object; or (iii) another person accustomed or obliged to act in accordance with the directions or instructions of the analyst.
Company Disclosure
Global Wealth Technology Pte Ltd (“Beansprout”) does not have any financial interest in the corporation(s) mentioned in this report.
Disclaimer
This report is provided by Beansprout for the use of intended recipients only and may not be reproduced, in whole or in part, or delivered or transmitted to any other person without our prior written consent. By accepting this report, the recipient agrees to be bound by the terms and limitations set out herein.
You acknowledge that this document is provided for general information purposes only. Nothing in this document shall be construed as a recommendation to purchase, sell, or hold any security or other investment, or to pursue any investment style or strategy. Nothing in this document shall be construed as advice that purports to be tailored to your needs or the needs of any person or company receiving the advice. The information in this document is intended for general circulation only and does not constitute investment advice. Nothing in this document is published with regard to the specific investment objectives, financial situation and particular needs of any person who may receive the information.
Nothing in this document shall be construed as, or form part of, any offer for sale or subscription of or solicitation or invitation of any offer to buy or subscribe for any securities. The data and information made available in this document are of a general nature and do not purport, and shall not in any way be deemed, to constitute an offer or provision of any professional or expert advice, including without limitation any financial, investment, legal, accounting or tax advice, and shall not be relied upon by you in that regard. You should at all times consult a qualified expert or professional adviser to obtain advice and independent verification of the information and data contained herein before acting on it. Any financial or investment information in this document are intended to be for your general information only. You should not rely upon such information in making any particular investment or other decision which should only be made after consulting with a fully qualified financial adviser. Such information do not nor are they intended to constitute any form of financial or investment advice, opinion or recommendation about any investment product, or any inducement or invitation relating to any of the products listed or referred to. Any arrangement made between you and a third party named on or linked to from these pages is at your sole risk and responsibility.
You acknowledge that Beansprout is under no obligation to exercise editorial control over, and to review, edit or amend any data, information, materials or contents of any content in this document. You agree that all statements, offers, information, opinions, materials, content in this document should be used, accepted and relied upon only with care and discretion and at your own risk, and Beansprout shall not be responsible for any loss, damage or liability incurred by you arising from such use or reliance.
This document (including all information and materials contained in this document) is provided “as is”. Although the material in this document is based upon information that Beansprout considers reliable and endeavours to keep current, Beansprout does not assure that this material is accurate, current or complete and is not providing any warranties or representations regarding the material contained in this document. All opinions contained herein constitute the views of the analyst(s) named in this report, they are subject to change without notice and are not intended to provide the sole basis of any evaluation of the subject securities and companies mentioned in this report. Any reference to past performance should not be taken as an indication of future performance. To the fullest extent permissible pursuant to applicable law, Beansprout disclaims all warranties and/or representations of any kind with regard to this document, including but not limited to any implied warranties of merchantability, non-infringement of third-party rights, or fitness for a particular purpose.
Beansprout does not warrant, either expressly or impliedly, the accuracy or completeness of the information, text, graphics, links or other items contained in this document. Neither Beansprout nor any of its affiliates, directors, employees or other representatives will be liable for any damages, losses or liabilities of any kind arising out of or in connection with the use of this document. To the best of Beansprout’s knowledge, this document does not contain and is not based on any non-public, material information. The information in this document is not intended for distribution to, or use by, any person or entity in any jurisdiction where such distribution or use would be contrary to law or regulation, or which would subject Beansprout to any registration requirement within such jurisdiction or country. Beansprout is not licensed or regulated by any authority in any jurisdiction or country to provide the information in this document.
As a condition of your use of this document, you agree to indemnify, defend and hold harmless Beansprout and its affiliates, and their respective officers, directors, employees, members, managing members, managers, agents, representatives, successors and assigns from and against any and all actions, causes of action, claims, charges, cost, demands, expenses and damages (including attorneys’ fees and expenses), losses and liabilities or other expenses of any kind that arise directly or indirectly out of or from, arising out of or in connection with violation of these terms, use of this document, violation of the rights of any third party, acts, omissions or negligence of third parties, their directors, employees or agents. To the extent permitted by law, Beansprout shall not be liable to you, any other person, or organization, for any direct, indirect, special, punitive, exemplary, incidental or consequential damages, whether in contract, tort (including negligence), or otherwise, arising in any way from, or in connection with, the use of this document and/or its content. This includes, without limitation, liability for any act or omission in reliance on the information in this document. Beansprout expressly disclaims and excludes all warranties, conditions, representations and terms not expressly set out in this User Agreement, whether express, implied or statutory, with regard to this document and its content, including any implied warranties or representations about the accuracy or completeness of this document and the content, suitability and general availability, or whether it is free from error.
If these terms or any part of them is understood to be illegal, invalid or otherwise unenforceable under the laws of any state or country in which these terms are intended to be effective, then to the extent that they are illegal, invalid or unenforceable, they shall in that state or country be treated as severed and deleted from these terms and the remaining terms shall survive and remain fully intact and in effect and will continue to be binding and enforceable in that state or country.
These terms, as well as any claims arising from or related thereto, are governed by the laws of Singapore without reference to the principles of conflicts of laws thereof. You agree to submit to the personal and exclusive jurisdiction of the courts of Singapore with respect to all disputes arising out of or related to this Agreement. Beansprout and you each hereby irrevocably consent to the jurisdiction of such courts, and each Party hereby waives any claim or defence that such forum is not convenient or proper.
Read also
Gain financial insights in minutes
Subscribe to our free weekly newsletter for more insights to grow your wealth
Most Popular

Comments
0 comments