
HSBC Everyday Global Account (EGA): Earn up to 6.01% p.a. with Rewards+
Savings Account
By Gerald Wong, CFA • 12 Nov 2026
Why trust Beansprout? We’ve been awarded Best Investment Website at the SIAS Investors’ Choice Awards 2025

Make Beansprout your preferred source on Google
Add us on Google to see more of our insights in your search results
Explore HSBC EGA’s November fresh funds promotion, new Rewards+ Programme interest and how eligible savers may combine both offers.

What happened?
HSBC has introduced a new way to earn interest on its HSBC Everyday Global Account (EGA).
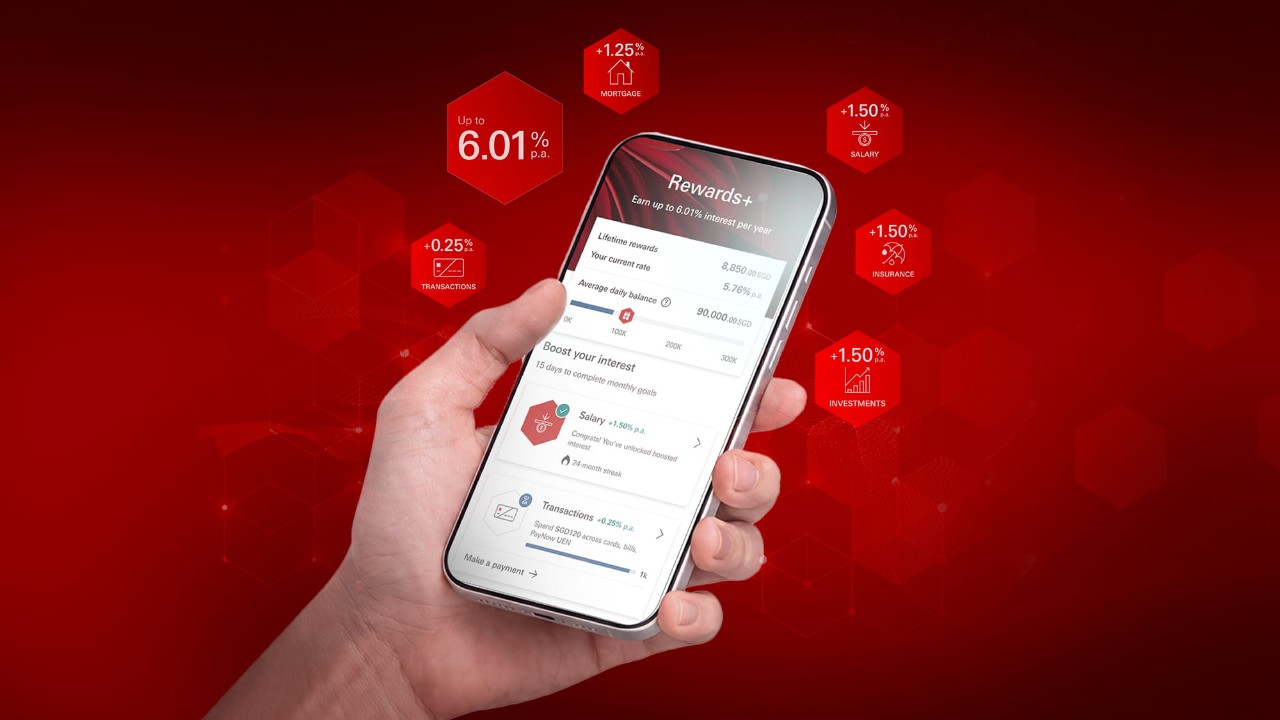
Its new Rewards+ programme offers up to 6.01% p.a. on the first S$100,000 of eligible SGD balances, depending on the banking activities you qualify for.
Alongside this, the November Everyday Global Account (EGA) promotion offers up to 2.10% p.a. on qualifying incremental fresh funds through January 2027.
What caught my attention is that eligible customers can combine both offers, although the advertised rates apply to different balances and come with different conditions.
This also comes as HSBC prepares to end its Everyday+ Rewards Programme on 30 November 2026.
Let us look at how the account works, the interest you may earn and what I would check before moving my savings.
What is HSBC Everyday Global Account (EGA)?
The HSBC EGA combines savings and everyday banking.
It is a multi-currency account that lets you hold up to 11 currencies, including Singapore dollars. You can exchange currencies, make payments and send money overseas through HSBC’s digital banking services.
The Everyday Global Debit Card also lets you spend and withdraw cash in supported currencies. This may be useful if you travel regularly or manage money across different countries, although transaction conditions and fees apply.
You do not need to be an HSBC Premier customer to open an EGA. The account is available to Personal Banking customers too. Premier is a separate banking relationship with its own eligibility requirements and benefits.
For savers, the main question is how much interest the account can earn.
There are now two offers to understand: Rewards+, which rewards qualifying banking activities, and the November promotion, which rewards eligible fresh funds.
What is the interest rate on the HSBC Everyday Global Account?
The EGA’s prevailing SGD interest rate is 0.01% p.a. Most of the potential return therefore comes from meeting additional conditions.
| Interest component | Interest rate | Balance that qualifies |
|---|---|---|
| Base interest | 0.01% p.a. | SGD account balance |
| HSBC Rewards+ | Up to 6.00% p.a. additional interest, giving up to 6.01% p.a. including base interest* | First S$100,000 of eligible sole-name SGD average daily balance |
| November fresh funds promotion | Up to 2.10% p.a. including base interest* | Qualifying incremental SGD average daily balance, capped at S$5 million |
| Source: HSBC. *Both advertised total rates include base interest. | ||
The offers available depend on when you opened your EGA and whether you are already participating in a promotion.
- If you are opening an EGA now, you can consider Rewards+ and applicable welcome promotions, but will not qualify for November’s fresh funds offer.
- If you already have an eligible EGA and fresh funds, you may be able to combine Rewards+ with the November promotion.
- If you are participating in September or October’s EGA promotion, refer to your existing offer’s terms, as you cannot also join November’s promotion.
How does HSBC Rewards+ work?
Rewards+ started on 1 November 2026 and is available to eligible new and existing Personal Banking, Premier and Premier Elite customers.
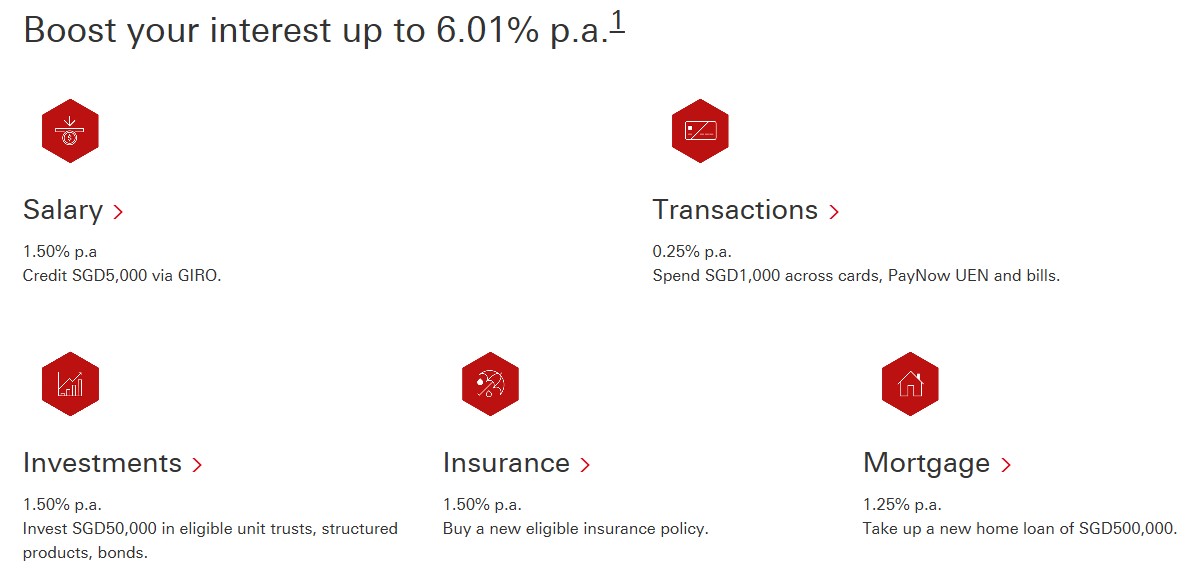
You can earn additional interest by meeting one or more of five categories.
| Category | Main qualifying requirement | Additional interest |
|---|---|---|
| Salary | Credit at least S$5,000 of qualifying salary each month | 1.50% p.a. |
| Transactions | Make at least S$1,000 of eligible transactions each month | 0.25% p.a. |
| Investments | Purchase at least S$50,000 of eligible investments in a calendar month | 1.50% p.a. |
| Insurance | Purchase an eligible new policy with an annualised regular premium of at least S$12,000 or a single premium of at least S$50,000 | 1.50% p.a. |
| Mortgage | Take out a qualifying new HSBC home loan of at least S$500,000 | 1.25% p.a. |
| Maximum additional interest | Meet all five categories | 6.00% p.a. |
| Source: HSBC | ||
Together with base interest of 0.01% p.a., this gives the advertised maximum of 6.01% p.a.
The bonuses apply to the first S$100,000 of eligible SGD average daily balance in your sole-name EGA. Unlike the fresh funds promotion, Rewards+ does not require the money to be newly deposited.
Eligible customers are automatically enrolled.
Salary and everyday transactions
For many of us, salary and transactions may be the first categories to consider.
Salary must be credited through GIRO with the transaction narrative “SALA”. Moving money from your own bank account does not qualify as salary crediting.
Eligible transactions include qualifying HSBC card spending, bill payments and PayNow payments to businesses using a UEN. PayNow transfers to individuals do not qualify, and card-spending exclusions apply.
Meeting both categories earns 1.75% p.a. in additional interest, or 1.76% p.a. including base interest, before any separate fresh funds promotion.
I would check whether my existing salary arrangements and spending can meet these conditions comfortably, rather than increase my spending just to earn the bonus.
Investments, insurance and mortgage
The remaining categories involve larger financial commitments.
Eligible investments include selected unit trusts, structured products and bonds. Equities, ETFs, CPFIS/SRS investments and specified money market funds are excluded.
The insurance bonus requires an eligible new policy meeting the premium threshold, while the mortgage bonus requires a qualifying new home loan. Repricing or restructuring an existing HSBC loan does not qualify.
Salary and transaction bonuses are assessed monthly. Qualifying investment, insurance and mortgage activities can earn bonuses for 12 months, subject to continuing conditions and rate changes.
I would assess these products on their own merits. Additional savings interest should be one consideration, rather than the reason for buying an investment or committing to an insurance policy.
Read the full T&C of the HSBC Rewards+ Programme here.
HSBC EGA November 2026 fresh funds promotion
The HSBC EGA November 2026 SGD promotion offers a total interest rate of up to 2.10% p.a. on qualifying incremental SGD fresh funds from November 2026 to January 2027.
The rate depends on how much qualifying money you add and whether you meet the wealth-customer or balance-maintenance conditions.
| Incremental average daily balance | Wealth customers / non-wealth customers meeting the balance-maintenance condition | Other non-wealth customers |
|---|---|---|
| Below S$500,000 | 2.00% p.a. | 1.80% p.a. |
| S$500,000 to S$5 million | 2.10% p.a. | 1.90% p.a. |
| Source: HSBC | ||
For qualifying incremental balances below S$500,000, the highest promotional rate is 2.00% p.a. You need at least S$500,000 of qualifying incremental average daily balance to earn the higher 2.10% rate.
How does HSBC calculate the incremental fresh funds?
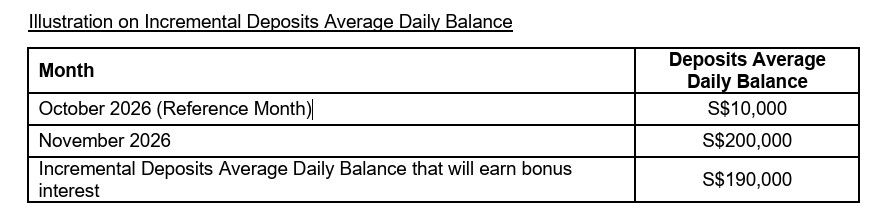
HSBC calculates your qualifying incremental average daily balance (ADB) against October 2026.
For example, if your October ADB was S$20,000 and your November ADB rises to S$120,000, the S$100,000 increase may qualify for promotional bonus interest, provided it consists of eligible fresh funds.
ADB is based on end-of-day balances throughout the month, so depositing money later in the month contributes less to that month’s average. Transfers between HSBC accounts, recycled withdrawals and proceeds from HSBC deposits or investments do not count as fresh funds.
You do not need to buy a wealth product to earn the higher promotional rate. Non-wealth customers can qualify by keeping their incremental ADB in December 2026 and January 2027 at least as high as November’s.
Withdrawals are possible, but may affect eligibility if they bring either month’s average below the required level.
Alternatively, customers holding eligible wealth products by 28 February 2027 qualify for the wealth-customer rate. These include unit trusts, equities, bonds, structured products and eligible HSBC-sold insurance policies, but exclude foreign exchange and Dual Currency Plus. Do note that these criteria differ from Rewards+, where equities do not qualify for the investment bonus.
To qualify, you must also have an EGA that was opened by 31 July 2026. This means customers who only open an EGA in November will not qualify for this particular bonus interest promotion.
To participate in the HSBC SGD EGA promotion, eligible existing customers must register by 30 November 2026, either through the HSBC Singapore app or by sending an SMS to 74722 in the following format:
EGA <space> First 9 digits of your Everyday Global Account number
Example: EGA 123456789
Bonus interest is scheduled for payment by 31 March 2027, subject to verification and delays. Keep your reward account open and your HSBC relationship in good standing until payment.
Read the full T&C of the HSBC SGD EGA Bonus Interest November 2026 Promotion here.
Can the HSBC SGD EGA Bonus Interest Promotion be stacked with Rewards+?
You can stack the November EGA promotion with Rewards+
Here is our calculation for a S$100,000 average balance that fully qualifies for the higher 2.00% November rate and Rewards+:
| Scenario | Calculation | Combined annualised rate |
|---|---|---|
| Fresh Funds EGA Bonus Interest Promotion only | 2.00% | 2.00% p.a. |
| Plus qualifying salary from Rewards+ | 2.00% + 1.50% | 3.50% p.a. |
| Plus qualifying salary and transactions from Rewards+ | 2.00% + 1.50% + 0.25% | 3.75% p.a. |
| Source: HSBC, and Beansprout calculations as of 12 November 2026. | ||
This assumes the full S$100,000 is eligible incremental fresh funds, with all conditions met. The combined rate applies only while both benefits overlap. A deposit made partway through a month produces a lower monthly average balance.
If some savings were already in the account during October, the fresh funds bonus will apply to a smaller amount. Rewards+ can still apply to the eligible account balance up to its cap.
What would Beansprout do?
The HSBC Everyday Global Account may be useful as a supplementary savings account if I am comfortable with the fresh funds mechanics. With Rewards+, it may also be worth a closer look if I can meet the salary and transaction requirements through my usual banking activities.
I would start with the rate I can realistically earn. Qualifying salary credits and transactions give 1.76% p.a. including base interest on the first S$100,000, before any separate fresh funds promotion.
If I also qualify for November’s 2.00% p.a. promotional rate, the combined return could reach 3.75% p.a. on S$100,000 that qualifies under both programmes. However, I would still look beyond the headline number.
For the fresh funds offer alone, the highest rate on incremental balances below S$500,000 is 2.00% p.a. The 2.10% p.a. rate requires at least S$500,000 of qualifying incremental ADB, while Rewards+ bonuses remain capped at the first S$100,000.
For me, one positive is that I do not necessarily have to buy an HSBC investment or insurance product to earn the higher fresh funds rate. As a non-wealth customer, I can qualify by keeping my incremental ADB in December and January at least as high as November’s.
However, this also makes the promotion less flexible if I expect to need the money over the next few months. While there is no fixed deposit-style maturity period, withdrawing enough to lower my incremental ADB could reduce my promotional rate.
Before transferring money, I would check my October average daily balance, my account’s eligibility, whether I am in an overlapping promotion and how much cash I can comfortably keep through January 2027.
I would also avoid buying investments or insurance, or taking out a mortgage, solely to earn the maximum Rewards+ rate. The costs, risks and longer-term commitments could matter far more than the extra savings interest.
The EGA may be more attractive if you already have an eligible account, have fresh funds available and can meet the conditions without stretching your finances.
If you prefer a simpler arrangement, you can compare the best savings accounts in Singapore for different balances, salary-crediting arrangements and spending habits here.
If you are deciding where to park your cash, explore how savings accounts fit into your Liquidity Pot within Beansprout’s Four Pots of Wealth, alongside fixed deposits, Singapore T-bills and Singapore Savings Bonds here and money market funds.
Follow Beansprout on Telegram, Youtube, Facebook and Instagram, and add Beansprout as your preferred source on Google so you never miss an update.

Find out which savings account allows you to earn the highest interest rate on your savings.
Read also
Gain financial insights in minutes
Subscribe to our free weekly newsletter for more insights to grow your wealth
Most Popular

Questions and Answers
1 questions
- Geri • 15 Jul 2025 06:06 AM