
Stoneweg Europe Stapled Trust - Internalisation could unlock a new earnings stream
Global Wealth Technology Pte. Ltd. is regulated by the Monetary Authority of Singapore (MAS) as a licensed Financial Adviser.

Make Beansprout your preferred source on Google
Add us on Google to see more of our insights in your search results
Stoneweg Europe Stapled Trust (SERT) has proposed to internalise its REIT Manager, Business Trust trustee-manager and pan-European logistics and light industrial asset and property management platform. The purchase consideration for the proposed internalisation is €114 million.
Proposed acquisition of management platform
Stoneweg Europe Stapled Trust (SERT) has proposed to internalise its REIT Manager, Business Trust trustee-manager and pan-European logistics and light industrial asset and property management platform.
The transaction would also bring selected third-party asset management contracts and associated minority co-investments into SERT.
The proposed internalisation would transform SERT from an externally managed vehicle into a more integrated platform with approximately €3.2 billion of assets under management and around 100 employees across Europe and Singapore.

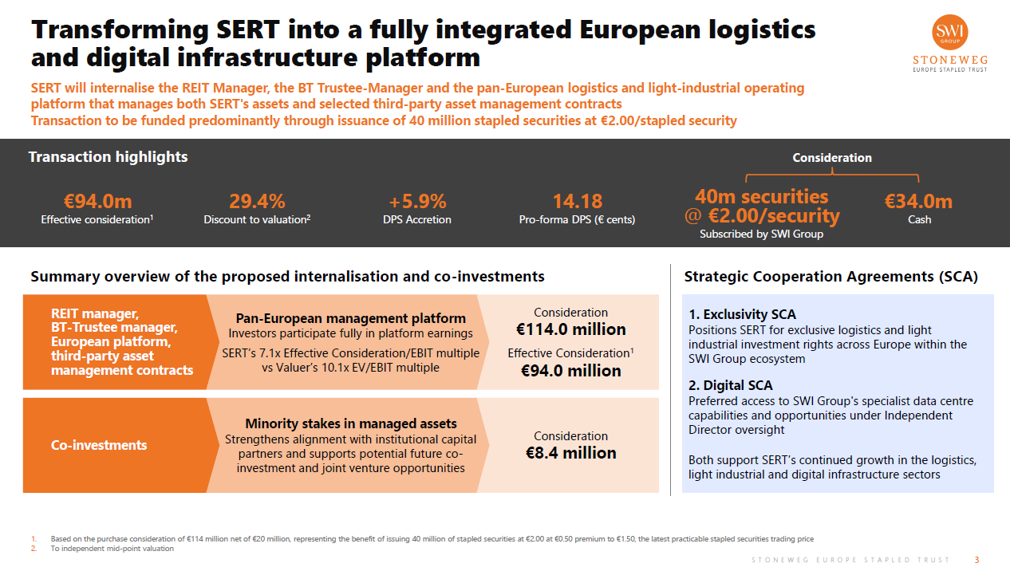
The purchase consideration for the proposed internalisation is €114 million, representing a 14.4% discount to the €133.2m independent valuation midpoint.
The purchase consideration comprises €114 million for the management platform and €8.4 million for the minority co-investments in assets managed through the third-party service contracts.
The effective consideration is €94 million. The €20 million difference reflects the benefit accruing to SERT from the issuance of 40.0 million subscription securities to SWI Group at €2.00 per security.
The issue price is a €0.50 premium to €1.50, the volume-weighted average trading price as at 24 September 2026. Thus, issuing the new securities at €2.00 reduces SERT’s cash outlay by €20 million.
Transaction structure and consideration
The proposed transaction changes the way economic value flows through SERT. Instead of paying fees to an external manager, SERT will bear the cost of operating the platform but retain the residual economics.
Under the current structure, SERT owns the European property portfolio but the management platform is externally owned. Management, property management, acquisition, divestment, development and leasing fees are paid to the external manager. On a pro forma basis, the FY25 fees given up by SERT was €26.4 million.
Following internalisation, SERT would own the REIT Manager, BT Trustee-Manager and the European logistics and light industrial management platform. This allows securityholders to participate directly in the economics generated by the platform.
The platform currently manages 96 SERT assets and 46 third-party assets.
What is SERT paying for?
The transaction comprises three main components.
#1 Managers and operating platform
SERT will acquire the shares of the REIT Manager and BT Trustee-Manager, together with the European operating and management platform companies and selected third-party asset and property management mandates. The purchase consideration of €114.0 million represents a discount of 14.4% when compared to the midpoint of the range of enterprise value.
#2 Third-party asset management contracts
The third-party contracts cover 46 assets and approximately €820m of AUM. SERT says these contracts generate recurring fee income and can also strengthen relationships with institutional investors
#3 Co-investments
SERT will also acquire minority interests in certain real estate assets linked to the third-party mandates. The maximum consideration for these co-investments is €8.4m.
Valuation of the proposed transaction
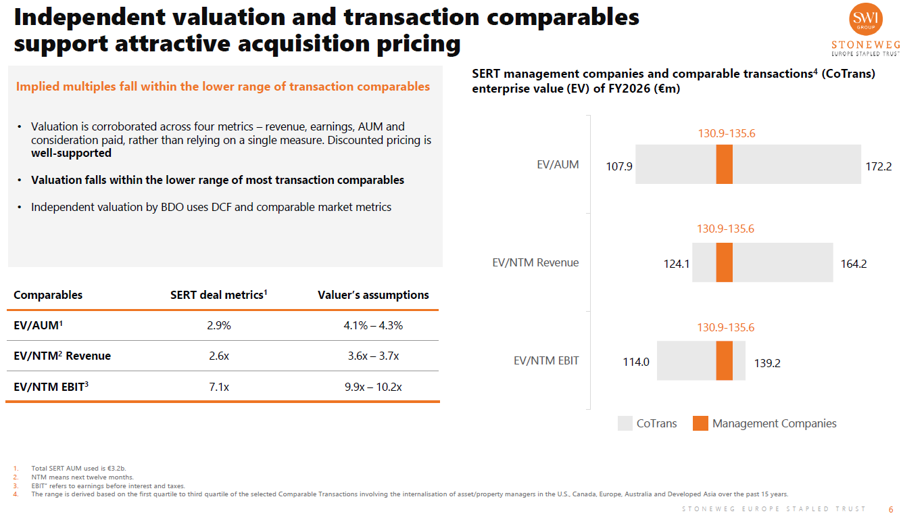
The proposed internalisation is priced below the range of selected transaction comparables.
The implied EV/AUM of 2.9%, EV/NTM revenue of 2.6x and EV/NTM EBIT of 7.1x are below the valuer’s comparable ranges of 4.1–4.3%, 3.6–3.7x and 9.9–10.2x respectively.
This suggests SERT is acquiring the platform at a discount to its independently assessed value.
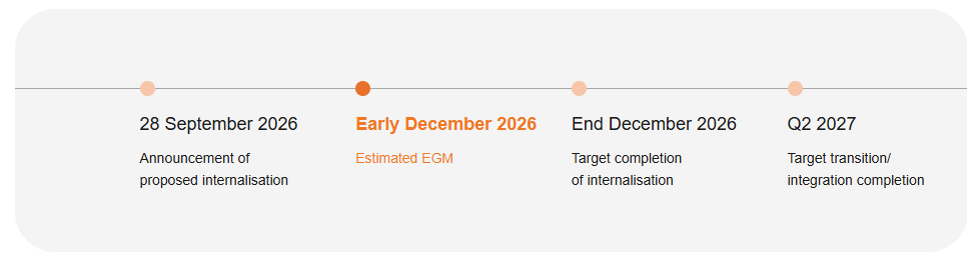
The proposed transaction is subjected to approval of Stapled Securityholders at the extraordinary general meeting. The indicative timeline as shown below :
Potential benefits of the acquisition
SERT is moving from paying management fees to SWI Group to owning the management platform itself. This allows it to retain the earnings from managing its own portfolio, including €13.3 million of NTM EBIT.
The internalised platform also gives SERT an additional source of recurring fee income from third-party mandates. In simple terms, more of the value created by the management platform will flow back to SERT’s securityholders.
However, the acquisition also comes with some trade-offs. For instance, the internalisation does not simply convert €26.4m of fees into €26.4m of earnings. A substantial portion of those fees is required to fund the internalised platform.
While the transaction creates stronger economic alignment, it also means governance and related-party transactions remain important considerations.
SWI remains a substantial shareholder, strategic partner and counterparty to the cooperation agreements. The agreements also contain fee arrangements that could result in payments to SWI entities.
Leasing fees are subject to stated caps and governance requirements, but investors should monitor them because they represent potential leakage of economics from an otherwise internally managed structure.
#1 Immediate earnings enhancement
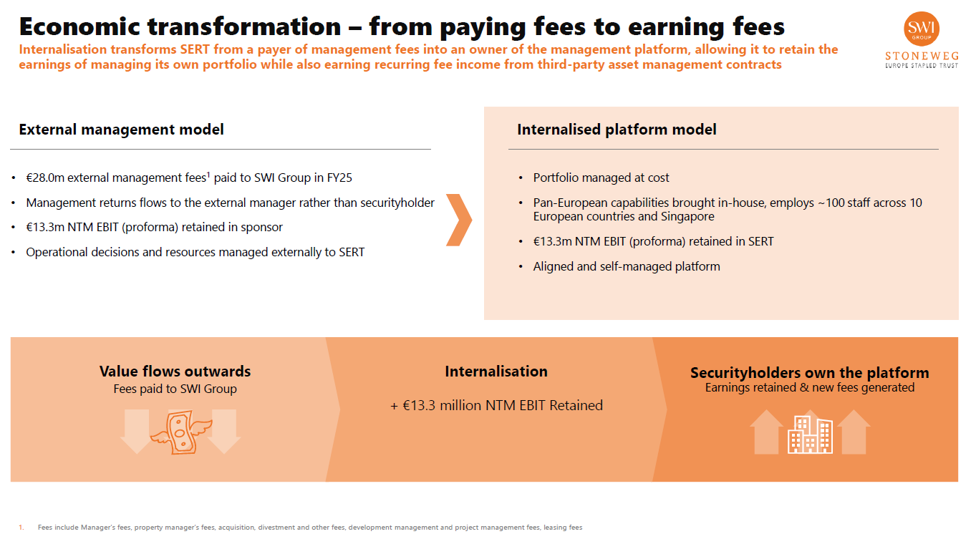
SERT’s proposed internalisation changes its model from paying management fees to SWI Group to owning the management platform.
Under the current structure, SERT paid €28.0 million in external management fees in FY25, while €13.3 million of NTM EBIT generated by the management platform would be retained within SERT following internalisation.
It will also bring the platform and around 100 staff in-house, while continuing to earn fees from third-party asset management contracts.
In short, more of the value generated by the platform stays with SERT’s securityholders.
#2 DPU accretion
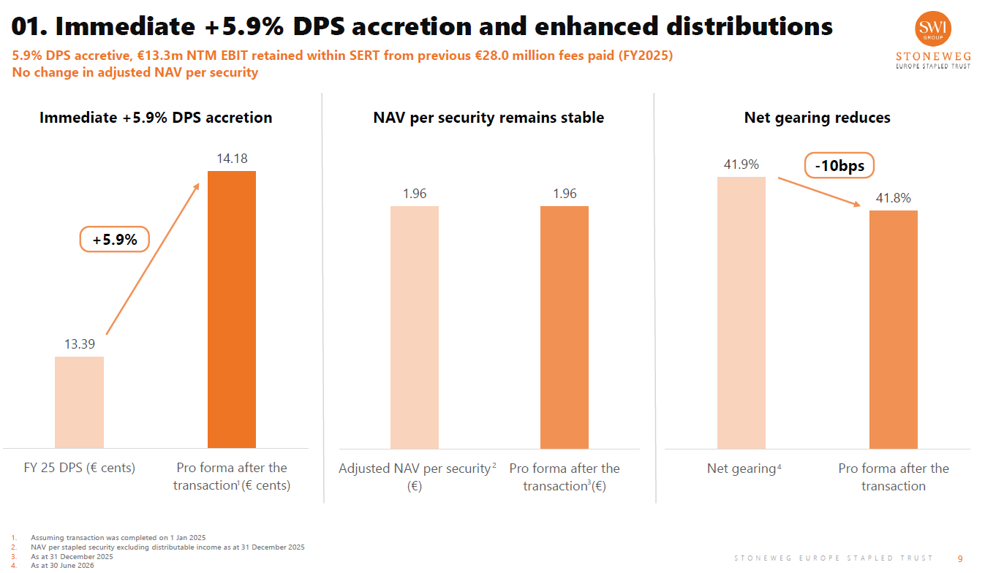
SERT’s proposed internalisation is expected to be immediately DPU accretive. Pro forma FY25 DPU increases 5.9% from 13.39 euro cents to 14.18 euro cents, mainly reflecting the retention of earnings from the management platform that were previously paid to SWI Group as management fees.
The transaction allows SERT to retain €13.3 million of NTM EBIT generated by the platform, while also creating a new recurring income stream from third-party asset management contracts. However, the accretion is partly offset by the operating costs of running the internalised platform, estimated at €23.8 million for FY27.
Importantly, the 5.9% DPU accretion assumes that all required third-party consents are obtained. Management also expects adjusted NAV per security to remain unchanged at €1.96, while net gearing is broadly stable at 41.8%.
If none of the required third-party consent in respect of the Third-Party Service Contracts are obtained, pro forma DPU accretion would be 3.1%, or 13.80 euro cents. The NAV remains stable at €2.02 per security.
#3 SWI's economic alignment
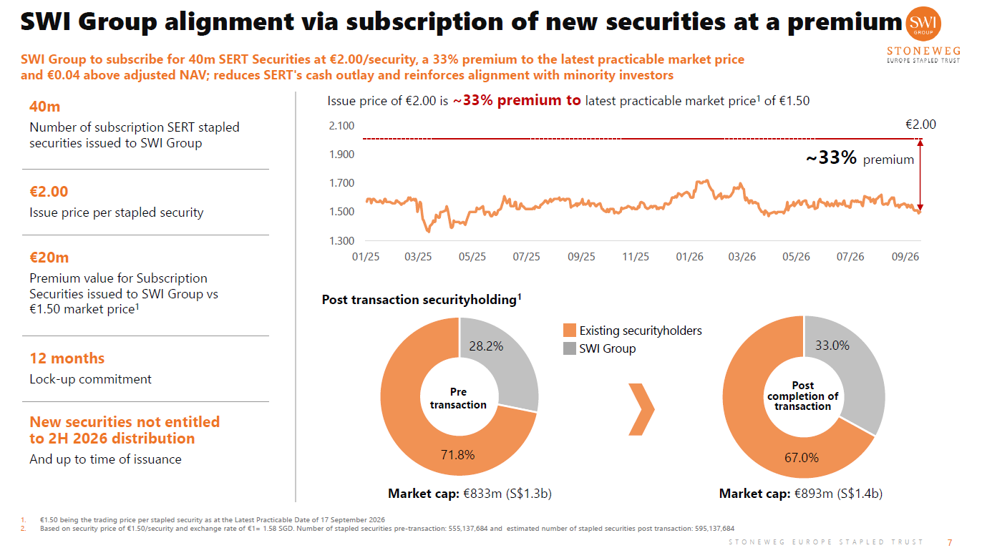
SWI currently has a deemed interest of 28.21% in SERT. Following the proposed issuance of 40m new securities, its ownership is expected to rise to approximately 33%.
SWI will subscribe for the new securities at €2.00, compared with the market price of approximately €1.50, providing an estimated €20m premium benefit to SERT.
The securities will also be subject to a 12-month lock-up and will not receive the 2H26 distribution prior to issuance.
#4 Long-term strategic rationale
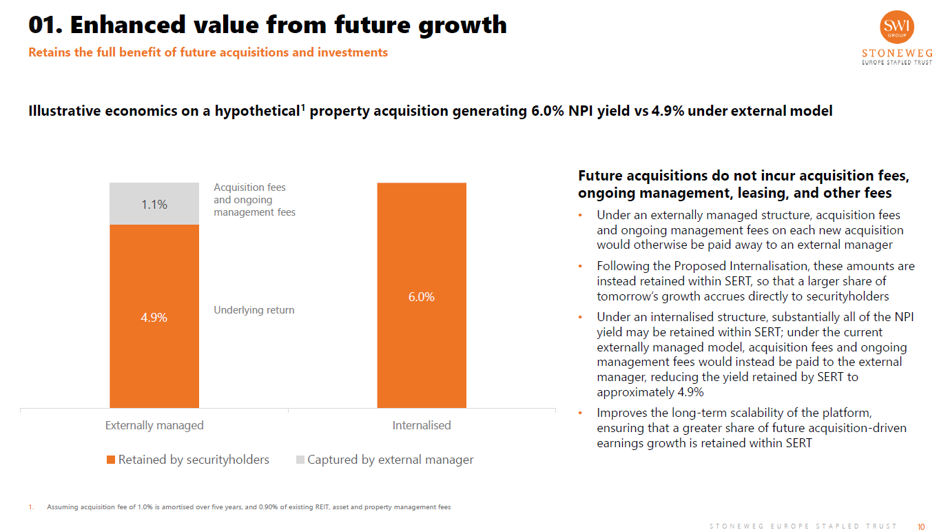
The most interesting aspect of internalisation is what happens to future acquisitions.
SERT's presentation illustrates a hypothetical acquisition producing a 6.0% NPI yield.
Under the current externally managed structure, SERT estimates that approximately 4.9% would be retained after acquisition and ongoing management fees.
Under the internalised structure, substantially all of the NPI yield could be retained within SERT.
This potentially changes the economics of SERT's future growth.
Maintain BUY and target price at €1.73
Stoneweg Europe Stapled Trust is trading at €1.47, implying FY26E distribution yield of 8.7%. In comparison, Elite UK REIT and IREIT Global are trading at FY26E distribution yield of 9.8% and 7.6%, respectively. Elite UK REIT’s higher yield reflects the portfolio’s smaller scale.
Although the management has provided for FY26E distribution guidance, we think there is upside potential from the data centre assets. In addition, the data centre valuation will provide upside to the net asset value upon semi-annual revaluation of AiOnX.
SERT is trading at FY25 price-to-book of 0.76x, below the peer group average of 0.81x. Despite the discount to peers, SERT remains below book value, and management has decided to continue with unit buybacks in 2026.
Stoneweg Europe Stapled Trust on REIT Income Pot framework
We apply Beansprout's REIT screening framework, covering DPU growth, gearing, and yield versus risk-free alternatives, to assess whether Stoneweg Europe Stapled Trust (“SERT”) is suitable for an income-focused portfolio.
| Check | Stoneweg Europe Stapled Trust (SERT) |
| DPU growth – able to generate stable earnings | ✅ Pass — 1H26 DPU 6.642 Euro cents, +1.4% year-on-year |
| Aggregate leverage < 45% | ✅ Pass — 43.6% as of 30 June 2026
|
| Dividend yield > 5% | ✅ Pass — 1H26 trailing twelve months DPU of 13.48 cents, translating to a distribution yield of 8.7% (24 Aug closing price €1.55) |
| Overall | 3/3 checks |
| Source: Beansprout | |
Check #1: DPU growth remained positive
1H26 DPU of 6.642 Euro cents was 1.4% higher year-on-year, with NPI +1.3%, on a like-for-like basis. DPU growth was driven by income from the AiOnX data centre investments and strong logistics/light industrial NPI growth (+2.7% year-on-year).
Check #2: Gearing ratio at an acceptable level
Aggregate leverage stood at 43.6% as at 30 June 2026, up from 42.4% as at 31 December 2025 and within Beansprout's preferred gearing threshold.
Interest coverage ratio was 3.0x, with a weighted average debt maturity of five years. SERT does not have refinancing requirements until 2030, other than the revolving credit facility.
Check #3: Distribution yield remains attractive
Trailing-twelve-month DPU of 13.48 Euro cents (1H26’s 6.642 cents plus 2H FY25’s 6.837 cents), at the closing price of €1.55 (24 Aug 2026), implies a distribution yield of 8.7%.
Currently, Singapore Savings Bond is offering about 2.3% and 6-month T-bill is offering around 1.9%.
SERT is trading at a spread of 6.6% to 7.1% over risk-free rates. This is above Beansprout's preferred minimum spread of 3 percentage points, compensating investors for SERT’s Euro exposure and modest outlook for the office assets.
SERT passes the 3/3 checks for the Income Pot framework.
Investors should monitor the portfolio repositioning, investments into Western Europe logistics and data centres, and rental reversion trends.
Key risks
Key risks include interest rate risk, weak office demand, limited debt headroom, execution risk and macroeconomic risk.
Interest rate and refinancing risk
It is exposed to movements in European interest rates which have remained elevated relative to the low-rate environment seen in prior years. Higher all-in funding costs directly increase interest expense and reduce distributable income.
What this really means is that even if the underlying property income remains stable, distributions can still come under pressure due to financing costs alone. The pace and timing of rate cuts, as well as its ability to manage its debt maturity profile and hedging strategy, will be key in determining the extent of this impact.
It actively manages its debt profile through a mix of fixed and hedged borrowings and maintains a well-staggered debt maturity profile.
Office sector weakness
The office sector faces structural and cyclical headwinds across Europe. Demand for office space has softened in certain markets due to hybrid work trends, corporate cost rationalisation, and tenant downsizing. This has resulted in lower occupancy rates and weaker rental reversions compared to logistics assets.
Stoneweg Europe Stapled Trust is gradually reducing its exposure to office assets through selective divestments, while increasing allocation to logistics and light industrial properties. This strategic shift helps rebalance the portfolio towards sectors with stronger demand fundamentals and more resilient occupancy.
Leverage and limited debt headroom
Its gearing remains in the low-40% range, which is below regulatory limits but leaves only moderate headroom for additional borrowing. This constrains financial flexibility, particularly in a rising rate environment where maintaining balance sheet discipline is critical. This limits its ability to pursue acquisitions or fund large-scale redevelopment without raising equity. Ongoing divestments of non-core assets can free up capital and create additional headroom. The REIT also has access to multiple funding channels, including bank debt and capital markets, allowing it to optimise its capital structure.
Execution risk in portfolio repositioning
The REIT is actively repositioning its portfolio while undertaking asset enhancement initiatives and redevelopment projects to improve asset quality and ESG credentials. We think the execution risk is mitigated by the strong support from an experienced sponsor, SWI Group, which has an established track record. This provides operational expertise and access to deal flow. For instance, the REIT has invested in the data centre platform at the early development stage.
Macroeconomic and valuation risk
SERT’s portfolio is concentrated in Europe, exposing it to regional macroeconomic conditions including GDP growth, inflation, and monetary policy. A weaker economic outlook could dampen tenant demand, reduce leasing activity, and put downward pressure on rents across certain markets.
Related links:
- Stoneweg Europe Stapled Trust share price history and share price target
- Stoneweg Europe Stapled Trust history and dividend forecasts
Download the full report here.
Check out Beansprout's guide to the best stock trading platforms in Singapore with the latest promotions to invest in Stoneweg Europe Stapled Trust.
Join the Beansprout Telegram group for the latest insights on Singapore stocks, REITs, bonds and ETFs.
Important Disclosures
Analyst Certification and Disclosures
The analyst(s) named in this report certifies that (i) all views expressed in this report accurately reflect the personal views of the analyst(s) with regard to any and all of the subject securities and companies mentioned in this report and (ii) no part of the compensation of the analyst(s) was, is, or will be, directly or indirectly, related to the specific views expressed by that analyst herein. The analyst(s) named in this report (or their associates) does not have a financial interest in the corporation(s) mentioned in this report.
An associate is defined as (i) the spouse, or any minor child (natural or adopted) or minor step-child, of the analyst; (ii) the trustee of a trust of which the analyst, his spouse, minor child (natural or adopted) or minor step-child, is a beneficiary or discretionary object; or (iii) another person accustomed or obliged to act in accordance with the directions or instructions of the analyst.
Company Disclosure
Global Wealth Technology Pte Ltd (“Beansprout”) does not have any financial interest in the corporation(s) mentioned in this report.
Disclaimer
This report is provided by Beansprout for the use of intended recipients only and may not be reproduced, in whole or in part, or delivered or transmitted to any other person without our prior written consent. By accepting this report, the recipient agrees to be bound by the terms and limitations set out herein.
You acknowledge that this document is provided for general information purposes only. Nothing in this document shall be construed as a recommendation to purchase, sell, or hold any security or other investment, or to pursue any investment style or strategy. Nothing in this document shall be construed as advice that purports to be tailored to your needs or the needs of any person or company receiving the advice. The information in this document is intended for general circulation only and does not constitute investment advice. Nothing in this document is published with regard to the specific investment objectives, financial situation and particular needs of any person who may receive the information.
Nothing in this document shall be construed as, or form part of, any offer for sale or subscription of or solicitation or invitation of any offer to buy or subscribe for any securities. The data and information made available in this document are of a general nature and do not purport, and shall not in any way be deemed, to constitute an offer or provision of any professional or expert advice, including without limitation any financial, investment, legal, accounting or tax advice, and shall not be relied upon by you in that regard. You should at all times consult a qualified expert or professional adviser to obtain advice and independent verification of the information and data contained herein before acting on it. Any financial or investment information in this document are intended to be for your general information only. You should not rely upon such information in making any particular investment or other decision which should only be made after consulting with a fully qualified financial adviser. Such information do not nor are they intended to constitute any form of financial or investment advice, opinion or recommendation about any investment product, or any inducement or invitation relating to any of the products listed or referred to. Any arrangement made between you and a third party named on or linked to from these pages is at your sole risk and responsibility.
You acknowledge that Beansprout is under no obligation to exercise editorial control over, and to review, edit or amend any data, information, materials or contents of any content in this document. You agree that all statements, offers, information, opinions, materials, content in this document should be used, accepted and relied upon only with care and discretion and at your own risk, and Beansprout shall not be responsible for any loss, damage or liability incurred by you arising from such use or reliance.
This document (including all information and materials contained in this document) is provided “as is”. Although the material in this document is based upon information that Beansprout considers reliable and endeavours to keep current, Beansprout does not assure that this material is accurate, current or complete and is not providing any warranties or representations regarding the material contained in this document. All opinions contained herein constitute the views of the analyst(s) named in this report, they are subject to change without notice and are not intended to provide the sole basis of any evaluation of the subject securities and companies mentioned in this report. Any reference to past performance should not be taken as an indication of future performance. To the fullest extent permissible pursuant to applicable law, Beansprout disclaims all warranties and/or representations of any kind with regard to this document, including but not limited to any implied warranties of merchantability, non-infringement of third-party rights, or fitness for a particular purpose.
Beansprout does not warrant, either expressly or impliedly, the accuracy or completeness of the information, text, graphics, links or other items contained in this document. Neither Beansprout nor any of its affiliates, directors, employees or other representatives will be liable for any damages, losses or liabilities of any kind arising out of or in connection with the use of this document. To the best of Beansprout’s knowledge, this document does not contain and is not based on any non-public, material information. The information in this document is not intended for distribution to, or use by, any person or entity in any jurisdiction where such distribution or use would be contrary to law or regulation, or which would subject Beansprout to any registration requirement within such jurisdiction or country. Beansprout is not licensed or regulated by any authority in any jurisdiction or country to provide the information in this document.
As a condition of your use of this document, you agree to indemnify, defend and hold harmless Beansprout and its affiliates, and their respective officers, directors, employees, members, managing members, managers, agents, representatives, successors and assigns from and against any and all actions, causes of action, claims, charges, cost, demands, expenses and damages (including attorneys’ fees and expenses), losses and liabilities or other expenses of any kind that arise directly or indirectly out of or from, arising out of or in connection with violation of these terms, use of this document, violation of the rights of any third party, acts, omissions or negligence of third parties, their directors, employees or agents. To the extent permitted by law, Beansprout shall not be liable to you, any other person, or organization, for any direct, indirect, special, punitive, exemplary, incidental or consequential damages, whether in contract, tort (including negligence), or otherwise, arising in any way from, or in connection with, the use of this document and/or its content. This includes, without limitation, liability for any act or omission in reliance on the information in this document. Beansprout expressly disclaims and excludes all warranties, conditions, representations and terms not expressly set out in this User Agreement, whether express, implied or statutory, with regard to this document and its content, including any implied warranties or representations about the accuracy or completeness of this document and the content, suitability and general availability, or whether it is free from error.
If these terms or any part of them is understood to be illegal, invalid or otherwise unenforceable under the laws of any state or country in which these terms are intended to be effective, then to the extent that they are illegal, invalid or unenforceable, they shall in that state or country be treated as severed and deleted from these terms and the remaining terms shall survive and remain fully intact and in effect and will continue to be binding and enforceable in that state or country.
These terms, as well as any claims arising from or related thereto, are governed by the laws of Singapore without reference to the principles of conflicts of laws thereof. You agree to submit to the personal and exclusive jurisdiction of the courts of Singapore with respect to all disputes arising out of or related to this Agreement. Beansprout and you each hereby irrevocably consent to the jurisdiction of such courts, and each Party hereby waives any claim or defence that such forum is not convenient or proper.
Read also
Gain financial insights in minutes
Subscribe to our free weekly newsletter for more insights to grow your wealth
Most Popular

Comments
0 comments