
1-year T-bill yield jumps to 1.92% despite higher demand
Bonds
By Gerald Wong, CFA • 15 Oct 2026
Why trust Beansprout? We’ve been awarded Best Investment Website at the SIAS Investors’ Choice Awards 2025

Make Beansprout your preferred source on Google
Add us on Google to see more of our insights in your search results
The cut-off yield on the latest 1-year Singapore T-bill rose to 1.92% in the auction on 15 October 2026.
What happened?
The results of the latest 1-year Singapore T-bill auction are out.
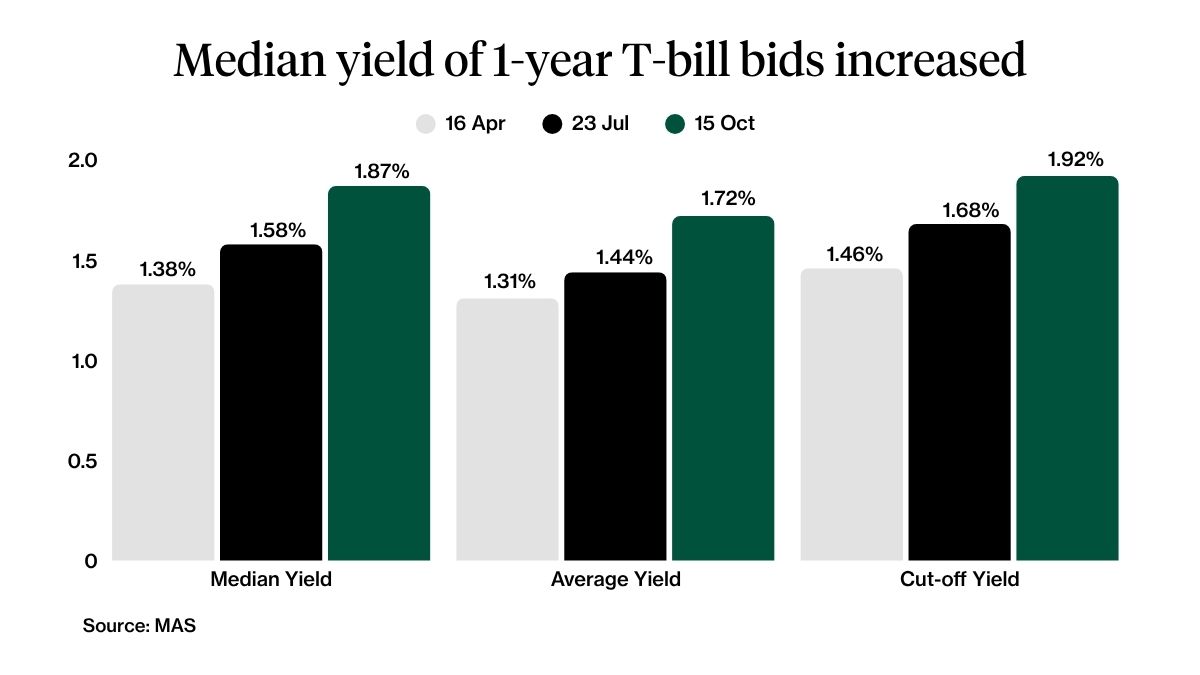
The cut-off yield for the 1-year Singapore T-bill (BY26103X) rose to 1.92% in the auction on 15 October.
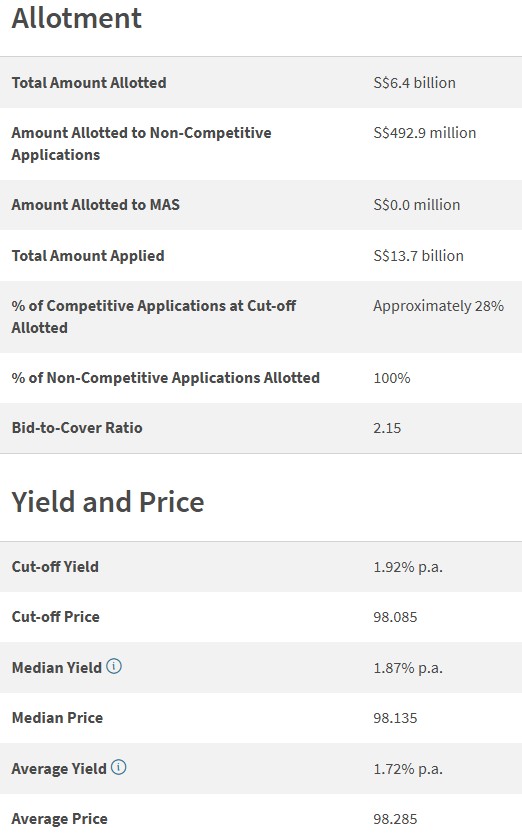
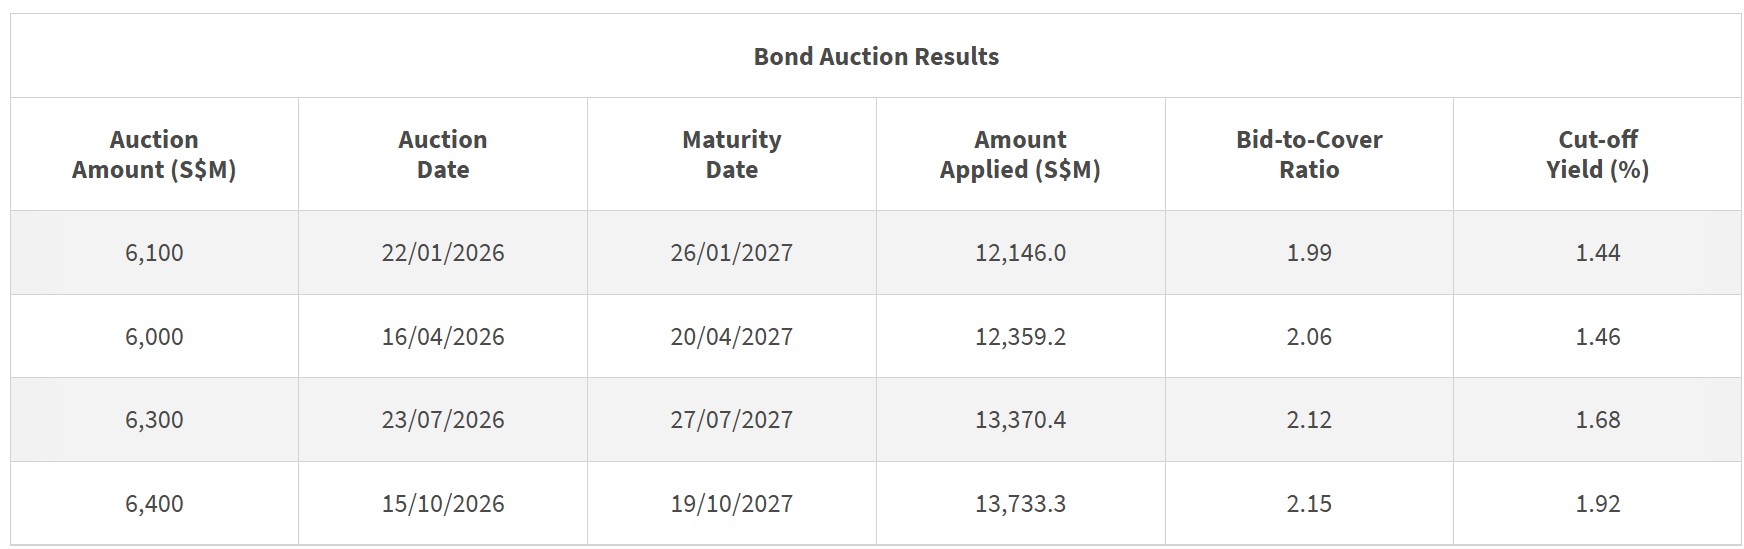
This latest 1-year T-bill yield is higher than the yield of 1.68% in the previous 1-year T-bill auction.
It also marks a change from last week, when we shared that the 1-year T-bill yield was lower than the 6-month T-bill yield
What caught my attention was that the yield increased despite stronger demand for the 1-year T-bill.
In this article, we will find out what is driving the jump in the Singapore T-bill yield, and if there are other ways to earn a yield of above 1.92%.
What we learnt from the latest 1-year Singapore T-bill auction
#1 – Stronger demand for 1-year T-bill compared to the previous auction
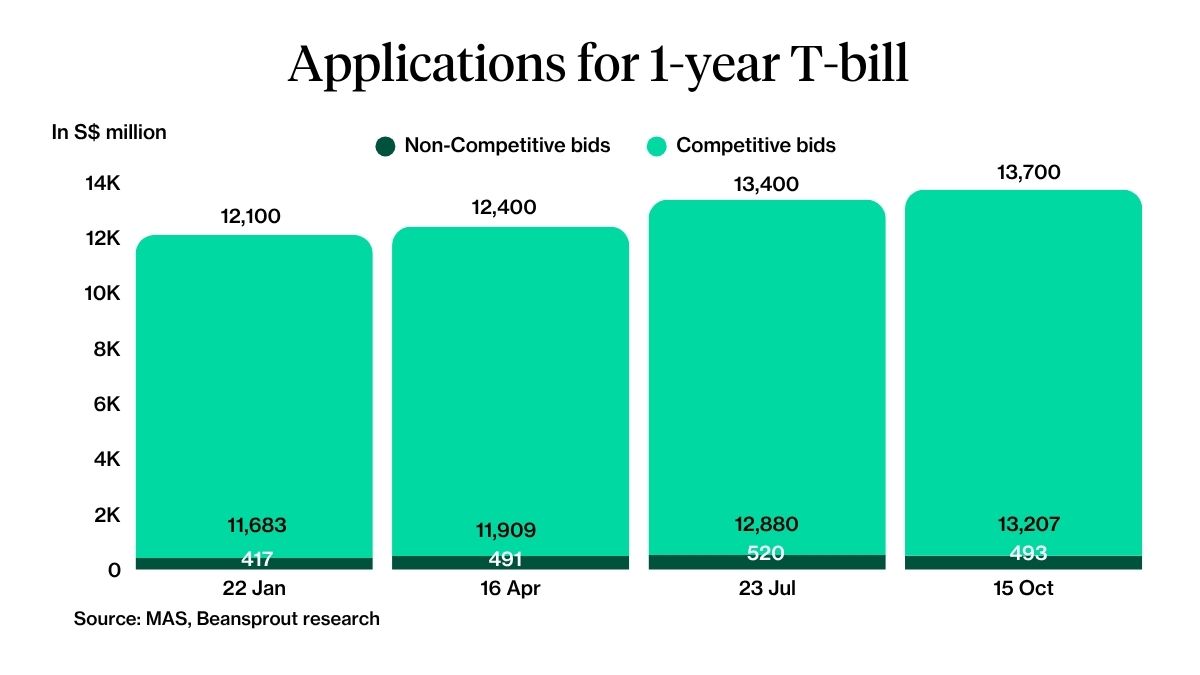
Total applications for the latest Singapore 1-year T-bill increased to S$13.7 billion, up from S$13.4 billion in the previous 1-year T-bill auction on 23 July 2026.
The amount of non-competitive bids fell slightly to S$492.9 million from about S$520 million in the previous auction.
Since the S$492.9 million in non-competitive bids fell within the allocation limit, eligible non-competitive bids received a full 100% allocation at a cut-off yield of 1.92% p.a.
Meanwhile, the amount of competitive bids increased to approximately S$13.24 billion from S$12.85 billion in the previous auction. This means the increase in total applications was driven by competitive bids.
Demand also remains elevated compared to the auctions in January, April and July 2026.
#2 – Higher average and median yield for bids submitted
The average yield of submitted bids rose to 1.72%, up from 1.44% in July's auction.
Similarly, the median yield increased to 1.87%, from 1.58% previously.
This extends the uptrend in short-term bond yields, reversing the broad decline seen through most of 2025.
What would Beansprout do?
The jump in the cut-off yield for the latest 1-year Singapore T-bill to 1.92% appears to reflect higher yields on submitted bids, in line with the increase in Singapore T-bill yields in recent months.
While the yield has moved higher, we would still compare alternatives based on when we may need the money.
My first step would be to make sure I have sufficient cash set aside for emergencies and upcoming expenses through my liquidity pot, within Beansprout’s four pots of wealth.
I would then consider how to earn a higher return on this cash while keeping it accessible when I need it.
The 1-year T-bill yield of 1.92% is slightly higher than that of the latest 6-month T-bill yield of 1.90% on 8 October. Choosing a 1-year T-bill provides certainty over the return for a longer period and reduces the need to reinvest after six months. However, it also means committing funds for longer if interest rates rise further.
Despite the increase, the 1-year T-bill yield remains below the best 12-month fixed deposit rate in our comparison of 2.10% p.a.
For longer-term savings, we would also consider the Singapore Savings Bonds (SSB), with the latest November 2026 issue offering a first-year return of 1.67% and an average annual return of 2.45% if held for 10 years, with the flexibility to redeem monthly before maturity.
For cash I may need at short notice, I would also consider savings accounts offering competitive interest rates, while checking the requirements to earn bonus interest.
To compare between fixed deposits, T-bills, savings account and SSBs, check out our guide to the best places to park your cash in October 2026.
Ultimately, the best option depends on whether I prioritise a slightly higher locked-in yield today, or greater flexibility for my cash.
With my liquidity pot properly set up, I can stay invested through market ups and downs without worrying about being forced to sell my investments at the wrong time. Learn more about the liquidity pot here.
Longbridge is running a promotion offering 10% p.a. interest boost on S$3,600 with Longbridge Cash Plus for 90 days (worth up to S$88). Also, get a free S$80 Fairprice voucher within 5 working days when you sign up for a Longbridge account via Beansprout. Promo ends on 31 October 2026. Learn more about the Longbridge promo here.
To learn more about T-bills and find out how to apply, check out our comprehensive guide to T-bills.
Do you prefer to park your cash in T-bills, SSB or fixed deposits? Share with us in the comments below or in our Telegram group!
Enjoyed this insight? Follow Beansprout on Telegram, Youtube, Facebook and Instagram, and add Beansprout as your preferred source on Google so you never miss an update.
Read also
Gain financial insights in minutes
Subscribe to our free weekly newsletter for more insights to grow your wealth
Most Popular

Comments
0 comments