
6-month T-bill yield rises to 2026 high of 2.07%. Here’s what pushed yields higher
Bonds
By Gerald Wong, CFA • 19 Nov 2026
Why trust Beansprout? We’ve been awarded Best Investment Website at the SIAS Investors’ Choice Awards

Make Beansprout your preferred source on Google
Add us on Google to see more of our insights in your search results
The cut-off yield for the 6-month Singapore T-bill rises to 2.07% p.a. at the latest auction on 19 November 2026.
What happened?
The latest 6-month Singapore T-bill auction results have been released.
The cut-off yield on the latest 6-month Singapore T-bill (BS26123A) rose to 2.07% at the 19 November 2026 auction.
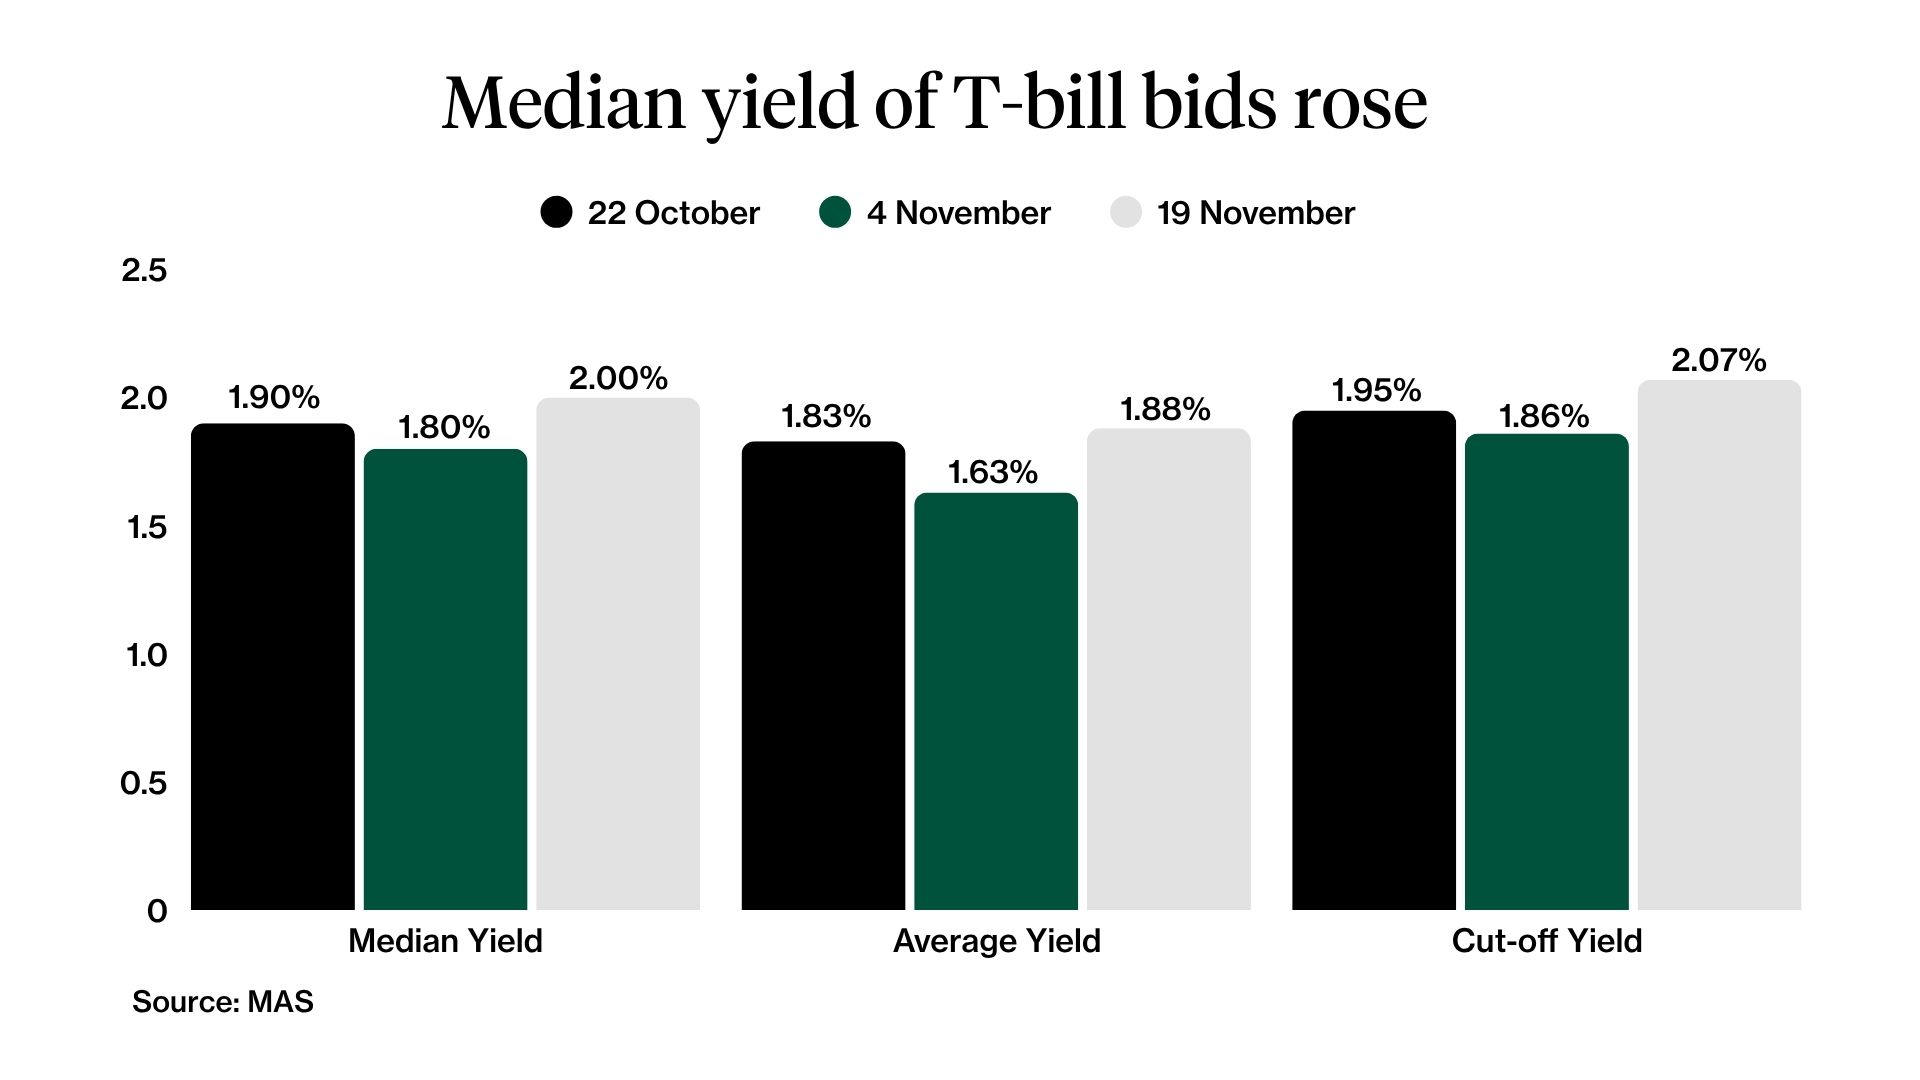
The increase of 21 basis points from 1.86% in the previous auction on 4 November takes the cut-off yield to a new high for 2026, surpassing the previous peak of 1.95% on 22 October.
We recently shared how higher bond yields have improved income opportunities, although inflation and uncertainty over the US Federal Reserve's interest rate outlook remain key risks.
We also compared T-bills, fixed deposits and Singapore Savings Bonds (SSBs) in November, amid discussions in the Beansprout Telegram community about where to park spare cash as fixed deposit rates continue to climb.
In this article, I’ll look at what may have driven the rise in the T-bill yield and how the latest yield compares with fixed deposits and other options for spare cash.
What we learnt from the latest 6-month Singapore T-bill auction
#1 - Demand for the Singapore T-bill fell sharply
Total applications for the 6-month Singapore T-bill fell to S$17.1 billion at the latest auction on 19 November, down from S$20.8 billion at the previous auction on 4 November.
This is a decrease of S$3.7 billion, or approximately 17.8%.
The previous auction on 4 November marked the highest levels of applications in 2026.
This may help to explain why the cut-off yield has risen from the previous auction.
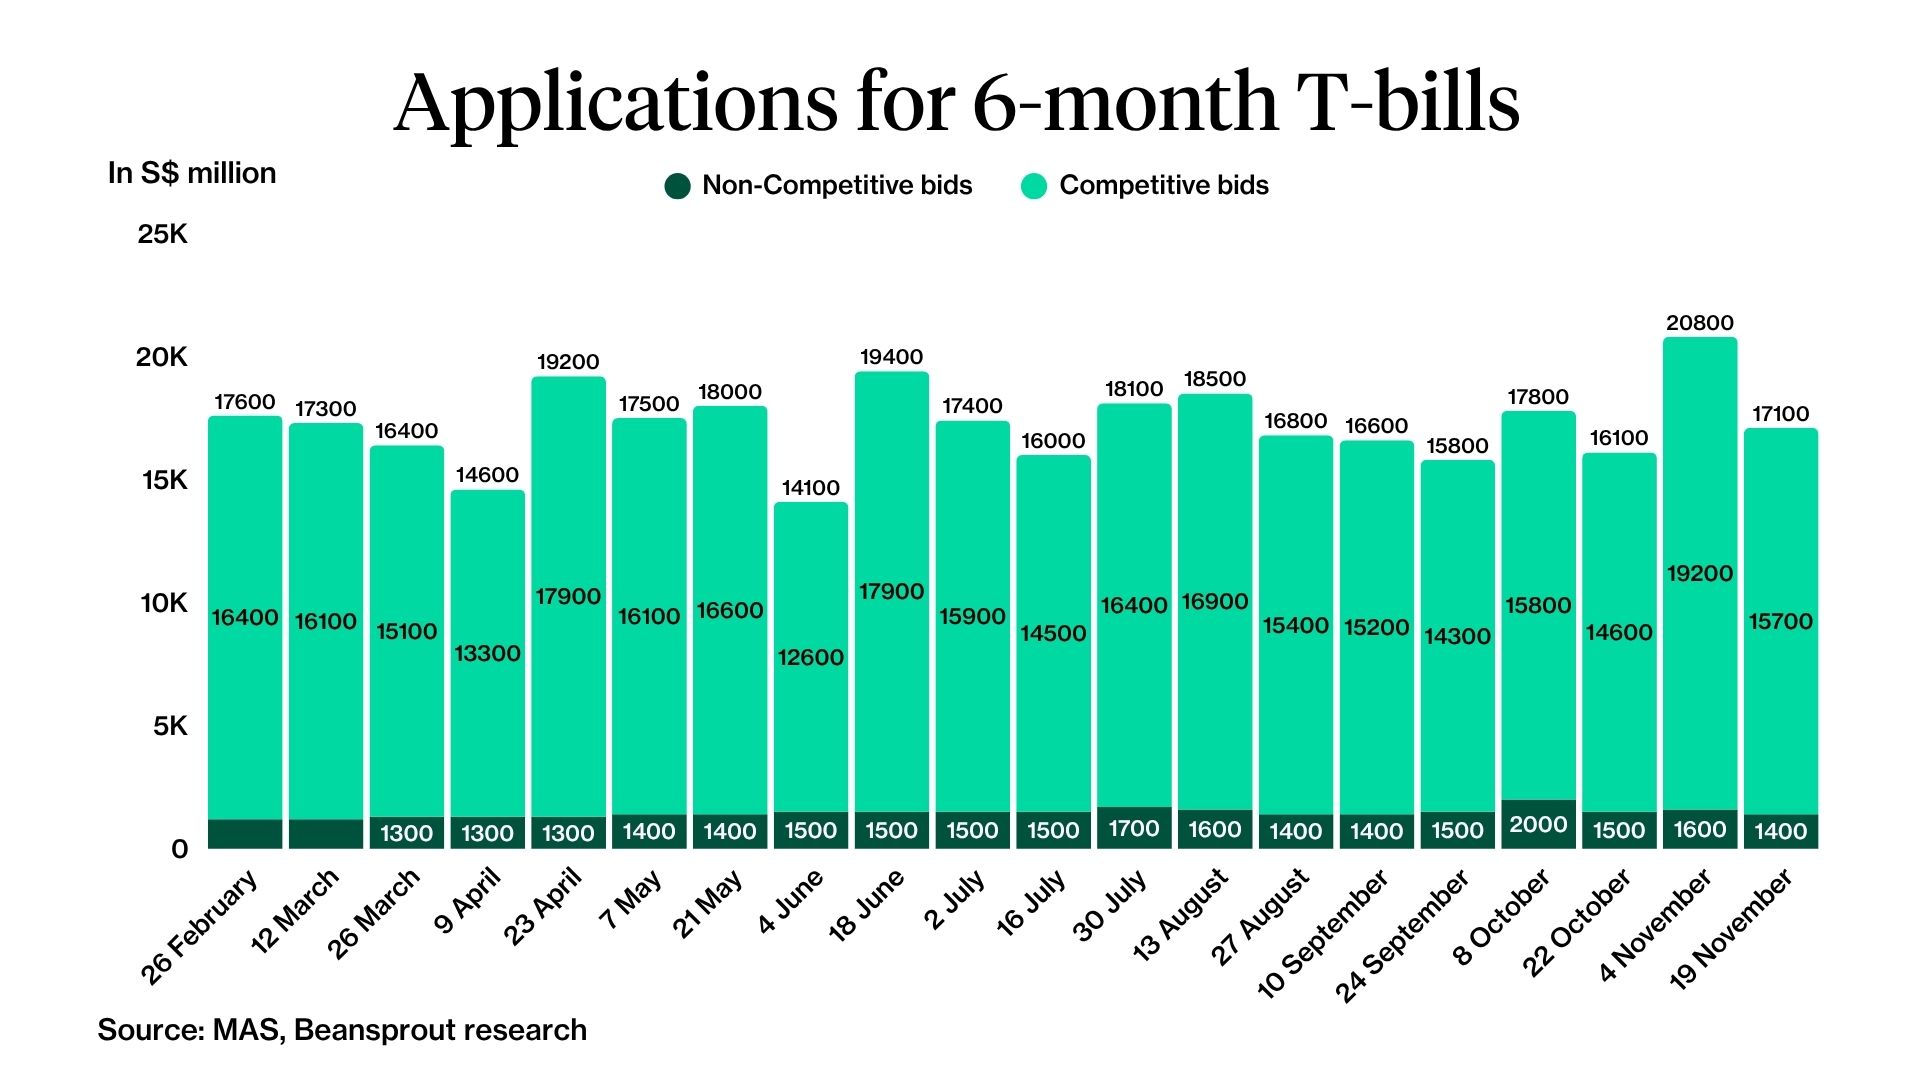
The amount of competitive bids fell to approximately S$15.7 billion on 19 November, from S$19.2 billion on 4 November.
If you placed a competitive bid below 2.07%, you would receive 100% of your requested T-bill allocation.
If you bid at exactly 2.07%, the allocation would be around 90%.
The amount allotted to non-competitive applications also fell to S$1.4 billion, from S$1.6 billion in the previous auction on 4 November.
Since the amount of non-competitive bids was within the allocation limit, all eligible non-competitive bids received full allocation for the T-bill.
#2 - T-bills issued rose
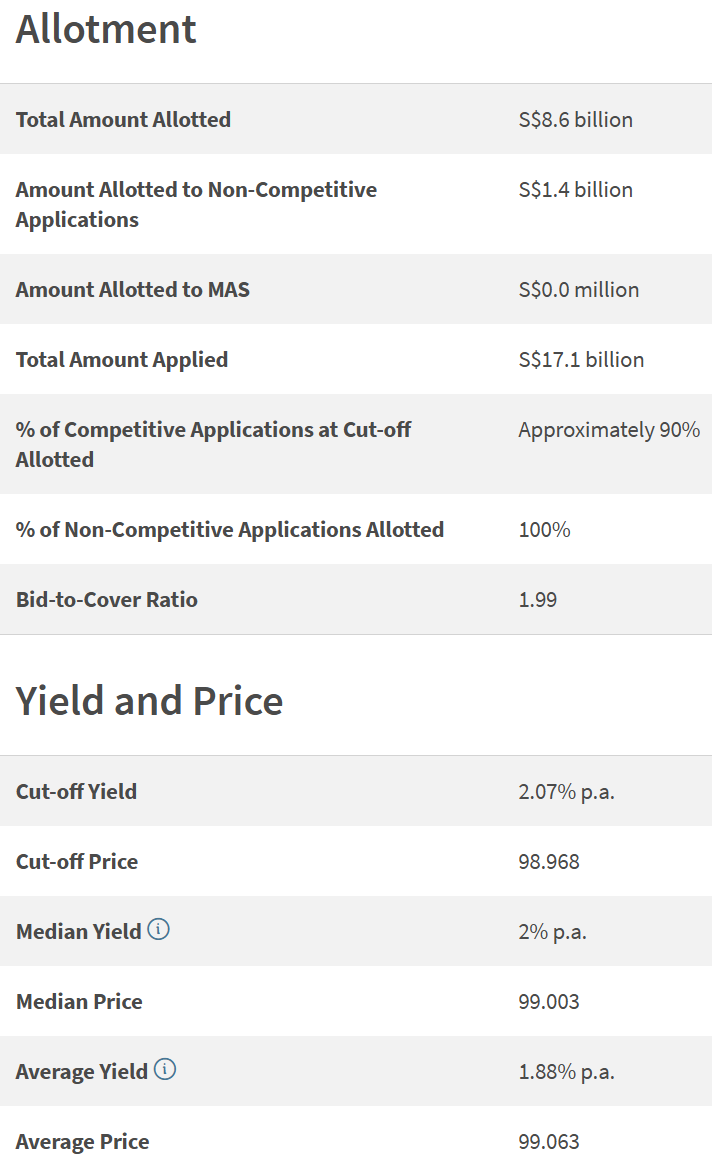
The amount of T-bills allotted rose to S$8.6 billion, from S$8.5 billion in the previous auction on 4 November.
With the sharp fall in total applications and the rise in amount allotted, the ratio of applications to T-bills allotted (bid-to-cover ratio) fell sharply to 1.99x from 2.45x in the previous auction.

#3 - Median yield of bids submitted rose sharply
The median yield of submitted bids rose sharply to 2.00%, from 1.80% in the previous T-bill auction on 4 November.
The average yield of submitted bids also increased sharply to 1.88% from 1.63%.
The median yield of 2.00% was higher than the average yield of 1.88%, suggesting that the distribution of submitted bids was not symmetrical.
This also suggests that investors submitted bids at higher yields compared with the previous auction, which may have contributed to the higher cut-off yield.
What would Beansprout do?
The 6-month T-bill cut-off yield rose to 2.07% in the latest auction, up from 1.86% previously.
This marks the highest cut-off yield so far in 2026, up from the previous high of 1.95% at the 22 October auction.
As we shared in our November bond market outlook, the US Federal Reserve's October meeting reinforced expectations that interest rates could remain elevated for longer, as inflation concerns persist. This could continue to support global bond yields and influence Singapore T-bill yields.
In our view, lower demand, a higher issuance size and higher yields submitted by investors may have contributed to the increase in the cut-off yield.
With the recent movement in interest rates, I have been reviewing where to park my cash to earn a higher yield, while having sufficient security and peace of mind.
The first step is to make sure I have sufficient cash put aside for emergency uses through my Liquidity Pot within Beansprout's four pots of wealth.
Then, I would see how I can earn a higher yield on this pot of emergency cash, while maintaining the liquidity I may need. Learn more about the liquidity pot here.
The T-bill yield of 2.07% is lower than the best 6-month fixed deposit rate of 2.30% p.a., as well as the best 12-month fixed deposit rate of 2.30% p.a.
Another option to consider is the Singapore Savings Bond (SSB), which the current issuance offers a first-year return of 1.83% and average annual return of 2.39% over 10 years, while having the flexibility to redeem prior to maturity.
There are also savings accounts in Singapore offering interest rates above 2.25% p.a. worth considering if you prefer to keep your cash more accessible.
For more liquidity than T-bills or fixed deposits, I may also consider money market funds, while remembering that they are not capital guaranteed and are not insured under SDIC.
To find out where you can earn a higher yield on your spare cash, check out our latest comparison of T-bills, fixed deposits and Singapore Savings Bonds (SSBs) in November.
By finding the best place to park my cash, I can build a stable Liquidity Pot that allows the rest of my portfolio to remain invested through market volatility without being forced to sell at the wrong time.
For a broader introduction to bonds, read our beginner’s guide to bond investing in Singapore, including how coupons, yields and duration work.
Do you prefer to park your cash in T-bills, SSB or fixed deposits? Share with us in the comments below or in our Telegram group!
Enjoyed this insight? Follow Beansprout on Telegram, Youtube, Facebook and Instagram, and add Beansprout as your preferred source on Google so you never miss an update.
Read also
Gain financial insights in minutes
Subscribe to our free weekly newsletter for more insights to grow your wealth
Most Popular

Comments
0 comments