
6-month T-bill yield jumps to 1.95%, highest in 2026. Here’s what drove the increase
Bonds
By Gerald Wong, CFA • 22 Oct 2026
Why trust Beansprout? We’ve been awarded Best Investment Website at the SIAS Investors’ Choice Awards 2025

Make Beansprout your preferred source on Google
Add us on Google to see more of our insights in your search results
The cut-off yield for the 6-month Singapore T-bill rises to 1.95% p.a. at the latest auction on 22 October 2026.
What happened?
The latest 6-month Singapore T-bill auction results are out.
The cut-off yield for the 6-month Singapore T-bill (BS26121N) climbed to 1.95% at the auction on 22 October 2026.
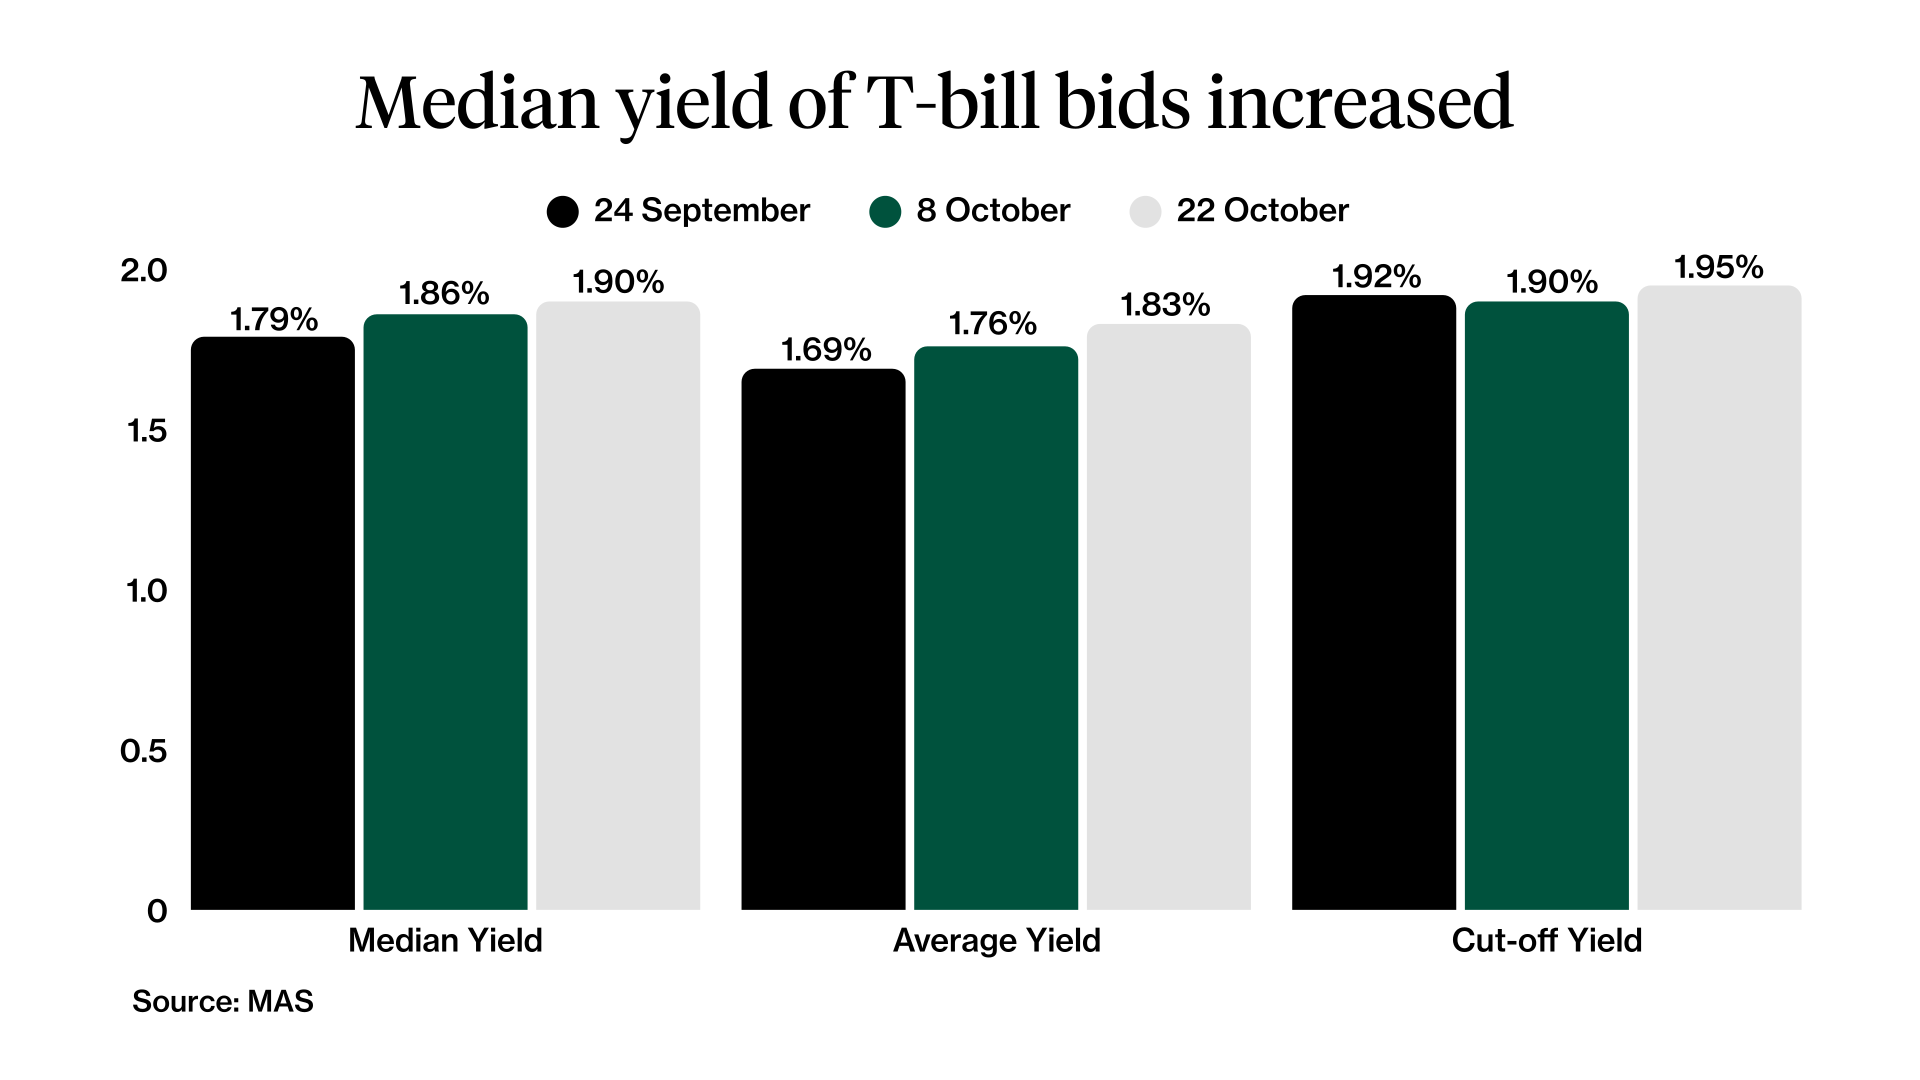
This was an increase of 5 basis points from 1.90% in the previous auction on 8 October 2026.
This marks the highest six-month T-bill cut-off yield so far in 2026, surpassing the previous high of 1.92% recorded on 24 September.
We recently explored how rising global bond yields could influence Singapore government bond yields, potentially keeping T-bill yields elevated.
I have seen ongoing discussion in the Beansprout Telegram community about where to park our cash, especially as fixed deposit rates have continued to rise.
In this article, I’ll look at what drove the increase in T-bill yield and how it compares with other options for earning a higher return on our spare cash.
What we learnt from the latest 6-month Singapore T-bill auction
#1 - Demand for the Singapore T-bill fell
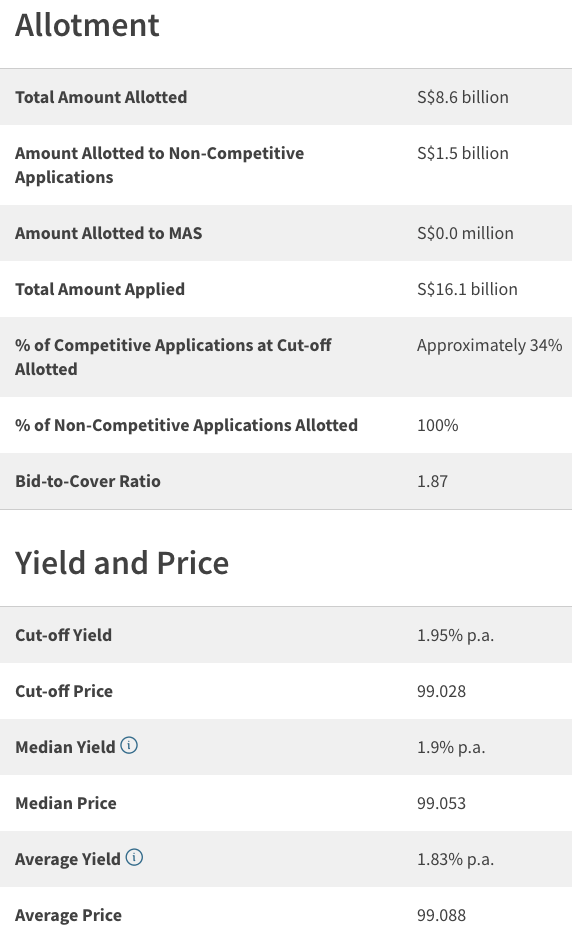
Total applications for the 6-month Singapore T-bill fell to S$16.1 billion in the latest auction on 22 October, from S$17.8 billion in the previous auction on 8 October.
This represents a decrease of S$1.7 billion, or about 9.6%.
T-bill applications had previously reached S$19.4 billion in the auction on 18 June, the highest level recorded since the start of the year.
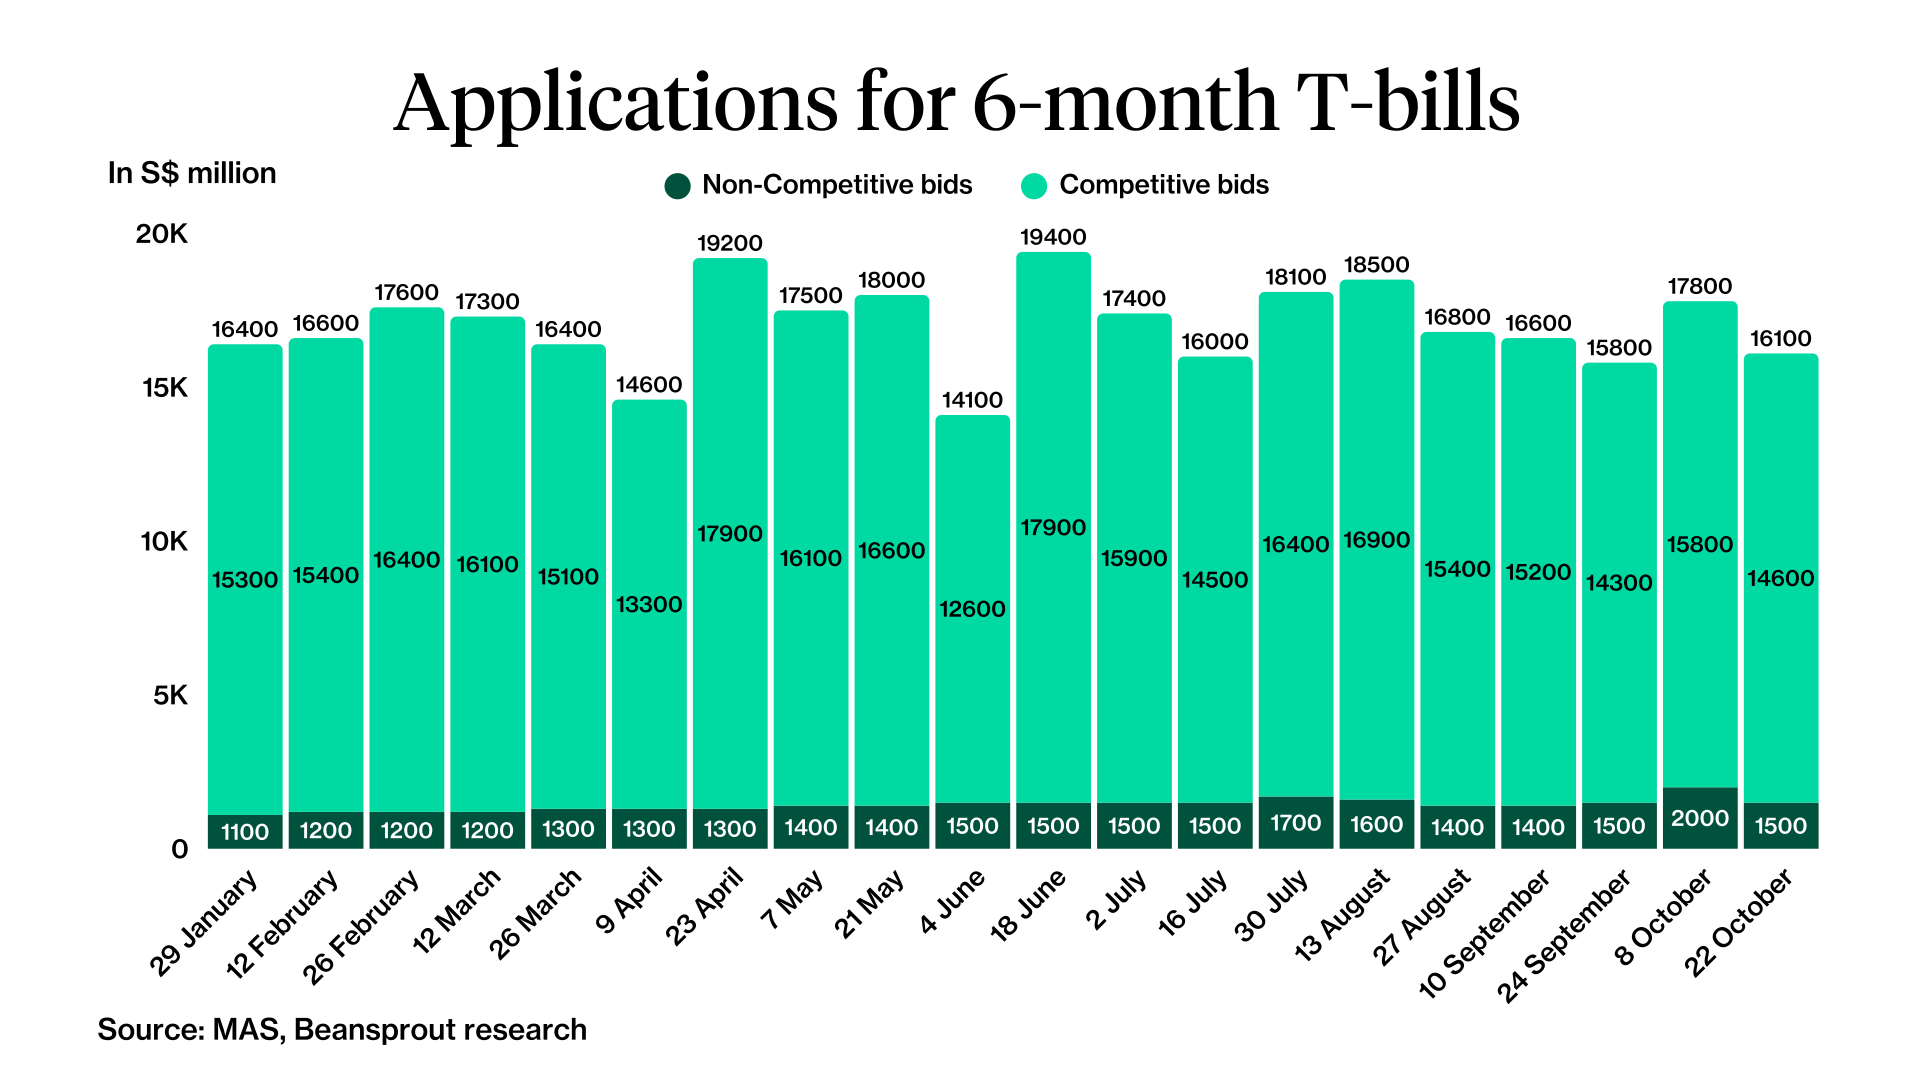
The amount of competitive bids fell to approximately S$14.6 billion on 22 October, from S$15.8 billion on 8 October.
If you placed a competitive bid below 1.95%, you would receive 100% of your requested T-bill allocation.
If you bid at exactly 1.95%, the allocation would be around 34%.
The amount allotted to non-competitive applications also fell to S$1.5 billion, from S$2.0 billion in the previous auction on 8 October.
Since the amount of non-competitive bids was within the allocation limit, all eligible non-competitive bids received full allocation for the T-bill.
#2 - T-bills issued rose
The amount of T-bills allotted rose to S$8.6 billion, from S$8.3 billion in the previous auction on 8 October.
With the decrease in total applications and the rise in amount allotted, the ratio of applications to T-bills allotted (bid-to-cover ratio) fell to 1.87x from 2.14x in the previous auction.

#3 - Median yield of bids submitted continued to rise
The median yield of submitted bids rose to 1.90%, from 1.86% in the previous T-bill auction on 8 October.
The average yield of submitted bids also increased to 1.83% from 1.76%.
This suggests that investors continued to submit bids at higher yields, potentially reflecting the recent increase in bond yields in the US and globally.
The gap between the median yield of 1.90% and the cut-off yield of 1.95% is narrow, suggesting that the yields submitted by investors were closer to the final cut-off yield.
What would Beansprout do?
The 6-month T-bill cut-off yield climbed to 1.95% in the latest auction, up from 1.90% previously.
This marks a new high for 2026, surpassing the previous peak of 1.92% at the auction on 24 September 2026.
The US Federal Reserve increased interest rates in September for the first time since 2023, against a backdrop of rising global bond yields.
Higher yields among successful competitive bids, weaker demand and a larger issuance size were consistent with upward pressure on the cut-off yield.
With the recent movement in interest rates, I have been reviewing where to park my cash to earn a higher yield, while having sufficient security and peace of mind.
The first step is to make sure I have sufficient cash put aside for emergency uses through my Liquidity Pot within Beansprout's four pots of wealth.
Then, I would see how I can earn a higher yield on this pot of emergency cash, while maintaining the liquidity I may need. Learn more about the liquidity pot here.
The T-bill yield of 1.95% is lower than the best 6-month fixed deposit rate of 2.05% p.a., as well as the best 12-month fixed deposit rate of 2.10% p.a.
Another option to consider is the Singapore Savings Bond (SSB), which the current issuance offers a first-year return of 1.67% and average annual return of 2.45% over 10 years, while having the flexibility to redeem prior to maturity.
There are also savings accounts in Singapore offering interest rates above 1.95% p.a. worth considering if you prefer to keep your cash more accessible.
For more liquidity than T-bills or fixed deposits, I may also consider money market funds, while remembering that they are not capital guaranteed and are not insured under SDIC.
Longbridge is running a promotion offering 10% p.a. interest boost on S$3,600 with Longbridge Cash Plus for 90 days (worth up to S$88). Also, get a free S$80 Fairprice voucher within 5 working days when you sign up for a Longbridge account via Beansprout. Promo ends on 31 October 2026. Learn more about the Longbridge promo here.
By finding the best place to park my cash, I can build a stable Liquidity Pot that allows the rest of my portfolio to remain invested through market volatility without being forced to sell at the wrong time.
For a broader introduction to bonds, read our beginner’s guide to bond investing in Singapore, including how coupons, yields and duration work.
Do you prefer to park your cash in T-bills, SSB or fixed deposits? Share with us in the comments below or in our Telegram group!
Enjoyed this insight? Follow Beansprout on Telegram, Youtube, Facebook and Instagram, and add Beansprout as your preferred source on Google so you never miss an update.
Read also
Gain financial insights in minutes
Subscribe to our free weekly newsletter for more insights to grow your wealth
Most Popular

Comments
0 comments