
6-month T-bill yield falls to 1.86%. Here’s what caused the decline
Bonds
By Gerald Wong, CFA • 04 Nov 2026
Why trust Beansprout? We’ve been awarded Best Investment Website at the SIAS Investors’ Choice Awards 2025

Make Beansprout your preferred source on Google
Add us on Google to see more of our insights in your search results
The cut-off yield for the 6-month Singapore T-bill falls to 1.86% p.a. at the latest auction on 4 November 2026.
What happened?
The latest 6-month Singapore T-bill auction results have been released.
The cut-off yield for the 6-month Singapore T-bill (BS26122V) fell to 1.86% at the auction on 4 November 2026.
This follows a 2026 high of 1.95% at the previous auction on 22 October 2026.
We recently looked at how rising global bond yields could affect Singapore government bond yields, potentially keeping T-bill yields elevated.
I have also seen continued discussion in the Beansprout Telegram community about where to park our cash, particularly as fixed deposit rates have continued to rise.
In this article, I’ll explore what drove the decline in the T-bill yield and how it compares with other options for earning a higher return on our spare cash.
What we learnt from the latest 6-month Singapore T-bill auction
#1 - Demand for the Singapore T-bill rose sharply
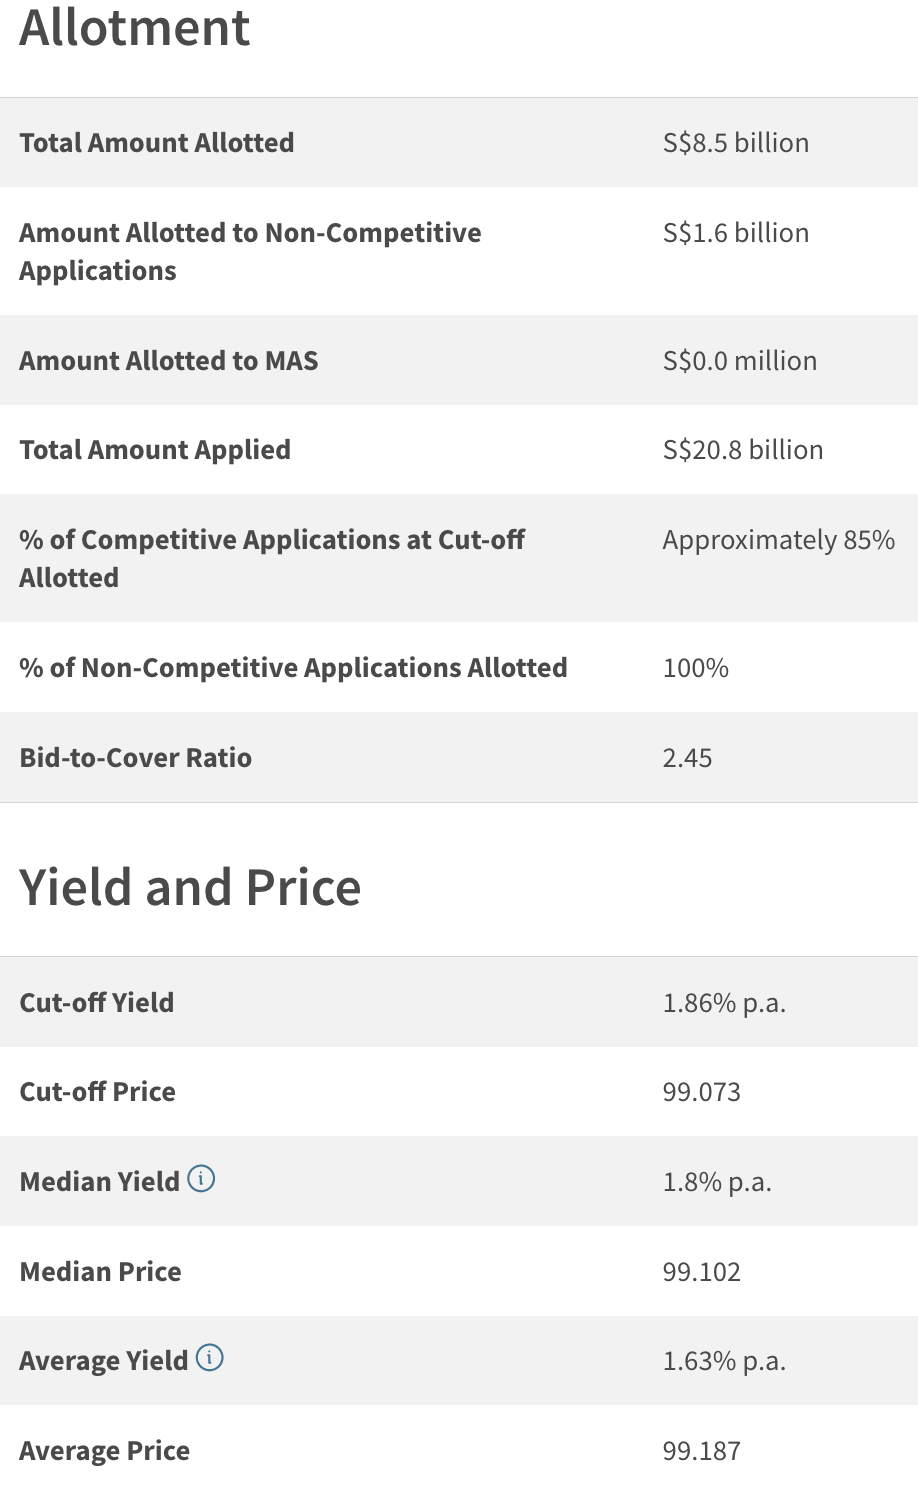
Total applications for the 6-month Singapore T-bill jumped to S$20.8 billion at the latest auction on 4 November, up from S$16.1 billion at the previous auction on 22 October.
This is an increase of S$4.7 billion, or approximately 29.2%.
This also marks the highest levels of applications in 2026, surpassing the previous peak of S$19.4 billion at the auction on 18 June.
This may help to explain why the cut-off yield has fallen from the previous auction.
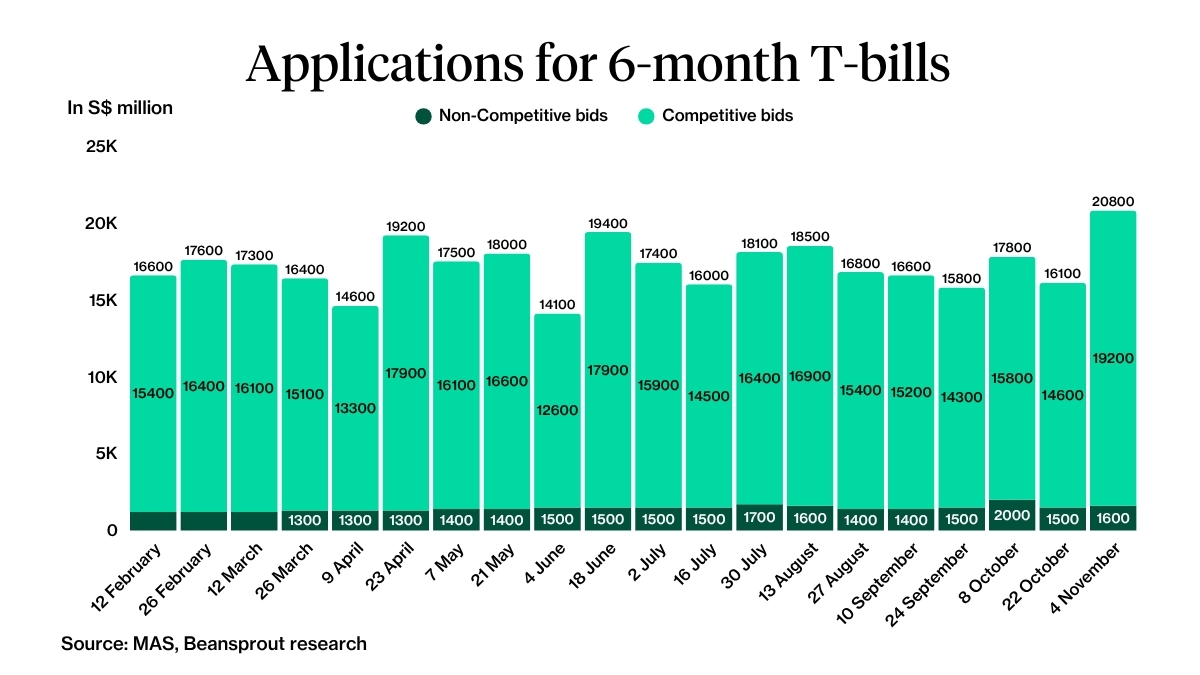
The amount of competitive bids rose to approximately S$19.2 billion on 4 November, from S$14.6 billion on 22 October.
If you placed a competitive bid below 1.86%, you would receive 100% of your requested T-bill allocation.
If you bid at exactly 1.86%, the allocation would be around 85%.
The amount allotted to non-competitive applications also rose to S$1.6 billion, from S$1.5 billion in the previous auction on 22 October.
Since the amount of non-competitive bids was within the allocation limit, all eligible non-competitive bids received full allocation for the T-bill.
#2 - T-bills issued fell
The amount of T-bills allotted fell to S$8.5 billion, from S$8.6 billion in the previous auction on 22 October.
With the sharp rise in total applications and the fall in amount allotted, the ratio of applications to T-bills allotted (bid-to-cover ratio) rose sharply to 2.45x from 1.87x in the previous auction.

#3 - Median yield of bids submitted fell
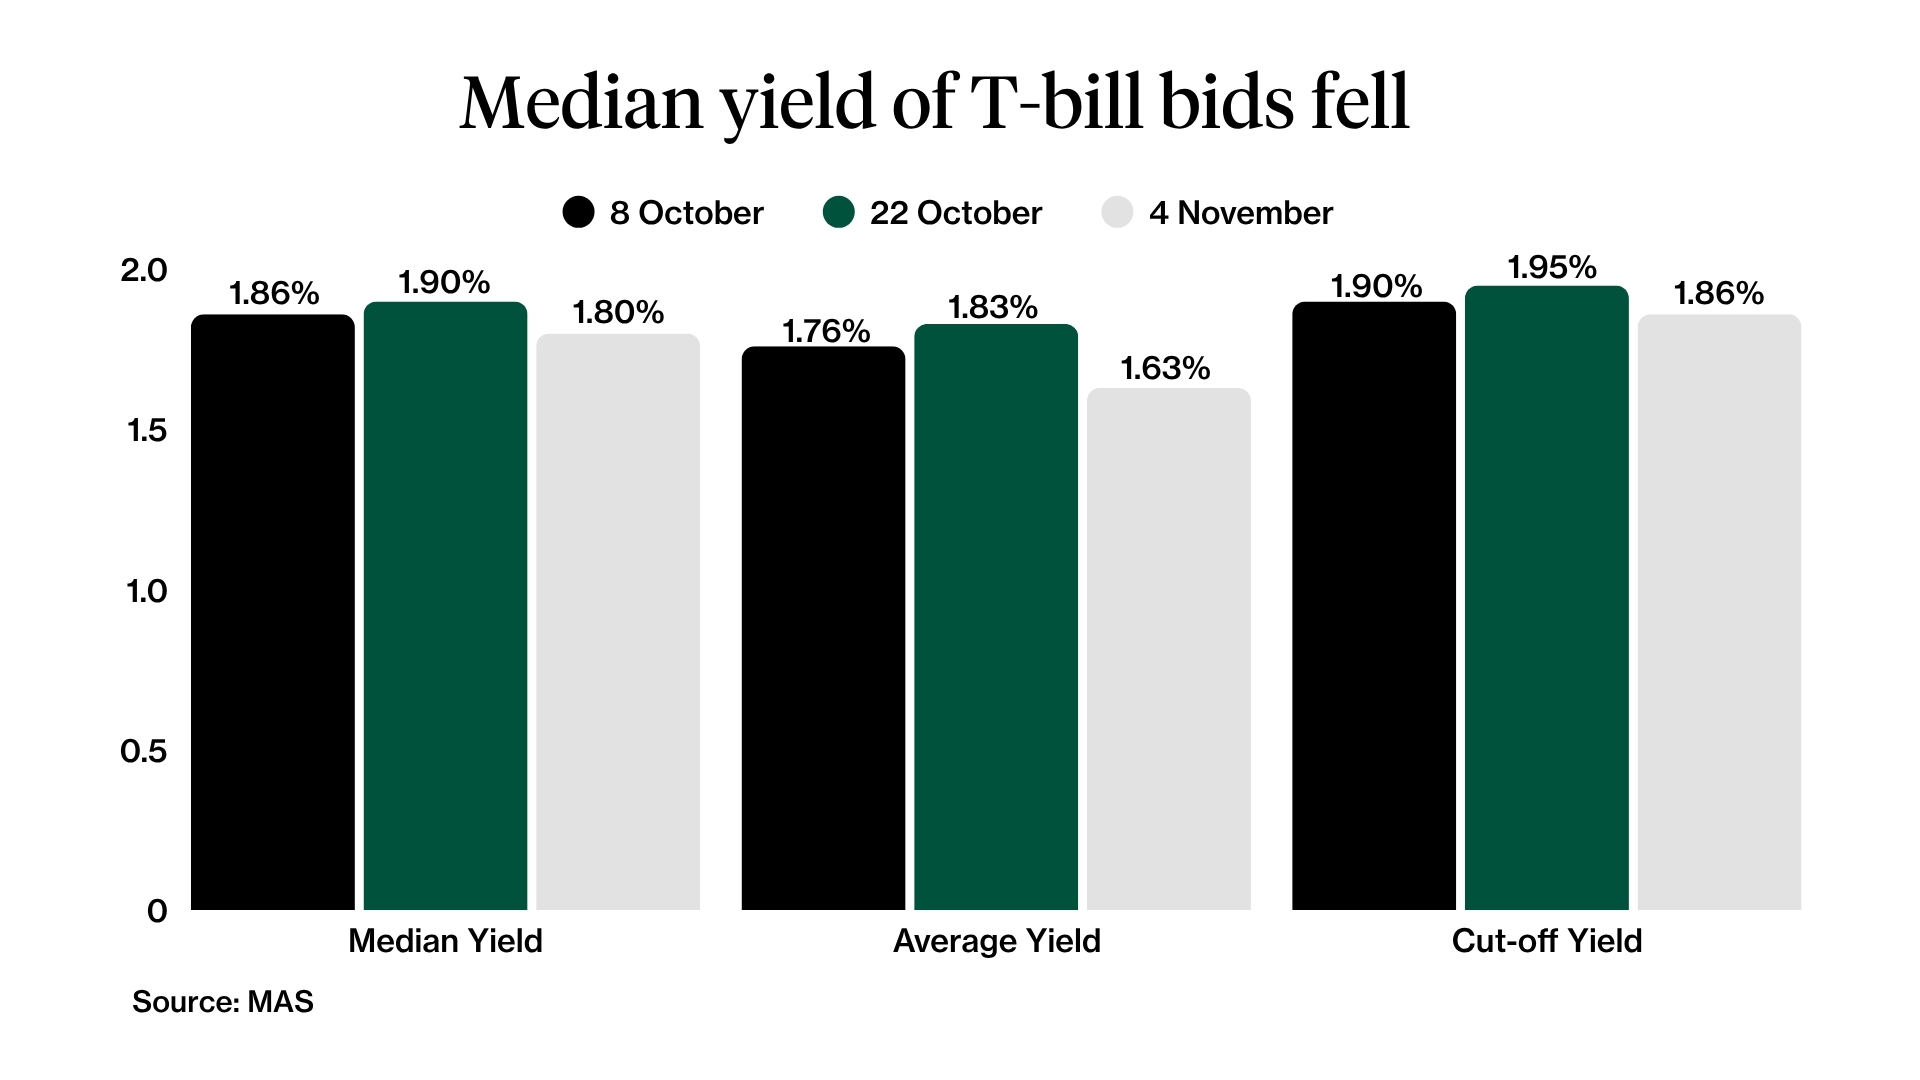
The median yield of submitted bids fell to 1.80%, from 1.90% in the previous T-bill auction on 22 October.
The average yield of submitted bids also decreased sharply to 1.63% from 1.83%.
The gap between the median yield of 1.80% and the average yield of 1.63% is large, suggesting that the yields submitted by investors were very spread apart.
What would Beansprout do?
The 6-month T-bill cut-off yield fell to 1.86% in the latest auction, down from 1.95% previously.
The previous auction marked a new high for 2026, surpassing the previous peak of 1.92% at the auction on 24 September 2026.
The US Federal Reserve increased interest rates in September for the first time since 2023, against a backdrop of rising global bond yields.
Much higher demand and a smaller issuance size were the main factors driving the downward pressure on the cut-off yield.
With the recent movement in interest rates, I have been reviewing where to park my cash to earn a higher yield, while having sufficient security and peace of mind.
The first step is to make sure I have sufficient cash put aside for emergency uses through my Liquidity Pot within Beansprout's four pots of wealth.
Then, I would see how I can earn a higher yield on this pot of emergency cash, while maintaining the liquidity I may need. Learn more about the liquidity pot here.
The T-bill yield of 1.86% is lower than the best 6-month fixed deposit rate of 2.10% p.a., as well as the best 12-month fixed deposit rate of 2.19% p.a.
Another option to consider is the Singapore Savings Bond (SSB), which the current issuance offers a first-year return of 1.83% and average annual return of 2.39% over 10 years, while having the flexibility to redeem prior to maturity.
There are also savings accounts in Singapore offering interest rates above 1.86% p.a. worth considering if you prefer to keep your cash more accessible.
For more liquidity than T-bills or fixed deposits, I may also consider money market funds, while remembering that they are not capital guaranteed and are not insured under SDIC.
By finding the best place to park my cash, I can build a stable Liquidity Pot that allows the rest of my portfolio to remain invested through market volatility without being forced to sell at the wrong time.
For a broader introduction to bonds, read our beginner’s guide to bond investing in Singapore, including how coupons, yields and duration work.
Do you prefer to park your cash in T-bills, SSB or fixed deposits? Share with us in the comments below or in our Telegram group!
Enjoyed this insight? Follow Beansprout on Telegram, Youtube, Facebook and Instagram, and add Beansprout as your preferred source on Google so you never miss an update.
Read also
Gain financial insights in minutes
Subscribe to our free weekly newsletter for more insights to grow your wealth
Most Popular

Comments
0 comments