
15-year SGS bond auction: What yield to expect on 28 September
Bonds
By Gerald Wong, CFA • 23 Sep 2026
Why trust Beansprout? We’ve been awarded Best Investment Website at the SIAS Investors’ Choice Awards 2025

Make Beansprout your preferred source on Google
Add us on Google to see more of our insights in your search results
The closing yield on the 15-year Singapore government bond (SGS) was at 2.43% on 22 September 2026. We compare it with T-bills, fixed deposits and SSBs before the auction.
What happened?
There will be a 15-year Singapore government bond auction (NY25200N) coming up on 28 September.
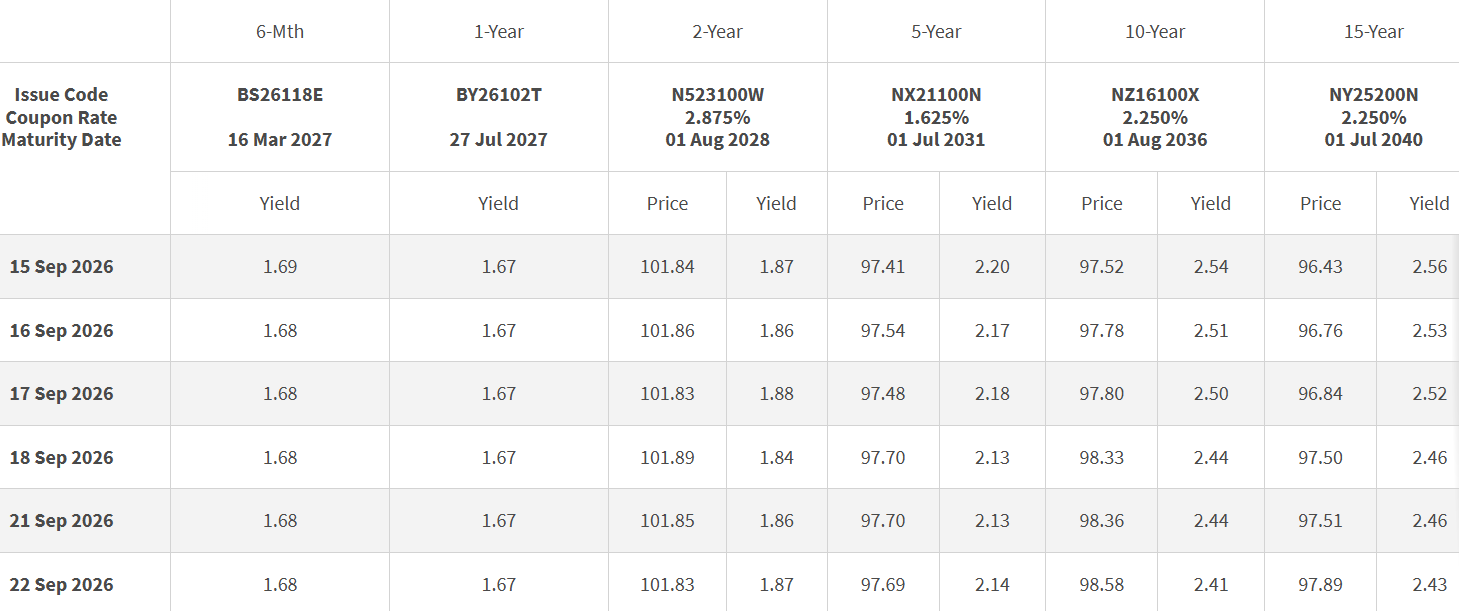
In recent weeks, we have seen Singapore T-bill and government bond yields move higher.
Last month, we also saw the 10-year SGS bond offer a cut-off yield of 2.3%.
This comes as the 30-year US government bond yield recently climbed to around 5.4%, its highest level since 2007, before easing again.
With more attention on bond yields in the Beansprout community, I will explore the likely yield on the reopened 15 year Singapore government bond auction, explain how a reopened auction works, and compare it with T-bills, fixed deposits and Singapore Savings Bonds in this article.
What are the details of the 15-year SGS bond auction?
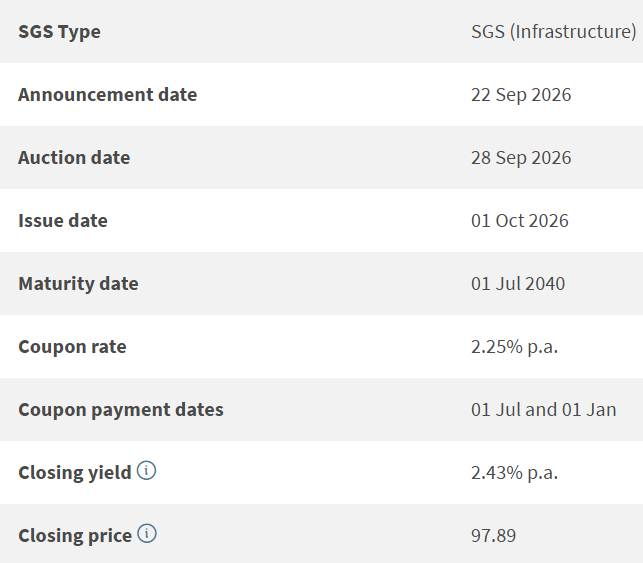
The reopened 15-year SGS bond (NY25200N) will be issued on 1 October 2026, and will mature on 1 July 2040.
The bond is categorised under the 15-year SGS auction schedule, but its actual remaining maturity from 1 October 2026 is about 13 years and 9 months.
This distinction is important when considering how long the funds will be committed.
The bond offers a coupon rate of 2.25% p.a., and the coupon will be paid every six months, on 1 January and 1 July.
What is a reopened SGS bond auction?
The latest auction is a reopened auction, where MAS issues more of an existing bond. This increases the total amount of that bond in circulation.
A reopened bond has the same issue code, coupon rate, coupon payment dates and maturity date as the existing bond.
The upcoming auction is the second issuance of NY25200N.
NY25200N was first issued on 1 July 2025 as a bond with an initial maturity of 15 years.
At its original auction, the bond was issued with a coupon rate of 2.25% per year and a maturity date of 1 July 2040. The cut-off yield was 2.35%, with a cut-off price of S$98.742 for every S$100 in face value.
Why does the bond offer a closing yield of around 2.43% if it pays a 2.25% coupon?
The coupon rate is not necessarily the yield an investor will earn.
The coupon determines the interest payment based on the face value of the bond.
For example, an investor allotted S$1,000 in principal would receive:
- S$22.50 in coupon payments each year
- S$11.25 every six months
- S$1,000 in principal when the bond matures
However, the final price paid for the bond will be decided at the auction.
Although the bond pays interest at a rate of 2.25% a year, investors may have to pay less than S$100 to receive S$100 back when the bond matures.
For example, NY25200N closed at S$97.89 for every S$100 that will be repaid on 1 July 2040, before including any interest that had already built up.
An investor buying at this price would receive the 2.25% coupon payments, as well as S$100 at maturity despite paying S$97.89.
This difference increases the investor’s actual return.
After taking into account the interest received, the purchase price and the amount repaid at maturity, the return would be closer to 2.43% a year, rather than the stated interest rate of 2.25%.
We can see the same relationship in another bond’s earlier auctions as well.
When N524100X was first issued in April 2024, the cut-off yield was 3.06% a year. Investors paid slightly less than S$100, at S$99.724 for every S$100 that would eventually be repaid.
When the bond was offered again in May 2025, the cut-off yield had fallen to 2.05%. Its price had risen to S$103.989 for every S$100 that would be repaid.
More recently, when the bond was reopened again in July 2026, its cut-off yield fell further to 1.84% p.a. Despite the bond paying a coupon of 3.00% p.a., successful applicants paid S$104.014 for every S$100 in principal, including accrued interest.
I would therefore focus on the auction yield rather than the coupon rate when comparing the bond with other options.
What is the likely yield on the reopened 15-year SGS bond?
The closing yield on the SGS bond being reopened, NY25200N, was 2.43% on 22 September 2026.
In the previous 15-year SGS bond auction on 26 June 2025, the cut-off yield was 2.35%. This was below the benchmark 15-year yield of 2.37% on the day before the auction.
This reflected higher demand for the 15-year SGS bond. If demand remains strong, we may again see the cut-off yield come in below the prevailing market yield.
I would therefore use the current 2.43% market yield as an indication rather than an estimate of the exact cut-off yield.
Buying the 15-year SGS bond: Better than Singapore Savings Bonds?
The latest Singapore Savings Bond offers:
- A first-year return of 1.65%
- An average return of 2.32% per year over 10 years
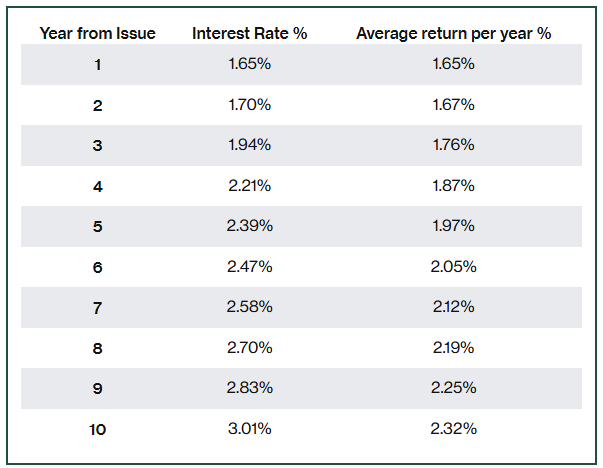
Based on these rates, the reopened 15-year SGS bond may offer a slightly higher return based on its current closing yield of around 2.43%.
However, the Singapore Savings Bond provides more flexibility.
SSBs can be redeemed in any month, with investors receiving their principal amount and accrued interest.
In comparison, the SGS bond does not provide monthly redemption at face value.
An investor who wants to exit before July 2040 would have to sell the SGS bond in the secondary market. The price received may be higher or lower than the amount paid.
The comparison may also become closer with the next SSB issuance.
While the current SSB offers a 10-year average return of 2.32%, the next SSB issuance is currently projected to offer a 10-year average return of above 2.4%.
This would put the next SSB's projected return close to the 15-year SGS bond's current closing yield of around 2.43%, while offering the flexibility to redeem before maturity without having to sell in the secondary market.
For investors who value this flexibility, the next SSB may therefore be worth considering alongside the 15-year SGS bond, although its final interest rates may still change.
Buying the 15-year SGS bond: Better than T-bills and fixed deposits?
The latest 6-month T-bill offered a cut-off yield of 1.70%, while the latest 1-year T-bill offered 1.68%.
Currently, the best 6-month fixed deposit rate we found is at 2.00% p.a.
Hence, the 15-year SGS bond may offer a higher yield for investors who are comfortable with the longer commitment.

What are the risks of the 15-year SGS bond?
#1 – Potential losses if sold before maturity
The main risk is that investors may incur a loss if they sell the SGS bond before it matures on 1 July 2040.
The market price of an SGS bond moves as interest rates change. If market yields rise after the auction, the price of the bond may fall.
In this case, an investor who needs to sell the bond before maturity may receive a price that is lower than the price paid at the auction.
For example, if an investor pays S$97.89 for every S$100 in principal and later sells the bond below that purchase price, the investor may suffer a capital loss.
#2 – Liquidity risk
There may also be limited liquidity in the secondary market if an investor decides to sell the bond before maturity.
If there are few interested buyers, investors may not be able to sell the bond immediately or at their desired price.
This could increase the risk of receiving less than the purchase price, especially if the funds are needed urgently.
Investors who want to reduce the risk of a capital loss should therefore be prepared to hold the SGS bond until it matures on 1 July 2040.
What would Beansprout do?
The reopened 15-year SGS bond (NY25200N) currently has a closing yield of around 2.43%.
The 15-year SGS bond may offer a higher yield compared to the 6-month T-bill and fixed deposit. However, it also requires a longer commitment period, and I would be mindful about potential losses if I decide to sell the bond before maturity.
This makes the 15-year SGS bond less likely to be something I'd consider for my Liquidity Pot within Beansprout's four pots of wealth.
Find out what yield to expect from the upcoming 6-month T-bill auction on 24 September 2026 here.
I would also keep an eye on the next Singapore Savings Bond.
While the current SSB offers a 10-year average return of 2.32%, the next SSB is projected to be above 2.4% over 10 years.
This is very close to the 15-year SGS bond's current closing yield of 2.43%, while the SSB offers the flexibility to redeem before maturity without having to sell in the secondary market.
For investors who value this flexibility, the next SSB may therefore be worth considering alongside the 15-year SGS bond.
It is also worth noting that the eventual cut-off yield of the 15-year SGS bond will depend on market movements and the bids submitted at the auction.
How do I apply for the 15-year SGS bond?
The 15-year Singapore Government Securities (SGS) bond auction is currently open.
The auction will take place on 28 September 2026.
As cash applications for the 15-year Singapore Government Securities (SGS) bond close one business day before the auction date, we would need to put in our cash applications by 9pm on 25 September, as 26 and 27 September are weekends.
If you prefer a shorter investment period and are comfortable holding your investment until maturity, you may consider Singapore T-bills. Read our guide to SGS bonds and T-bills to learn how they work and how to apply.
If you value the flexibility to redeem your investment in any month without being exposed to market price movements, you may consider Singapore Savings Bonds instead. Read our SSB guide to know more.
Would you consider the reopened 15-year SGS bond at a yield of around 2.43%, or would you prefer the flexibility of T-bills and SSBs? Share with us in the comments below or in our Telegram group!
Enjoyed this insight? Follow Beansprout on Telegram, Youtube, Facebook and Instagram, and add Beansprout as your preferred source on Google so you never miss an update.
Read also
Gain financial insights in minutes
Subscribe to our free weekly newsletter for more insights to grow your wealth
Most Popular

Comments
0 comments